Back


2026 Supreme(Online)(ITAT) 4418
INCOME TAX APPELLATE TRIBUNAL (PUNE BENCH)
R.K. Panda, Vice-President, Astha Chandra, Judicial Member
Sankalp Munraj Kale – Appellant
Versus
DCIT, Pune – Respondent
ITA No.2248/PUN/2025
For the Appellants/Petitioners: Shri Bharat Shah
For the Respondents: Shri Gaurav K Singh
Penalty u/s 270A for misreporting invalid if notice u/s 274 fails to specify applicable limb of s.270A(9)(a)-(f); mere 'misreporting' reference without particulars vitiates proceedings.
Headnote:(A) Income Tax Act, 1961 - Sections 270A, 274, 80GGC - Penalty for under-reporting of income in consequence of misreporting - Assessee claimed deduction for donation without documentary evidence, leading to disallowance and penalty at 200% of tax on under-reported income - Penalty notice u/s 274 r.w.s. 270A failed to specify which limb of section 270A(9)(a) to (f) was attracted - No indication in assessment order or penalty proceedings as to how ingredients of section 270A(9) were satisfied - Mere reference to 'misreporting' without pinpointing specific clause renders penalty proceedings invalid and arbitrary - Penalty liable to be deleted. (Paras 2, 4, 6, 7, 9)
(B) Penalty Proceedings - Strict construction required - Assessing Officer must establish under-reporting resulted from specific misreporting as per statutory clauses - Failure to identify applicable limb vitiates entire proceedings, following judicial precedents emphasizing legislative intent and principles of natural justice. (Paras 7, 8, 9)
Facts of the case:
Assessee, an individual, filed return claiming deduction for donation to political party u/s 80GGC without evidence; addition made on scrutiny, penalty initiated for misreporting without specifying section 270A(9) limb; assessee accepted quantum but challenged penalty on procedural grounds; lower authorities confirmed penalty ex-parte.
Findings of Court:
Penalty of Rs.34,64,740/- not exigible due to defective notice lacking specificity on misreporting limb under section 270A(9); proceedings vacated following coordinate bench decisions.
Issues: Whether penalty u/s 270A sustainable absent specification of misreporting limb in notice u/s 274 and assessment order; validity of 200% penalty without linking to section 270A(9)(a)-(f).
Ratio Decidendi: Penalty under section 270A for misreporting requires Assessing Officer to explicitly identify applicable clause from section 270A(9); generic reference to misreporting without particulars contravenes statutory mandate, rendering levy arbitrary and unsustainable.
Result: Appeal allowed; impugned penalty vacated.
| Table of Content |
|---|
| 1. facts of assessment and penalty levy under section 270a. (Para 1 , 2 , 3) |
| 2. assessee's arguments on defective penalty notice. (Para 4 , 5) |
| 3. penalty invalid without specifying 270a(9) limb. (Para 6 , 7 , 8) |
| 4. penalty vacated; assessee's appeal allowed. (Para 9 , 10) |
आदेश/ORDER
PER ASTHA CHANDRA, JM :
The appeal filed by the assessee is directed against the order dated 22.07.2025 of the Ld. Commissioner of Income Tax (Appeals)/NFAC, Delhi [“CIT(A)”] wherein he has confirmed the penalty of Rs.34,64,740/- levied by the Ld. Assessing Officer (“AO”) u/s 270A of the Income Tax Act, 1961 (the “Act”) pertaining to Assessment Year (“AY”) 2022-23.
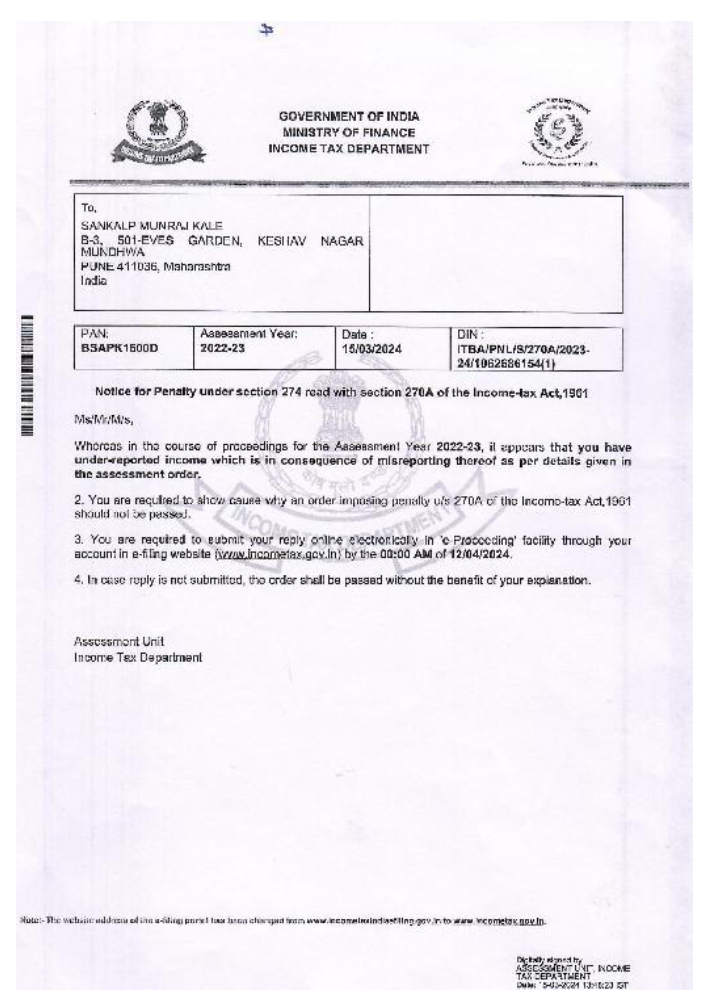
2. Briefly stated, the facts of the case are that the assessee is an individual and was employed with M/s. Nvidia Graphics Private Limited during the AY 2022-23. For AY 2022-23, he filed his return of income on 30.06.2022 declaring total income of Rs.66,29,320/- after claiming deduction of Rs.52,54,000/- comprising of : (i) donation of Rs.51,00,000/- u/s 80GGC; (ii) Rs.15,000/- u/s 80C and (iii) Rs.4,000/- u/s 80D of the Act. The case of the assessee was selected for scrutiny under CASS for the reason “verification of deduction from total income” (Chapter VI-A) (Non business ITR). During the course of assessment proceedings, the assessee could not submit any documentary evidence in respect of his claim of deduction u/s 80GGC for donation of Rs.51,00,000/- made to a political party. The Ld. AO therefore completed the assessment by making an addition of Rs.51,00,000/- and determined the total income of the assessee at Rs.1,17,29,320/-. Thereafter, the Ld. AO initiated penalty proceedings u/s 274 r.w.s. 270A of the Act vide issue of notice dated 15.03.2024 on account of underreporting of income in consequence of misreporting. During the penalty proceedings, the assessee failed to submit reply to the said show cause notice, however, he filed part response to the letter of the Ld. AO issued on 24.05.2024. The reply of the assessee was not found to be tenable by the Ld. AO and citing the reasons that the assessee did not file any appeal against the assessment order which clearly establish that the assessee willfully made default by underreporting of income by misreporting, he levied penalty of Rs.34,64,740/- being 200% of tax payable on underreported income u/s 274 r.w.s. 270A of the Act vide his order dated 02.08.2024.
3. On appeal, the various notices of hearing issued by the Ld. CIT(A)/NFAC remained un-complied with by the assessee which resulted into an ex-parte order passed by the Ld. CIT(A)/NFAC for non-prosecution. On merits, the Ld. CIT(A)/NFAC affirmed the action of the Ld. AO in imposing penalty of Rs.34,64,740/- u/s 270A of the Act due to lack of any response/submission/documentary evidence filed by the assessee to substantiate his case despite several opportunities granted to the assessee.
4. Aggrieved, the assessee is in appeal before the Tribunal raising the following grounds of appeal :
“1) The authorities below erred in the facts and circumstances of the case, and as per the law in levying and confirming the penalty of Rs. 3464740 under section 270A. The penalty so levied and confirmed by authority below be cancelled. Just and proper relief be granted to the assessee in this respect.
2) The authorities below erred in the facts and circumstances of the case, and as per the law, in levying and confirming the penalty on account of under-reporting of income in consequence of misreporting, without a specific limb and subsection and clause under which the penalty is levied and hence the penalty so levied and confirmed by the authorities below be cancelled. Just and proper relief be granted to the assessee in this respect.
3) The appellant prays to be allowed to add, amend, modify, rectify, delete, or raise any ground of appeal before or at the time of the hearing.”
5. The Ld. AR submitted that the assessee has accepted the quantum addition made by the Ld. AO and has also paid the