Back


2026 Supreme(Online)(ITAT) 7560
INCOME TAX APPELLATE TRIBUNAL (CHENNAI BENCH)
ABY T. VARKEY, Judicial Member, PADMAVATHY.S, Accountant Member
Joyson Anand Abhishek Safety Systems Pvt. Ltd. – Appellant
Versus
Dy. Commissioner of Income Tax – Respondent
ITA No.2252/Chny/2024 | IT(TP)A No.46/Chny/2024 | C.O No.02/Chny/2025
For the Appellants/Petitioners: Mr. Vikram Vijayaraghavan
For the Respondents: Mr. P. Krishna Kumar, Addl. CIT
Remitted TP adjustments for forex loss, customs duty, capacity utilization, and liability write-backs to TPO for fresh verification per consistent practice and R.10B.
Headnote:The Income Tax Act, 1961 governs transfer pricing adjustments under S.92C, requiring arm's length price determination for international transactions using comparable uncontrolled price method. Assessee engaged in manufacturing safety products reported losses with international transactions exceeding Rs.1.79 crores; TPO proposed adjustment of Rs.51 crores, revised by CIT(A) to Rs.8.37 crores after allowing certain adjustments. Tribunal found lower authorities erred in rejecting assessee's consistent treatment of forex losses, customs duty, and other economic adjustments without proper adjudication. Key issues framed: Whether single-year data violates CBDT Notification No.83/2015; validity of economic adjustments for forex loss, customs duty, capacity utilization, price penetration; treatment of liability write-backs as operating income. Ratio: Consistent historical treatment of forex as non-operating accepted in prior/subsequent years must be considered; adjustments under R.10B(3) permissible for material differences affecting margins, but require verification of impact on profitability; cash PLI appropriate where depreciation skews margins due to underutilization. Appeals of assessee and revenue allowed for statistical purposes; multiple issues remitted to TPO for fresh adjudication with opportunities to assessee; CO dismissed as academic.
| Table of Content |
|---|
| 1. cross appeals on tp adjustments from cit(a) order (Para 1 , 2 , 3) |
| 2. remit forex loss treatment for consistent non-operating classification (Para 4 , 5 , 6 , 7 , 11) |
| 3. remit customs duty adjustment for cost impact verification (Para 8 , 9 , 12) |
| 4. remit price penetration adjustment for quantitative details (Para 13) |
| 5. uphold trade payables write-back as operating; remit others (Para 14 , 15 , 16 , 17) |
| 6. direct cash pli computation excluding depreciation (Para 18 , 19 , 20) |
| 7. appeals allowed statistically; co dismissed (Para 21 , 22) |
आदेश/ORDER
PER PADMAVATHY.S, A.M:
These cross appeals by the assessee and the Revenue and the Cross Objections (COs) of the assessee are against the order of Commissioner of Income Tax (Appeals), Chennai-16 (in short "the CIT(A)") passed u/s. 250 r.w.s 254 of the Income Tax Act, 1961 (in short "the Act") dated 28.06.2024 for Assessment Year (AY) 2014-15. The grounds raised by the assessee are as given below:
“Issue no. 1-Prejudicial to the interest of the Appellant:
The Ld. TPO, the Ld. AO and Ld. CIT(A) have erred, in facts and in circumstances of the case and in law by rejecting the analysis undertaken by the Appellant to determine the arm's length price, thereby proposing an adjustment of INR 8,37,88,625 in respect of the international transactions of the Appellant and not considering all the legal and factual submissions filed
Issue no. 2-Adoption of single year financial data for the arm's length analysis
The Ld. TPO/AO and Ld. CIT(A) have erred, in law and in facts, by determining the arm's length margin using only single financial year ("FY") data ie. FY 2013-14 which was not available to the Appellant at the time of complying with the transfer pricing documentation requirements and not allowing the usage of multiple year data against the principles laid out in the Indian transfer pricing and in violation of the guidelines as notified by the CBDT vide Notification No. 83/2015 [F.No. 142/25/2015- TPL] dated 19 October 2015 with regard to use of multiple year data and use of percentile range concept, while determining the arm's length price.
Issue No. 3-Disregarding the economic analysis
The Ld. TPO/AO and Ld. CIT(A) have erred, in laws and in facts and in circumstances of the case by not appreciating the benchmarking analysis of the international transactions and rejecting the economic analysis undertaken by the Appellant to determine the arm's length margin, thereby proposing an adjustment of INR 8,37,88,625 and not considering all the legal and factual submissions filed.
The Appellant prays that the Ld. TPO/AO and Ld. CIT(A) be directed to accept the economic analysis undertaken by the Appellant in the documentation maintained and submitted in respect of its international transactions and consequently accept the arm's length margin determined by the Appellant.
Issue No. 4-Rejection of Foreign exchange loss adjustment
The Ld. TPO/AO and Ld. CIT(A) has erred in considering the foreign exchange loss as operating item while computing the operating margin of the Appellant and not appreciating the fact that, during FY 2013-14, the Rupee depreciated rapidly vis-à-vis major currencies such as USD and EURO within a short notice and the effects were outside of the control of the Appellant and accordingly the forex loss should be treated as a non- operating item.
Issue No. 5-Rejection of economic adjustments:
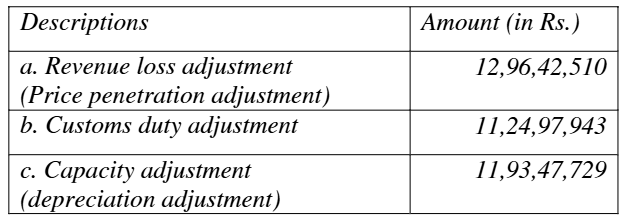
The Ld. TPO/AO and Ld. CIT(A) has grossly erred, in laws and facts, by not appreciating the business/economic circumstances faced by the Appellant and consequently rejected the economic adjustments claimed by the Appellant while computing the operating margins as under a. Customs duty adjustment:
The Ld. TPO and Ld. CIT(A) has erred by not adjusting for the differences in the import duty and other related costs of the appellant vis-à-vis the selected comparable companies.
b. Price penetration adjustment
The Ld. TPO and Ld. CIT(A) has erred by not providing adjustment for price penetration strate