Back


2026 Supreme(Online)(ITAT) 7652
INCOME TAX APPELLATE TRIBUNAL (HYDERABAD BENCH)
Ravish Sood, J, Madhusudan Sawdia, Accountant Member
Surender Kumar Bhojwani – Appellant
Versus
Income Tax Officer – Respondent
I.T.A. No.2086/Hyd/2025
For the Appellants/Petitioners:Shri A V Raghuram, Advocate, Dr. Sachin Kumar, Sr. AR
Landowner's agreed share of constructed residential units under development agreement qualifies as investment in new residential house for s.54F deduction; claim allowable in reassessment appeal if linked to escaped capital gains, even if not in original return.
Headnote:(A) Income Tax Act, 1961 - Sections 147, 143(3), 54F - Reassessment proceedings - Capital gains on transfer of land via development agreement - Assessee's share in constructed bungalows qualifies as investment in construction of new residential house for deduction u/s 54F - Claim not raised in original or s.148 return allowable in appellate proceedings if relatable to escaped income and material on record - Authorities below erred in denying deduction for lack of claim in return and evidence within time frame, as rights under agreement constitute deemed investment. (Paras 9-17)
(B) Reassessment - Scope - Proceedings for revenue's benefit; assessee cannot reagitate concluded matters or claim unrelated deductions, but claims directly linked to escaped income (here, capital gains) permissible even if not claimed earlier - Supported by Supreme Court in reassessment not wiping out original assessment entirely. (Paras 10-11)
Facts of the case:
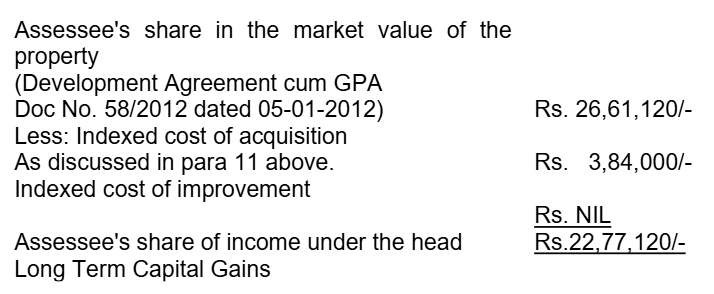
Non-Resident Indian assessee purchased vacant land, entered registered Development Agreement with developer for constructing individual bungalows with 48:52 sharing ratio favouring developer. AO treated assessee's 48% project share as long-term capital gains Rs.22,77,120/- in s.143(3) r.w.s.147 reassessment; CIT(A) upheld. Assessee claimed before Tribunal that share in bungalows qualifies for s.54F deduction.
Findings of Court:
AO directed to readjudicate claim for s.54F deduction, treating assessee's agreed share in constructed bungalows as investment in residential house construction; LTCG exempt subject to s.54F preconditions.
Issues: (1) Permissibility of raising s.54F claim in reassessment appellate proceedings not made in returns; (2) Whether land-owner's share in constructed units under development agreement qualifies as investment for s.54F deduction.
Ratio Decidendi: Assessee can raise s.54F claim relatable to escaped capital gains despite not claiming in returns, per scope of s.147; developer's construction of allotted residential units on behalf of landowner constitutes qualifying investment under s.54F, following High Court precedents on JDAs.
Result: Appeal allowed for statistical purposes; matter remitted to AO for allowing s.54F claim.
| Table of Content |
|---|
| 1. background of reassessment and ltcg addition on dagpa. (Para 6 , 7) |
| 2. parties' contentions on section 54f deduction claim. (Para 8 , 9 , 10) |
| 3. reassessment proceedings allow escaped income-related claims. (Para 11) |
| 4. appellate authorities can consider new claims with evidence. (Para 12 , 13 , 14 , 15) |
| 5. jda share in constructed residential units qualifies for 54f. (Para 16 , 17) |
| 6. appeal allowed; remand for 54f recomputation. (Para 18) |
ORDER
PER RAVISH SOOD, JM:
The present appeal filed by the assessee is directed against the order passed by the Commissioner of Income Tax (Appeals)-10, Hyderabad, dated 09/09/2025, which in turn arises from the order passed by the Assessing Officer (for short, “AO”) under section 143(3) r.w.s 147 of the Income Tax Act, 1961 (for short, “the Act”), dated 21/11/2019 for the Assessment Year (AY) 2013-14. The assessee has assailed the impugned order of the CIT(A) on the following grounds of appeal:
“1. On the facts and in the circumstances of the case, the order of the Id. CIT(A) is erroneous both on facts and in law.
2. The Id. CIT(A) erred in sustaining the addition made by the AO of Rs.22,77,120 as undisclosed income under the head Long Term Capital Gains' on entering into development agreement.
3. The Id. CIT(A) erred in denying the deduction u/s.54F of Act on the alleged ground that the appellant has not claimed any deduction in the return of income filed in response to notice issued u/s.148 of the Act and further has not filed any evidence in support of investment of sale consideration in the residential unit within the time frame as prescribed by the Act for claiming exemption u/s.54F of the Act.
4. The authorities below failed to appreciate that the requirement of section 54F of the Act is investment within three years in respect of construction, and in so far as the appellant is concerned, there is a deemed investment as per the entire entitlement by virtue of development agreement. The authorities below ought to have appreciated that the rights granted under development agreement is only on the condition that the appellant will be given developed area.
5. Without prejudice to the above grounds, the Id. CIT(A) erred in sustaining the action of the AO in computing capital gains on the entire value of development agreement. The authorities below failed to appreciate that the value of undivided land retained by the appellant in development agreement cannot be considered as it always belonged to the appellant, and what is to be considered is the value of land surrendered in the development agreement.
6. Any other ground that may be urged at the time of hearing.”
2. Succinctly stated, the assessee, a Non-Resident Indian (NRI), had filed his return of income for AY 2012-13 declaring an income of Rs. 26,04,670/-.
3. Thereafter, the case of the assessee was reopened under section 147 of the Act. Notice under section 148 of the Act, dated 28/03/2019, was issued to the assessee. In compliance, the assessee filed his return of income declaring an income of Rs. 26,40,670/-, i.e., as was originally returned.
4. During the course of the assessment proceedings, it was observed by the AO that the assessee had purchased vacant land admeasuring 1 Acre vide Document No.1629/2008, dated 11/04/2008, for a consideration of Rs. 5,47,500/-. Thereafter, the assessee had, during the year under consideration, vide Document No.58/2012, dated 05/01/2012, entered into a Development Agreement-cum-General Power of Attorney (DAGPA) registered with SRO, Shankerpally, with M/s. SARK Projects for the development of the aforementioned land into “individual bungalows” with a sharing ratio of 48:52 in favour of the developer. The AO observed that the assessee’s share in DAGPA worked out at Rs. 26,61,120/-, being 48% of the project cost.
5. The AO vide his order passed under section 143(3) r.w.s 147 of the Act, dated 20/11/2019, determined the capital gains with respect to the aforesaid property transaction entered into by