Back


2026 Supreme(Online)(ITAT) 7999
INCOME TAX APPELLATE TRIBUNAL (PUNE BENCH)
Astha Chandra, Judicial Member, Dipak P. Ripote, Accountant Member
Bosch Chassis Systems India (P.) Ltd. – Appellant
Versus
DCIT, Circle-1(1), Pune – Respondent
ITA No.1935/PUN/2024
For the Appellants/Petitioners: Shri Darpan Kirpalani
For the Respondents: Shri Prakash L Pathade
'Other Method' under Rule 10AB requires comparable uncontrolled transaction; ad hoc ALP determination invalid. Safe Harbour Rules inapplicable without assessee opt-in. TNMM aggregation upheld, rejecting separate benchmarking to prevent double adjustment.
Headnote:(A) Income Tax Act, 1961 - Sections 92CA, 92C, 143(3), 144C, 144B - Income Tax Rules, 1962 - Rules 10AB, 10TA(j), 10TA(k) - Transfer pricing - International transactions - Assessee applied TNMM with aggregation approach for benchmarking trademark fee, lumpsum license fee, intra-group services - Authorities rejected TNMM, applied 'Other Method' under Rule 10AB without comparable uncontrolled transactions, determined ALP at Nil - Safe Harbour Rules applied for segmental allocation despite no opt-in - Tribunal held 'Other Method' requires comparable uncontrolled transaction under Rule 10AB, ad hoc ALP determination invalid; Safe Harbour Rules inapplicable without assessee's option; TNMM with aggregation upheld, double adjustment impermissible; assessee's cost allocation keys accepted. (Paras 10, 14-17, 19, 22, 26)
(B) Transfer pricing - Segmentation - Manufacturing and trading segments - Allocation keys based on actuals, material cost, production ratios rejected; sales/turnover based reallocation using Safe Harbour definitions unsustainable without assessee opting in - Assessee's methodology reasonable, not disturbed in prior years. (Paras 9-11)
(C) Transfer pricing - Intra-group services - Documentary evidence (invoices, agreements, emails) submitted demonstrating benefit - Standalone benchmarking after aggregation under TNMM leads to double adjustment - Costs linked to manufacturing allocated per assessee's method. (Paras 12-14)
Facts of the case:
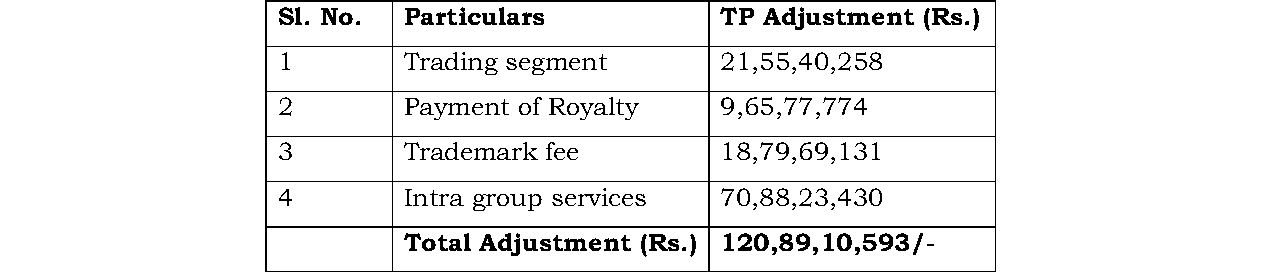
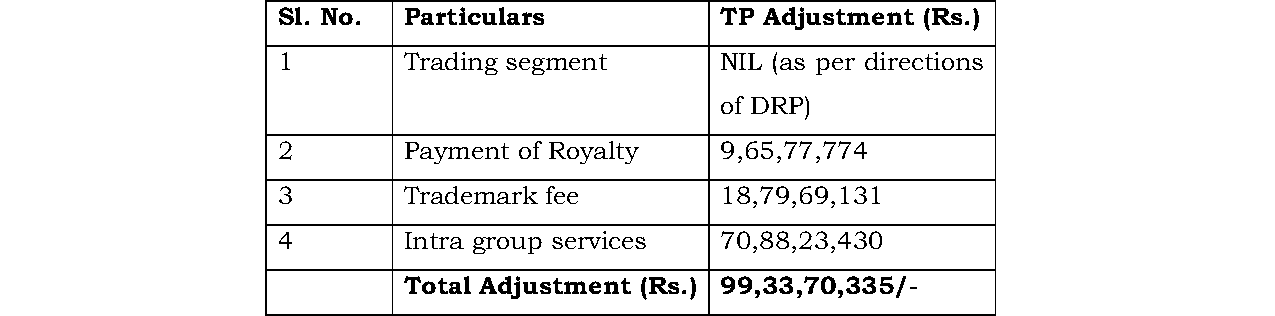
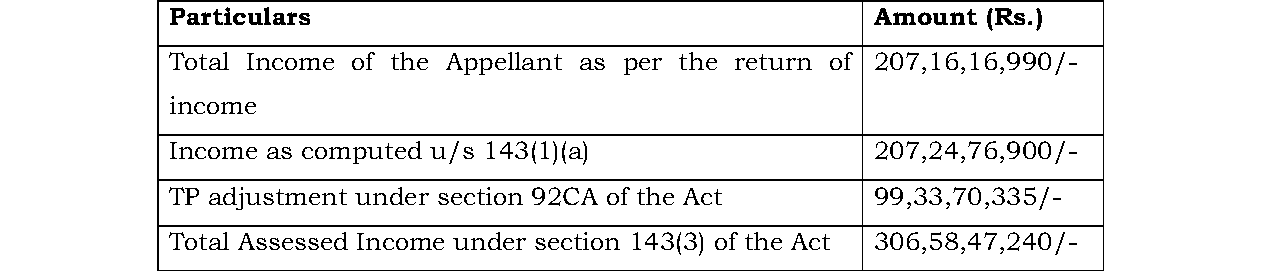
Assessee, engaged in manufacturing and trading, entered international transactions including trademark fee, lumpsum license fee, intra-group services - TP study used TNMM (11.73% manufacturing, 4.76% trading margins), aggregated linked transactions - TPO proposed adjustments totalling over Rs.120 crores, reduced partially by DRP; final order added ~Rs.99 crores to income.
Findings of Court:
All TP adjustments deleted - TNMM accepted; 'Other Method' and Safe Harbour applications invalid; assessee's segmentation/allocation upheld post verification.
Issues: Validity of rejecting TNMM/aggregation, applying 'Other Method' without comparables, Safe Harbour for allocation, double adjustments, commercial justification of transactions.
Ratio Decidendi: 'Other Method' under Rule 10AB mandates comparable uncontrolled transaction, ad hoc Nil ALP unsustainable; TPO cannot invoke Safe Harbour suo motu; aggregation under TNMM precludes separate benchmarking to avoid double adjustment; assessee's reasonable allocation keys prevail absent rationale for rejection.
Result: Appeal partly allowed.
| Table of Content |
|---|
| 1. factual background and procedural history outlined. (Para 1 , 2 , 3 , 4 , 5) |
| 2. assessee's arguments on distribution segment allocation. (Para 6 , 7 , 8 , 9) |
| 3. safe harbour rules inapplicable without assessee option. (Para 10 , 11) |
| 4. intra-group services benchmarked under tnmm upheld. (Para 12 , 13 , 14) |
| 5. other method invalid without comparable transactions. (Para 15 , 16 , 17 , 18 , 19) |
| 6. lumpsum license fee adjustment deleted for lack of comparables. (Para 20 , 21 , 22) |
| 7. trademark fee accepted under tnmm, no double adjustment. (Para 23 , 24 , 25 , 26) |
| 8. appeal partly allowed; penalty premature. (Para 27 , 28 , 29) |
ORDER
PER ASTHA CHANDRA, JM :
The appeal filed by the assessee is directed against the final assessment order dated 25.07.2024 passed by the Ld. Assessing Officer (“AO”) u/s 143(3) r.w.s. 144C(13) r.w.s. 144B of the Income Tax Act, 1961 (the “Act”) in pursuance of the direction of the Dispute Resolution Panel (“DRP”), Mumbai dated 22.06.2024 issued u/s 144C(5) of the Act pertaining to Assessment Year (“AY) 202021.
2. The assessee has raised the following grounds of appeal :
“General Ground
1. On the facts and in the circumstances of the case and in law. final assessment order passed by the Assessment Unit Income-tax Department (the learned Assessing Officer' or the learned AO) under section 143(3) r.w.s. 144C(13) r.w.s. 1448 of the Income tax Act, 1961 (the Act) in pursuance to the order of the Deputy Commissioner of Income-tax, Transfer Pricing. 1(1) (the learned Transfer Pricing Officer or the learned TPO), and the directions of the Hon'ble Dispute Resolution Panel-3. Mumbai (Hon'ble DRP or DRP), to the extent prejudicial to the Appellant is bad in law and is liable to be quashed.
2. That the draft order dated 29 September 2023 issued under section 144C(1) read with section 143(3) read with section 1448 of the Act by the Assessment Unit for AY 2020-21 is barred by Imitation and therefore, all consequent proceedings pursuant thereto, including the directions passed by the Hon'ble DRP and the final assessment order are all barred by limitation, void-ab-nitio, bad in law and liable to be quashed.
3. That the Document Identification Number allotted to the directions dated 22 June 2024 issued by The Hon'ble DRP cannot be authenticated on the e-portal of the Income-tax department, and therefore the directions issued are not in line with the Circular No. 19/2019 dated 14 August 2019 issued by the Central Board of Direct Taxes, thus rendering the directions invalid and consequently the final assessment order passed by the learned AO is bad in law.
4. On the facts and in circumstances of the Learned AO erred in issuing an email communication to pay a demand of INR 39.96.67,443 despite the fact that the demand notice issued by himself under section 156 of the Act indicates a Nil demand. Grounds relating to Transfer Pricing (TP)
5. On the facts and in circumstances of the case and in law, the Hon'ble DRP/learned AO/learned TPO erred in not accepting the TP Study/economic analysis (including the aggregation approach) undertaken by the Appellant for the determination of the Arm's Length Price (ALP) for the international transactions, and erred in conducting a fresh economic analysis.
6. On the facts and in circumstances of the case and in law, the Hon'ble DRP/Learned AO/Learned TPO have erred in not appreciating the fact that the Appellant had deducted and deposited the applicable withholding taxes in relation to the payments of Trademark fee, Lumpsum license fee and availing of intra-group services. Further, the Associated Enterprises (AEs) have disclosed the payments made by the Appellant viz, trademark fee, license fee and intra group services as income in its Income-tax Return and discharged necessary taxes in India, consequently, any adjustment made to the said payments would lead to double taxation in India.
7. On the facts and circumstances of the case and in law the Hon'ble DRP/Learned AO/Learned TPO have erre