Back





2026 Supreme(Online)(ITAT) 8552
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
Amit Shukla, JM, Arun Khodpia, AM
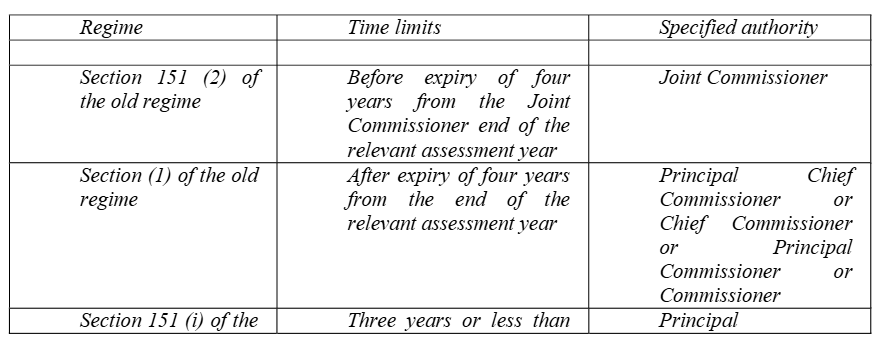
Prashant Jayantilal Patel – Appellant
Versus
ITO, Ward-13(3)(1) – Respondent
I.T.A. No.6952/Mum/2025
For the Appellants/Petitioners: Shri Kumar Kale, AR
For the Respondents: Smt. Virabhadra Mahajan, Sr. DR
Reassessment notice u/s 148 issued after three years invalid if prior approval obtained from Principal Commissioner instead of Principal Chief Commissioner as required under section 151(ii), vitiating jurisdiction and quashing proceedings.
Headnote:(A) Income Tax Act, 1961 - Sections 147, 148, 148A, 151 - Reassessment proceedings - Notice u/s 148 issued after three years from end of relevant assessment year (08.04.2022 for AY 2018-19) - Prior approval obtained from Principal Commissioner instead of Principal Chief Commissioner as mandated by section 151(ii) - Approval invalid as sanction must be from higher authority when more than three years elapsed - Non-compliance vitiates jurisdiction - Consequential assessment order quashed. (Paras 4, 6, 7, 9)
(B) Income Tax Act, 1961 - Section 151 - Specified authority - Time elapsed from end of assessment year determines approving authority - Post three years, Principal Chief Commissioner or equivalent required - Relaxation under TOLA does not alter section 151 requirements - Sanction from wrong authority renders notice and proceedings bad in law. (Paras 6, 14, 19)
Facts of the case:
Assessee engaged in share trading filed return declaring income which was accepted under section 143(3). Case reopened post three years via notice u/s 148 dated 08.04.2022 based on information under Risk Management Strategy, with approval from Principal CIT. Assessment completed adding business loss disallowance from penny stock transactions. CIT(A) upheld. Assessee challenged validity of reopening.
Findings of Court:
Reassessment notice u/s 148, order u/s 148A(d) and consequential assessment proceedings held invalid due to approval from unauthorized authority under section 151(ii). Entire reopening quashed without adjudication on merits.
Issues: Whether reassessment notice u/s 148 issued after three years valid without prior approval from Principal Chief Commissioner as per section 151(ii); whether defect curable.
Ratio Decidendi: Approval under section 151 is precondition for jurisdiction u/s 148 - For cases beyond three years, higher authority mandatory - Sanction from Principal Commissioner invalidates proceedings, following Supreme Court and High Court precedents on strict compliance.
Result: Appeal allowed; reassessment proceedings set aside and quashed.
| Table of Content |
|---|
| 1. factual background of reassessment and appeal. (Para 2 , 3) |
| 2. assessee challenges s.151 approval validity. (Para 4) |
| 3. court analyzes precedents on s.151(ii) approval requirement. (Para 5 , 6 , 7) |
| 4. reassessment quashed due to invalid approval. (Para 8 , 9) |
ORDER
Per Arun Khodpia, AM:
The captioned appeal is preferred by the assessee against the order of Commissioner of Income Tax (Appeals)/National Faceless Appeal Centre (NFAC), Delhi [in short “Ld. CIT(A)”] dated 29.09.2025 for the Assessment Year (AY) 2018-19, which in turn arises from the assessment order under section 147 r.w.s. 144B of the Income Tax Act, 1961 (the Act) dated 19.03.2024 passed by the Assessment Unit, Income Tax Department. The grounds of appeal raised by the assessee are as under:
“1. On the facts and in the circumstances of the case, and in law, the Ld. CITIA) erred in upholding legal validity of the reassessment proceedings u/s.147 of the Act. The appellant submits that the reassessment proceedings u/s.147 is bad in law in as much as:
(a) the notice u/s. 148 dated 08.04.2022 ought to have been issued by the Assessment Unit, National Faceless Assessment Centre, Delhi instead of Assistant Commissioner of Income Tax Officer, Circle 4(2)(1), Mumbai;
(b) the said notice was issued with prior approval of the Pr. CIT-4, Mumbai instead of Pr. CCIT, Mumbai as per mandate of section 151 of the Act, and
(c) Mandate of section 148A was not followed by the Ld. AO.
Your appellant, therefore, prays that the assessment order u/s.147 read with Section 144B of the Act dated 19.03.2024 be quashed
2. On the facts and in the circumstances of the case, and in law, the Ld. CITIA) erred in upholding the disallowance of loss of Rs.6,96,118/- incurred by the appellant on account of transactions in two scrips, viz., Stampede Capital Ltd. and Alora Trading Company Ltd.. The appellant, therefore, prays that the aforesaid disallowance of Rs.6,98,118/- be deleted.”
2. Brief facts of the case are that the assessee is an individual engaged in the business of share trading including Jobbing and Arbitrage. For the year under consideration return of income was filed on 19.10.2018 declaring total income at Rs. 2,49,40,910/-. Subsequently the case of assessee was scrutinized under section 143(3) of the Act and the order came to be passed on 19.04.2021, accepting the returned income of the assessee. Later, on the basis of certain information flagged as per Risk Management Strategy (RMS) formulated by the CBDT, the case of assessee was reopened by issue of notice under section 148 of the Act dated 08.04.2022. The reopening assessment was completed with an addition of Rs. 6,96,118/-, treating the amount of business loss claimed by the assessee from the sale of penny stocks.
3. Aggrieved with the aforesaid addition assessee preferred an appeal before the ld. CIT(A), however was unsuccessful as the ld. CIT(A) had dismissed the appeal of assessee.
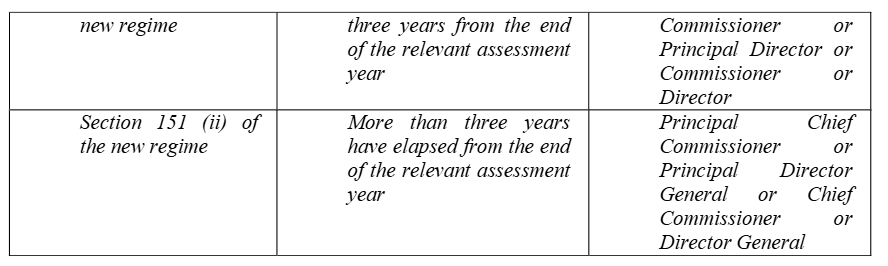
4. Being dissatisfied, the assessee preferred an appeal before us wherein a legal ground challenging the validity of preapproval under section 151 rendered by the PCIT-4, Mumbai was raised before us. The ld. AR submitted that the notice under section 148 dated 08.04.2022 was issued with the prior approval of PCIT-4, Mumbai as accorded on 08.04.2022 vide Reference No. 100000029210392, as mentioned on the impugned notice u/s 148 at para-3. It is submitted that the case of assessee pertains to AY 2018-19 and the notice under section 148 was issued on 08.04.2022, therefore the notice was issued beyond three years (issued after 31.03.20222). thus, as per the provisions in sub-clause (ii) of section 151 of the Act, the approval was to be obtained from the Pr. CCIT instead of PCIT. Since the approval was granted by an authority, who is not empowered by the mandate of law under section 151 of the Act, the notice issued under section 148 of the Act, vitiates and became an invalid. Accordingly, the consequential assessment under section 147 also invalidat