Back


2026 Supreme(Online)(ITAT) 9681
INCOME TAX APPELLATE TRIBUNAL (BANGALORE BENCH)
WASEEM AHMED, Accountant Member, KESHAV DUBEY, Judicial Member
Pepperl & Fuchs Factory Automation Private Limited – Appellant
Versus
Income Tax Officer, Ward – 5(1)(1) – Respondent
Appeal Assessment Year: 2021-22
For the Appellants/Petitioners: Shri Ketan Ved, CA
For the Respondents: Dr. Divya K.J, CIT(DR)
TP adjustments under TNMM require exclusion of dissimilar comparables, economic adjustments for customs duty/working capital differences, and restriction to AE transactions only.
Headnote:(A) Income Tax Act, 1961 - Sections 143(3), 144C(13), 144C(5), Rule 10B - Transfer Pricing - TNMM - Comparability analysis under trading segment - Exclusion of functionally dissimilar comparables (Sumitron Exports Pvt. Ltd., Exodus Information Technologies Pvt. Ltd., Vashi Integrated Solutions Ltd.) due to diversified product profiles, services, and distinction between electrical/electronic products materially impacting margins. (Paras 10-13)
(B) Customs duty adjustment - Non-creditable import duties (9.74% rate, 90.77% import purchases) reduce operating margins compared to domestic-sourcing comparables; requires adjustment for true comparability per Rule 10B. Restored to AO/TPO for verification. (Paras 14-19)
(C) Working capital adjustment - Differences in receivables, payables, inventory affect net margins under TNMM; to be computed using average balances per OECD Guidelines and Rule 10B(1)(e). Restored to AO/TPO. (Paras 20-27)
(D) TP adjustment restriction - Adjustment to be limited to international transactions with AEs only, not extended to third-party transactions, per Chapter X scope. (Paras 28-35)
Facts of the case:
Assessee imports factory automation components from AEs for resale in India; benchmarked trading under TNMM (OP/OC 2.73%); TPO rejected comparables, added others (avg. 4.84%), made upward adjustment Rs.2,14,83,958/-; DRP upheld; ITAT partly allowed appeal.
Findings of Court:
Excluded specified comparables; restored customs duty and working capital adjustments; restricted TP adjustment to AE transactions.
Issues: Selection of comparable companies; grant of import duty/working capital adjustments; scope of TP adjustment.
Ratio Decidendi: Functional dissimilarity excludes comparables with diversified operations/services; economic adjustments (customs duty, working capital) mandatory for material differences; TP adjustments confined to AE transactions to avoid inflating uncontrolled profits.
Result: Appeal partly allowed.
| Table of Content |
|---|
| 1. assessee's tnmm benchmarking rejected by tpo/drp with new comparables. (Para 4 , 5 , 6) |
| 2. exclusion of functionally dissimilar comparables due to product/operation differences. (Para 8 , 9 , 10 , 11 , 12 , 13) |
| 3. customs duty adjustment warranted for import-heavy trading; restored to tpo. (Para 14 , 15 , 17 , 18 , 19) |
| 4. working capital adjustment required under rule 10b; restored with oecd directions. (Para 20 , 21 , 22 , 23 , 25 , 26 , 27) |
| 5. tp adjustment restricted to ae transactions only per high court precedent. (Para 28 , 29 , 30 , 31 , 33 , 34 , 35) |
| 6. appeal partly allowed with directions. (Para 36) |
ORDER
PER WASEEM AHMED, ACCOUNTANT MEMBER:
The present appeal has been instituted by the assessee against the assessment order passed by the AO u/s 143(3) r.w.s. 144C(13) of the Act, in pursuant to the directions of the Ld. DRP issued u/s 144C(5) of the Act dt. 19.09.2024
2. In the memo of appeal, the assessee has raised 07 grounds of appeal and 01 additional ground of appeal challenging the transfer pricing adjustment, which for the sake of brevity and convenience, we are not inclined to reproduced here.
3. Ground No. 2 relate to the rejection of the transfer pricing study documentation furnished by the assessee. We note that the issues raised in these grounds are interconnected with the other transfer pricing grounds adjudicated herein below. The contentions raised therein have been examined and dealt with while deciding the respective substantive grounds. Accordingly, no separate adjudication is called for under this ground of appeal.
4. The issues raised by the assessee in Grounds Nos. 3 and 4 are interconnected and pertain to fresh economic analysis conducted by the TPO and inclusion and exclusion of certain comparables by the TPO and by the Ld. DRP for computing the ALP of the international transactions carried out with the AE.
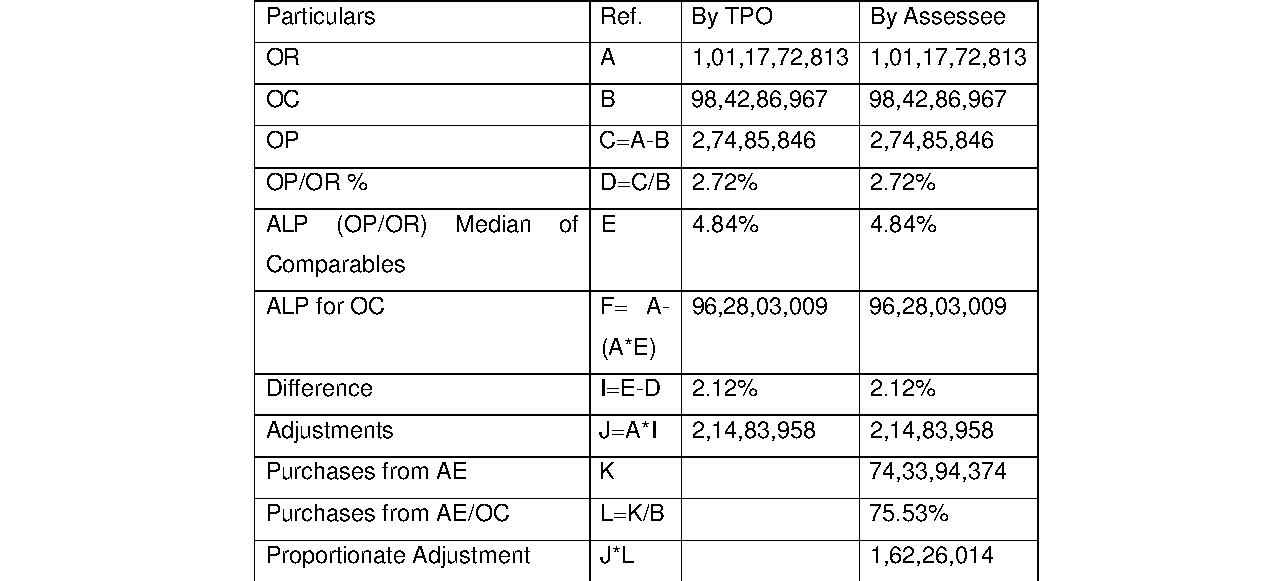
5. The brief facts of the case are that the assessee, a private limited company, is engaged in the business of import/purchase of factory automation components such as proximity switches, connectors, encoders, control equipment, ultrasonic sensors etc from its AEs and selling them to its customers in India. The assessee benchmarked its transaction under trading segment by adopting TNNM as most appropriate method and further PLI as OP/OC which arrived at 2.73% for trading segment. The assessee for the comparability analysis under trading segment selected 08 comparables.
5.1 However, the TPO during the assessment proceeding rejected 06 comparables out of 08 comparables selected by the assessee. The assessee’s comparables accepted by the TPO are detailed as under:
(1) Debak Enterprises Pvt Ltd
(2) Balaji Switch Gears Pvt Ltd
5.2 Thereafter, the TPO applied own filter and selected additional 10 comparables in addition to assessee’s 02 comparables accepted by him.
The final TPO’s comparables are detailed as under:
(1) Debak Enterprises Pvt Ltd (2) Balaji Switch Gears Pvt Ltd (3) Vijayesh Instruments Pvt Ltd (4) Ases Security Pvt Ltd (5) Brisk Electrosales Pvt Ltd (6) Electronika Sales Pvt Ltd (7) S B Syscon Pvt Ltd (8) Sumitron Exports Pvt Ltd (9) Exodus Information Technology Pvt Ltd (10) Vashi Integrated Solutions Ltd (11) Cirkit Electro Components Pvt Ltd (12) Vallabh Impex (India) Pvt Ltd
5.3 The average PLI/margin of the comparables companies was computed at 4.84%. Accordingly, an upward TP adjustment was made by the TPO for Rs. 2,14,83,958/- only by adding to the total income of the assessee.
6. The aggrieved assessee preferred to file objections before the Ld. DRP. Before the Ld. DRP, the assessee submitted that the TPO has erred in selecting certain companies as comparables which are not functionally similar to the assessee. The same is tabulated below:
6.1 However, the Ld. DRP rejected the plea of assessee in this regard by submitting as follows:
7. Aggrieved by the directions of the Ld. DRP, the assessee filed an appeal before us.
8. The Ld. AR before us has filed a paper book running from p