1. Exemption under section 10(46) of Income-tax Act for regulatory authority—Denial of exemption on prior period and other income—Appeal by assessee. (Para 1 , 2 , 3 , 4 , 5 )
 Back
Next 


2026 Supreme(Online)(ITAT) 11417
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
Makarand Vasant Mahadeokar, AM
MAHARASHTRA ELECTRICITY REGULATORY COMMISSION MUMBAI – Appellant
Versus
DY CIT (EXEMPTION)-CIRCLE 2 MUMBAI – Respondent
ITA No. [not specified]
Exemption under section 10(46) of the Income-tax Act attaches to the nature of income, not the year of recognition, and subsequent clarificatory notifications have persuasive value for earlier years; ancillary receipts integrally connected with regulatory functions are also eligible.
Headnote:(A) Income-tax Act, 1961 - Section 10(46) - Exemption for specified income of statutory bodies - Prior period income - Interest on House Building Advance - Incidental receipts - Interpretation of 'specified income' - The exemption under section 10(46) attaches to the nature of income, not the year of recognition; subsequent inclusion of income in notification is clarificatory and has persuasive value for earlier years; ancillary receipts integrally connected with regulatory functions are also eligible for exemption. (Paras 20, 22, 23, 26, 27, 31, 32)
Facts of the case:
The assessee, a statutory regulatory authority under the Electricity Act, 2003, filed its return declaring nil income after claiming exemption under section 10(46). The Assessing Officer restricted the exemption, disallowed prior period income of Rs. 1,10,26,018/- and other income of Rs. 16,70,763/- (including interest on HBA and incidental receipts), holding them not covered by the notification. The CIT(A) confirmed the disallowances except on the tax rate issue.
Findings of Court:
The Tribunal held that prior period income, being intrinsically linked to regulatory functions, retains its exempt character irrespective of timing; interest on HBA and other incidental receipts are eligible for exemption as they arise from non-commercial, incidental activities of the Commission; subsequent inclusion of such income in the notification is clarificatory; the entire addition of Rs. 16,70,763/- is directed to be deleted.
Issues: Whether prior period income and other income (including interest on HBA and minor receipts) qualify for exemption under section 10(46) even if not explicitly mentioned in the notification.
Ratio Decidendi: The exemption under section 10(46) is based on the nature of income; prior period income retains its exempt character; subsequent notifications expanding the scope of eligible income are clarificatory and relevant for interpreting earlier notifications; minor incidental receipts arising from regulatory functions are also exempt.
Result: Appeal allowed.
Legal Category Hierarchy
Table of Contents
2. Assessee contended prior period and other income are exempt as incidental to regulatory functions; Revenue argued not specified in notification. (Para 8 , 13 , 14 , 18 , 19 )
3. Tribunal allowed the appeal, granting exemption under section 10(46) for prior period and other income, deleting additions. (Para 35 , 36 , 37 )
4. Is prior period income eligible for exemption under section 10(46) even if recognized in a different year?
Yes, exemption attaches to the nature of income, not year of recognition; if underlying income is specified, accounting timing does not alter exempt character. (Para 20 , 21 , 22 , 23 )
5. Can income not expressly mentioned in the notification under section 10(46) be exempt based on subsequent inclusion?
Yes, subsequent inclusion is clarificatory; if the nature of income remains identical and arises from non-commercial incidental activities, exemption applies even for earlier years. (Para 26 , 27 , 28 )
6. Are minor incidental receipts from regulatory functions exempt under section 10(46) even if not listed?
Yes, the phrase 'income of the nature' is wider; ancillary receipts integrally connected with specified activities are also exempt. (Para 30 , 31 , 32 , 33 , 34 )
PER MAKARAND VASANT MAHADEOKAR, AM:
This appeal is filed by the assessee against the order dated 06.10.2025 passed by the Commissioner of Income-tax (Appeals), National Faceless Appeal Centre, Delhi[hereinafter referred to as "CIT(A)"], under section 250 of the Income-tax Act, 1961[hereinafter referred to as "the Act"], arising from the assessment order dated 29.01.2021 passed by the Assessing Officer, National e-Assessment Centre, under section 143(3) read with sections 143(3A) and 143(3B) of the Act for the assessment year 2018–19.
Facts in Brief
2. Brief facts of the case are such that the assessee is an AOP constituted on 05.08.1999 under the Electricity Regulatory Commission Act, 1998, subsequently governed by the Electricity Act, 2003, and is entrusted with regulatory functions in the power sector, including tariff determination and protection of consumer interests. The assessee had been notified by the Central Government vide notification dated 01.12.2016 for exemption under section 10(46) in respect of specified income.
3. The assessee filed its return of income on 19.10.2018 declaring total income at Rs. 7,58,87,698/- and, after claiming exemption under section 10(46) of the Act to the same extent, returned nil income. The case was selected for scrutiny under CASS for examining the issue of “Business Income of Trust” and statutory notices under sections 143(2) and 142(1) were issued during the course of assessment proceedings.
4. During the course of assessment proceedings, the Assessing Officer noticed that apart from the specified income covered under notification under section 10(46), the assessee had earned other income aggregating to Rs. 16,70,763/- comprising “Personal use of office vehicle Rs. 3,204/-, Misc. income Rs. 7,206/-, Interest on HBA Rs. 16,55,645/- and Interest on loans to others Rs. 4,708/-”. The assessee submitted that such income, particularly interest on HBA, was subsequently included in the notification for exemption in later years. However, the Assessing Officer held that the assessee “is not eligible for claiming exemption on the income to the tune of Rs.16,70,763/-, in view of S.O. 3605(E) dated 01-12-2016 though it may became eligible for assessment year 2021-22” and accordingly restricted the exemption.
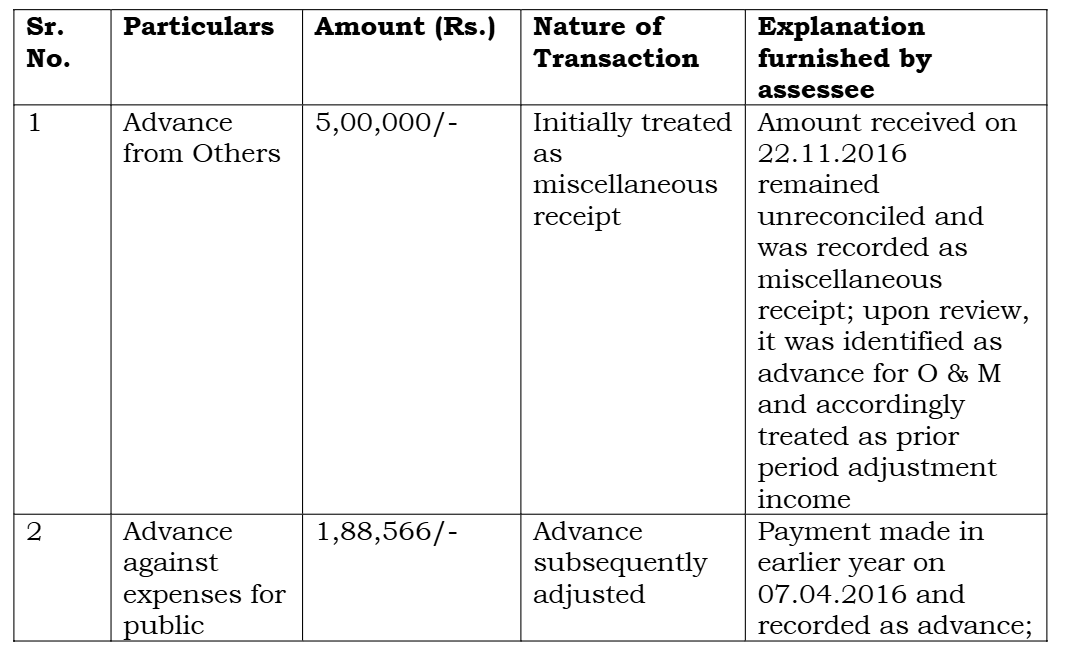
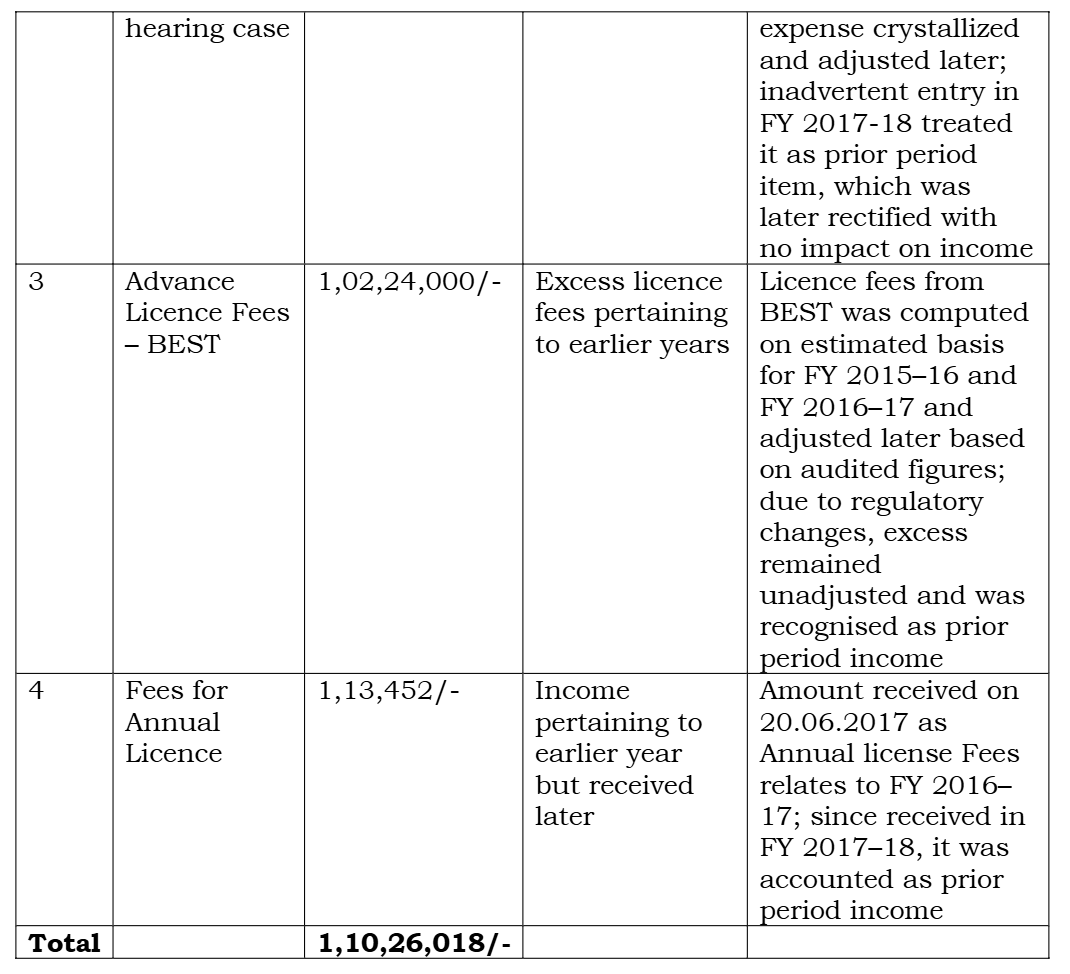
5. The Assessing Officer further observed from the audit report that the assessee had credited prior period income and debited prior period expenses. The assessee submitted details of such prior period adjustments. The Assessing Officer, however, held that since the assessee was following mercantile system of accounting, expenses not pertaining to the year under consideration could not be allowed and, after noting that the assessee had already disallowed Rs. 7,09,16,312/- in its computation, made a further disallowance of Rs. 1,10,26,018/- observing that “income liable to assess in a particular year cannot be postponed”.
6. Further, with regard to payments for professional and technical services, the Assessing Officer observed that against payments of Rs. 4,03,42,593/-, tax was required to be deducted on Rs. 3,44,04,937/-, whereas tax had been deducted only on Rs. 2,12,67,256/-, resulting in non-deduction on Rs. 1,31,37,681/-. The assessee submitted details in response; however, the Assessing Officer invoked section 40(a)(ia) and disallowed 30% thereof amounting to Rs. 39,41,304/-.
7. Accordingly, the Assessing Officer computed total income at Rs. 9,08,55,020/- and, after allowing exemption under section 10(46) to the extent of Rs. 7,42,16,935/- (after reduction of Rs. 16,70,763/-), assessed total income at Rs. 1,66,38,085/-.
8. Aggrieved by the assessment order, the assessee preferred appeal before the CIT(A). The assessee reiterated that it is a quasi-judicial regulatory authority, not engaged in any commercial activity, and is eligible for exemption under section 10(46) in respect of all its income. It was further submitted that prior period income had been adjusted against prior period expenses a