Back


2026 Supreme(Online)(ITAT) 12047
INCOME TAX APPELLATE TRIBUNAL (CHENNAI BENCH)
THIRUVASAGAM SATHIYAMOORTHY MADURAI – Appellant
Versus
ACIT NON CORPORATE CIRCLE MADURAI MADURAI – Respondent
ITA 2954/CHNY/2025[2011-12]
The onus under Section 68 is on the assessee, but the AO must verify evidence provided. Estimation of business profit does not subsume all additions; loans and investments require independent proof. A plausible CIT(A) finding supported by evidence is not interfered with.
Headnote:
(A) Income Tax Act, 1961 - Sections 68, 69, 144, 147, 44AD - Unexplained Cash Credits - Unsecured Loans - Cash Deposits - Sundry Creditors - Unexplained Investments - The onus is on the assessee to prove the nature and source of credits under Section 68. Once primary evidence is placed, the Assessing Officer (AO) must act as both investigator and adjudicator; failure to conduct independent verification vitiates the addition. However, estimation of profit from business at a percentage of turnover does not subsume all additions; additions concerning loans or investments must still be independently proved. Where income is estimated, telescoping of investments against such estimated income is permissible to avoid duplication. The burden of proof for the source of an investment can be discharged by producing bank statements, party confirmations, and ledgers. (Para 8-12, 19-23)
(B) Income Tax Act, 1961 - Section 68 - Cash Deposits - The assessee must produce contemporaneous cash flow statements, day-wise cash books, or reconciliatory statements to establish a nexus between withdrawals and redeposits; mere bank statements with a time gap between withdrawals and deposits are insufficient to discharge the onus. (Para 14-16)
(C) Income Tax Act, 1961 - Section 144 - Best Judgment Assessment - Where books of account are not furnished, the AO can estimate income under Section 144 without rejecting books under Section 145. (Para 12)
Facts of the case:
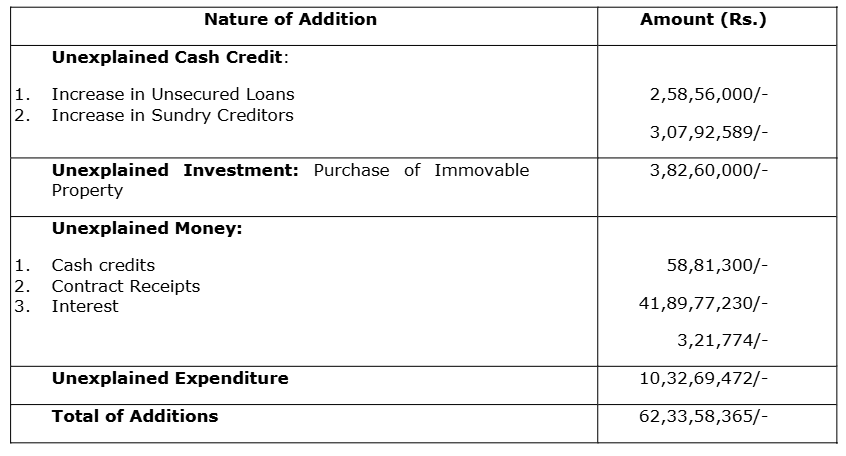
The assessee, an individual, did not file a return of income for AY 2011-12. The AO reopened the assessment under Section 147 based on information that the assessee had undertaken high-value property transactions and received contract payments. The assessee filed a return declaring income of Rs.96,47,790/-. The AO passed a best judgment assessment under Section 144, making several additions. On appeal, the CIT(A) partially granted relief. Both the assessee and the Revenue appealed to the Tribunal. Key issues included additions for unsecured loans (Rs.2,58,56,000/-), cash deposits (Rs.58,81,300/-), sundry creditors (Rs.3,07,92,589/-), and unexplained investment in property (Rs.4,23,12,933/-).
Findings of Court:
Regarding unsecured loans (Rs.2,45,56,000/- from one party), the Tribunal set aside the addition back to the AO for verification of the nature of the amount (whether business advance or loan), as the assessee proved the source but not the nature. The balance of Rs.13,00,000/- from three other parties was confirmed due to lack of evidence. For cash deposits (Rs.58,81,300/-), the issue was set aside to the AO for verification of the claim that deposits were from earlier withdrawals, allowing the assessee one more opportunity to prove its claim. Regarding sundry creditors (Rs.3,07,92,589/-), the Tribunal upheld the CIT(A)'s deletion, noting that the assessee provided names, PAN, and addresses of creditors, and the AO's remand report acknowledged the details without negative observations. For unexplained investment in property (Rs.4,23,12,933/-), the Tribunal upheld the CIT(A)'s deletion, finding that the source of Rs.2.82 crores was proved via direct payment by a third party to the vendor, and the balance of Rs.1.40 crores was telecopied against the estimated business income.
Issues: (i) Whether the assessee discharged the burden of proof under Section 68 concerning unsecured loans and cash deposits. (ii) Whether the AO/ CIT(A) erred in confirming/deleting additions for sundry creditors and unexplained investments. (iii) Whether estimation of business profit subsumes all other additions.
Ratio Decidendi: The Tribunal held that the initial onus is on the assessee, but once evidence is placed, the AO must conduct proper verification. The fact that business income is estimated does not automatically subsume other items like loans or investments which require independent proof. A plausible view taken by the CIT(A), supported by evidence, should not be disturbed.
Result: The assessee's appeal was partly allowed for statistical purposes (setting aside two issues for verification). The Revenue's appeal was dismissed.
| Table of Content |
|---|
| 1. appeals against additions for unsecured loans and cash deposits. (Para 1 , 2 , 3 , 4 , 5 , 6) |
| 2. assessee must prove nature and source of unsecured loans. (Para 7 , 8 , 9 , 10 , 11 , 12) |
| 3. assessee must prove source of cash deposits to avoid addition under section 68. (Para 13 , 14 , 15 , 16) |
| 4. addition for sundry creditors deleted when details furnished. (Para 17 , 18 , 19 , 20 , 21) |
| 5. source of investment in property can be explained by loans and telescoping. (Para 22 , 23 , 24) |
आदेश/ORDER
PER ABY T. VARKEY, JM:
These are cross-appeals preferred by the assessee as well as the Revenue against the order of the Learned Commissioner of Income Tax (Appeals)/NFAC, (hereinafter referred to as ‘Ld.CIT(A)‘), Delhi, dated30.09.2025 for the Assessment Year (hereinafter referred to as ‘AY‘)2011-12.
2. The assessee has raised the following grounds of appeal in ITA No.2954/Chny/2025:
1. The Learned Commissioner of Income-tax (Appeals), NFAC has erred in confirming the addition of Rs.2,58,56000/- made by the Assessing Officer on account of unsecured Loan even after submission of confirmation from the creditor viz. Ledger account copy of relevant portion of bank account in the books of Accounts of the creditor where the payments to the appellant are clearly mentioned along with the relevant portion of Bank Pass Sheet of appellant where the funds got credit for verification.
2. The Learned Commissioner of Income-tax (Appeals), NFAC has erred in confirming the cash payment made into the Bank Account to the tune of Rs.58,81,300/- which has been made by the appellant from out of withdrawal from his other Bank accounts u/s.68 of the I.T. Act in order to meet the cheque payments even after perusal of the reconciliation statement submitted showing a clear and proximate nexus between the withdrawals and subsequent deposits, most of which occurred on the same day by stating in his order under point No.12.4 as " in fact, there is time gap between withdrawal and redeposits, which undermines the claim of direct nexus".
For these Grounds and such other grounds that might be adduced at the time of appeal hearing, Your appellant prays for deletion of additions of Rs.2,58,56,000/- and Rs.58,81,300/- and thus justice be rendered.
3. The Revenue raised the following grounds of appeal in ITA No.3325/Chny/2025:
(1) The order of the Ld. CIT(A) is opposed to law on the facts and in the circumstances of the case.
(2) The Ld. CIT(A) failed to appreciate the fact that the addition u/s 69 was made since the assessee failed to substantiate the source for Rs.4,23,12,933/- with evidences.
(3) The Ld. CIT(A) failed to appreciate the fact that the addition u/s 68 was made since the assessee failed to substantiate the source for Rs.3,07,92,589/- with evidences.
(4) The Ld. CIT(A) failed to consider the decisions of Hon'ble Supreme Court in the cases of Roshan Di Hatti V. CIT (1977) 107 ITR 938(SC) and Kale Khan Mohammed Hanif V.CIT(1963) 50 ITR 1(SC) in which it was held that the onus of proving the source of sum of money found to have been received by an assessee is on him.
(5) The Ld. CIT(A) erred by deleting the additions of Rs.4,23,12,933/- and Rs.3,07,92,589/-despite upholding the findings of non-co-operation and failure to produce complete books of account or supporting vouchers.
(6) For these and such other grounds that may be adduced at the time of hearing and it is prayed that the order of the Ld. CIT(A) may be reversed and that of the Assessing Officer be restored.
4. Brief facts of the case are that the assessee is an individual, who didn’t file return of income (RoI/ITR) for the FY 2010-11 relevant to the subject AY 2011-12. The Assessing Officer (AO) received information that assessee had carried out various transactions during the FY 2010-11, viz purchased immovable property of value exceeding Rs.30,00,000/- (Rs.2.80 crores), sold immovable property of value exceeding Rs.5,00,000/- (Rs.1.61 crores), received contract payment of Rs.20,94,88,615/- for which