Back


2026 Supreme(Online)(ITAT) 12851
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
ACIT MUMBAI – Appellant
Versus
NAWAZUDDIN NAWABUDDIN SIDDIQUI MUMBAI – Respondent
ITA 8640/MUM/2025[2019-20]
Penalty for under-reporting of income is not automatic upon filing a return under section 148; the Assessing Officer must specify the precise limb of under-reporting or misreporting and cannot levy penalty when the returned income is accepted without variation.
Headnote:
(A) Income Tax Act, 1961 - Sections 270A, 274, 139(1), 148, 147, 144B, 250 and 271(1)(c) - Penalty for under-reporting of income - The Assessing Officer initiated penalty proceedings under section 270A of the Act for under-reporting income in consequence of misreporting thereof, without making any addition or disallowance to the income returned in response to a section 148 notice - The Ld. CIT(A) deleted the penalty, holding that the notice u/s 274 r.w.s 270A was omnibus and lacked a specific charge, that the AO's acceptance of the returned income without variation negated any under-reporting or misreporting, and that the levy of penalty under the section is directory ('may') and not mandatory ('shall'), requiring a judicious exercise of power. (Paras 9, 14).
(B) Income Tax Act, 1961 - Section 270A(9) - Misreporting of income - For levy of penalty at 200% under section 270A(8) for misreporting, the Assessing Officer must specify which clause of sub-section (9) (misrepresentation, suppression of facts, etc.) is attracted and record a categorical satisfaction of the same. (Para 12).
Facts of the case:
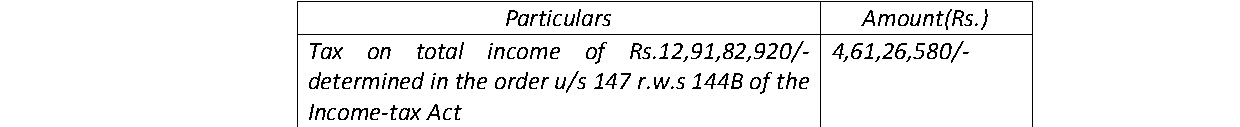
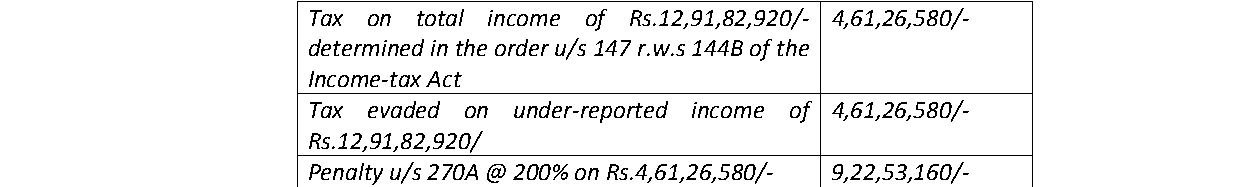
The assessee, an individual, did not file a return of income under section 139(1) for the Assessment Year 2019-20. The case was reopened under section 148 based on information regarding a high-value property purchase and large transactions. In response to the notice, the assessee filed a return declaring a total income of Rs.12,91,82,920/-. The Assessing Officer completed the assessment under section 147 r.w.s 144B, accepting the returned income without any addition or variation. Subsequently, the AO initiated and levied a penalty under section 270A at 200% for under-reporting income in consequence of misreporting, amounting to Rs.9,22,53,160/-. The assessee appealed the penalty order.
Findings of Court:
The Tribunal held that there was no infirmity in the Ld. CIT(A)'s order deleting the penalty. The Tribunal found that the penalty notice and order failed to specify under which limb of section 270A (under-reporting or misreporting) the case fell, nor did it specify the specific clause of section 270A(9) for misreporting. The AO also did not make any addition to the returned income, which was accepted, negating the basis for a penalty for under-reporting or misreporting. The Tribunal emphasized that the power to levy penalty under section 270A is directory and must be exercised judiciously, not arbitrarily. (Paras 8-14).
Issues: The main issues were whether penalty under section 270A can be levied when the assessee files a return for the first time in response to a section 148 notice, but the AO accepts the returned income without any addition, and whether the penalty notice must specify the specific limb of under-reporting or misreporting.
Ratio Decidendi: The court ruled that a penalty under section 270A is not automatically attracted merely because a return is filed for the first time under section 148. The AO must make a finding of under-reporting or misreporting based on the facts. Further, the show cause notice and order under section 270A must specify the precise limb of the provision under which the assessee is being penalized to allow for a proper defense. Failure to do so renders the penalty invalid. (Paras 12, 14).
Result : The appeal filed by the Revenue is dismissed.
| Table of Content |
|---|
| 1. appeal filed by revenue against cit(a) order. (Para 1) |
| 2. revenue's grounds of appeal raised. (Para 2) |
| 3. assessee failed to file return; reassessment opened. (Para 3) |
| 4. cit(a) deleted penalty; revenue appeals. (Para 4 , 5) |
| 5. arguments for and against penalty under section 270a. (Para 6 , 7) |
| 6. penalty invalid without specifying limb of under-reporting/misreporting. (Para 8 , 9 , 10 , 11 , 12 , 13 , 14) |
ORDER
Per Kavitha Rajagopal, J M:
This appeal is filed by the Revenue challenging the order of the Learned Commissioner of Income Tax (Appeals), National Faceless Appeal Centre (“NFAC” for short) [“Ld. CIT(A)” for short] u/s 250 of the Income Tax Act, 1961 (“the Act” for short) relevant to assessment year (“AY” for short) 2019-20.
2. The Revenue has raised the following grounds of appeal:
“1. Whether on the facts and circumstances of the case, the Ld. CIT(A) is justified in allowing an appeal against penalty levied under section 270A for under-reporting of income as being without jurisdiction and not being on factual basis even when the assessee has not filed a return of income under section 139(1) and penalty is leviable as per Act in such instances?
2. Whether on the facts and circumstances of the case, the Ld. CIT(A) is justified in allowing the appeal of the assessee holding that no penalty under section 270A is leviable when there is no addition on account of difference between the income assessed and income as per ROI, when such instances are deemed to be under- reporting and calculation of penalty for such under-reporting are clearly specified in the section 270A(2)(b) and Section 270A(3)(b) of the Act?"
3. Whether on the facts and circumstances of the case, the Ld. CIT(A) has erred in allowing the appeal of the assessee as the assessee has not filed his return of income under section 139(1) but in response to notice u/s.148 of the Act, ignoring the fact that the failure to file a return is under reporting under the provisions of section 270A(2) of the Act?
4."Whether on the facts and circumstances of the case, the Ld. CIT(A) has erred in allowing the appeal of the assessee as the assessee has not filed his return of income under section 139(1) but in response to notice u/s. 148 of the Act, ignoring the fact that the assessee was covered by the provision of section 270A(2)(b) of the Act?
5. The Ld. CIT (A)'s order is contrary in law and on facts and deserves to be set aside.
6. The appellant prays that the order of Ld. CIT (A) on the above ground be set aside and that of the AO restored. The applicant craves leave to amend or alter any ground or add a new ground that may be necessary at the time of hearing.
The Appellate Order of NFAC, Delhi vide DIN & Order No. ITBA/NFAC/S/250/2025- 26/1081746293(1) dated 14.10.2025 in the case of Nawazuddin Nawabuddin Siddiqui [PAN: AVVPS3509GJ, Α.Υ.: 2019-20 has been received in the O/o. Pr. CIT-8, Mumbai through ITHA on 14.10.2025. The Last date for filing appeal is 31.12.2025. However, appeal should be filed immediately.”
3. Brief facts of the case are that the assessee is an individual and had not filed his return of income for the year under consideration. The assessee's case was reopened based on the information on insight portal as Risk Management strategy formulated by CBDT as RMS-non filing of return-PAN cases, as the assessee had purchased an immovable property for a value of Rs.11,50,00,000/- during the year under consideration and large transactions of Rs.26,73,98,898/- were also found to have been done by the assessee. The Ld. Assessing Officer (“Ld. AO” for short) issued notice u/s 148 of the Act dated 30.03.2023 and in response to which the assessee filed his return of income declaring total income at Rs.12,91,82,920/- dated 09.11.2023. The Ld. AO passed the assessment order dated 05.03.2024 u/s 147 r.w.s 144B of the Act determining the total income at Rs.12,91,82,920/- after duly accepting the return of income filed by the assessee u/s 148 of the Act without any var