


 Back


2026 Supreme(Online)(ITAT) 13768
INCOME TAX APPELLATE TRIBUNAL (DELHI BENCH)
Vikas Awasthy, Judicial Member
DENSO INTERNATIONAL ASIA CO. LTD. THAILAND – Appellant
Versus
THE ASSISTANT COMMISSIONER OF INCOME TAX INTERNATIONAL TAXATION NEW DELHI – Respondent
ITA 3421/DEL/2023[2021-22]
For the Appellants/Petitioners: Vishal Kalra
For the Respondents: M.S. Nethrapal
Fee for Technical Services, in the absence of a specific clause in a DTAA, is taxable as business income under Article 7, not under the residuary Article 22, if rendered in the normal course of business and no PE exists.
Headnote:(A) Income Tax Act, 1961 - Sections 9(1)(vii), 143(3), 144C(13), 234A, 234B, 270A - India-Thailand DTAA - Articles 7, 12, 22 - Fee for Technical Services (FTS) not specifically covered in India-Thailand DTAA - Taxability under residual Article 22 - Whether FTS can be taxed under residuary clause when no specific article exists - Held: When DTAA does not make reference to FTS as separate item, residuary Article 22 cannot be invoked; FTS forms part of business income under Article 7 if services are in normal course of business and assessee has no PE in India. (Paras 7-9)
Facts of the case:
The assessee, a Thai tax resident and regional service center of Denso Group, provided technical, design, and testing services to its Indian group companies without a Permanent Establishment in India. The AO held that since India-Thailand DTAA lacks an FTS clause, the receipts fall under Article 22 (Other Income) and are taxable at 10% under Section 9(1)(vii). The DRP upheld the addition.
Findings of Court:
Following its consistent view in the assessee's own case for AY 2020-21 and AY 2022-23, the Tribunal held that FTS cannot be taxed under residuary Article 22; it constitutes business income under Article 7, and since the assessee has no PE in India, the income is not taxable. The addition was deleted.
Issues: Whether Fee for Technical Services receipts, in the absence of a specific FTS clause in the India-Thailand DTAA, can be taxed under the residuary Article 22 or should be treated as business income under Article 7.
Ratio Decidendi: When a DTAA does not contain a specific provision for FTS, such income, if derived in the normal course of business, falls under business income (Article 7) and not under the residuary clause. Article 22 applies only to items of income not covered by any other article. The AO cannot invoke the residuary clause without first examining whether the income falls under other express provisions.
Result: Appeal partly allowed.
| Table of Content |
|---|
| 1. the appeal is against the assessment order for ay 2021-22, and ground no. 2 is not pressed. (Para 1 , 2) |
| 2. assessee contends fts receipts are not taxable under india-thailand dtaa due to absence of fts clause and no pe. (Para 3) |
| 3. department argues that absence of fts clause does not make it business income; assessee relies on overruled case law. (Para 4 , 5) |
| 4. tribunal follows consistent view that fts is business income under article 7, not residuary article 22. (Para 6 , 7 , 8 , 9) |
| 5. interest under section 234a restored for verification; penalty proceedings premature; appeal partly allowed. (Para 10 , 11 , 12) |
PER VIKAS AWASTHY, JUDICIAL MEMBER
This appeal by the assessee is directed against the Assessment Order passed u/s. 143(3) r.w.s 144C(13) of the Income Tax Act,1961 (hereinafter referred to as ‘the Act’) dated 19.09.2023, for Assessment Year 2021-22.
2. Shri Vishal Kalra, appearing on behalf of the assessee at the outset submitted that he is not pressing ground no. 2 and sub grounds 2.1 to 2.4 of appeal challenging validity of the assessment order.
In light of the statement made by ld. Counsel for the assessee at Bar, ground no. 2 including the sub grounds i.e. 2.1 to 2.4 of appeal are dismissed as not pressed.
3. The ld. Counsel for the assessee submits that in ground no. 3 to 7 of appeal, the assessee has assailed the assessment order in taxing amount received as Fee for Technical Services (FTS) Rs.17,28,18,072/- under Article 22 of the India-Thailand DTAA and accordingly taxed FTS @10% as per the provisions of section 9(1)(vii) of the Income Tax Act, 1961 (hereinafter referred to as ‘the Act’).
3.1. The ld. Counsel narrating facts of the case submits that the assessee company is incorporated under the laws of Thailand and is a tax resident of Thailand. The assessee is a regional service center of the Denso Group for Asia and Oceanic undertaking business administration, material engineering services, design and development services, testing and technical services of automotive components for the group. The assessee does not have any Permanent Establishment (PE) in India. During the period relevant to assessment year under appeal, the assessee earned following incomes in the nature of FTS, on account of services provided to its Indian Group Companies:
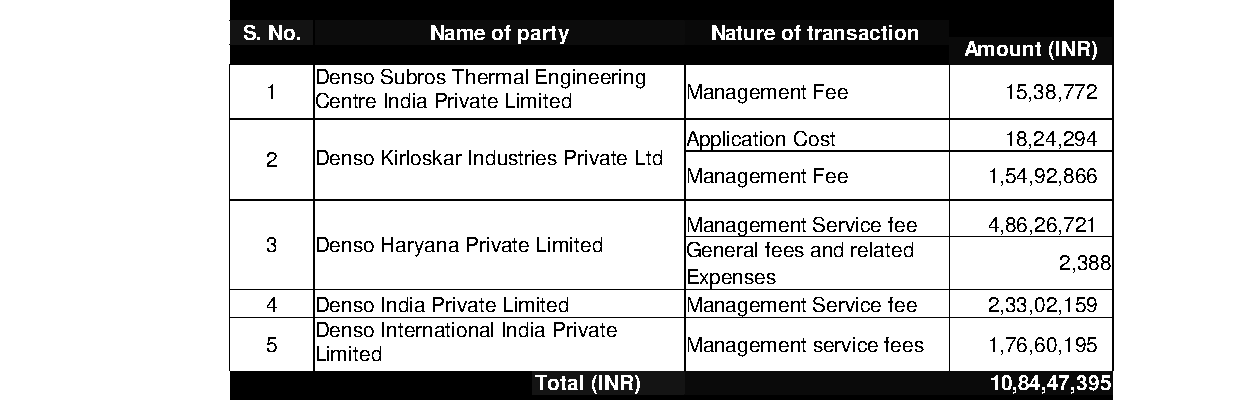
The assessee has claimed said receipts as non-taxable in the absence of FTS clause in India-Thailand Double Tax Avoidance Agreement (DTAA). The Assessing Officer (AO) held that in the absence of FTS clause in the DTAA, the income from FTS fall under Article 22 i.e. residuary clause of the DTAA i.e. ‘Other Income’ and accordingly taxed FTS @10% as per section 9(1)(vii) of the Act.
3.2. The ld. Counsel contended that the said receipts cannot be considered under Article 22 of DTAA merely for the reason that there is no clause to tax FTS in India- Thailand DTAA. The ld. Counsel submits that identical issue was considered by the Tribunal in assessee’s own case in preceding assessment years i.e. in ITA No. 1985/Del/2023 for AY 2020-21 decided on 27.06.2024 and in immediate subsequent assessment year in ITA No.402/Del/2025 for AY 2022-23 decided on 08.10.2025. The ld. Counsel submitted that, the AO in the impugned assessment order admits that the issue is repetitive.
3.3. The ld. Counsel submits that since the assessee has not have any Permanent Establishment (PE) in India. Even, if the amount received by the assessee from Indian Group Companies is treated as business income it is not liable to be taxed in India.
3.4. The ld. Counsel submits that a perusal of the draft assessment order would show that the AO as per the information available on Insight portal held that the assessee has received total amount of Rs.17,28,68,072/-. The AO without providing opportunity of hearing to the assessee proposed to make addition of the aforesaid amount. The AO while concluding the draft assessment order made addition of Rs.17,28,68,072/- as FTS under section 9(1)(vii) of the Act. T







