Back


2025 Supreme(Online)(KAR) 289
IN THE HIGH COURT OF KARNATAKA AT BENGALURU
C.M. POONACHA, J
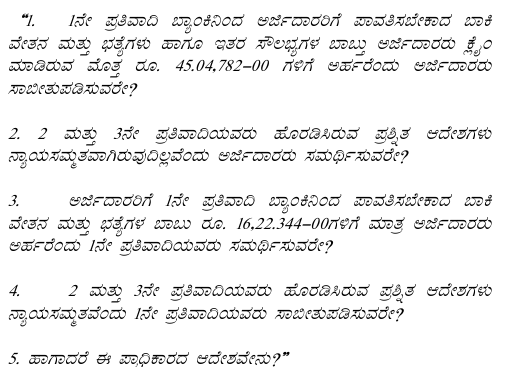
Revanasiddaiah S/o Late Siddalingaiah – Appellant
Versus
Janatha Seva Co-operative Bank Ltd. – Respondent
WRIT PETITION NO.41000 OF 2017 (CS-RES)
Advocate Appeared:
For the Appellant :SRI A V GANGADHARAPPA, ADVOCATE
For the Respondent:SRI SIDDHARTH BABURAO, AGA FOR R2 TO R4 SRI PRADEEP S SAWKAR, ADVOCATE
Reinstatement does not automatically entitle an employee to benefits; actual service is required to claim allowances and bonuses.
Headnote:(A) Karnataka Co-operative Societies Act, 1959 - Sections 70, 101, 106, and 108 - Writ petition seeking to quash orders rejecting claims for arrears of salary and other benefits following reinstatement - Court affirmed the need for proper consideration of claims for consequential benefits post-reinstatement, emphasizing that entitlements must be based on actual service and not merely on reinstatement. (Paras 2, 4, 6, 8, 9, 54)
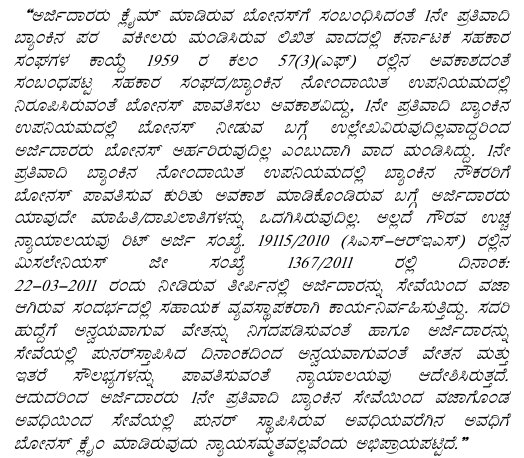
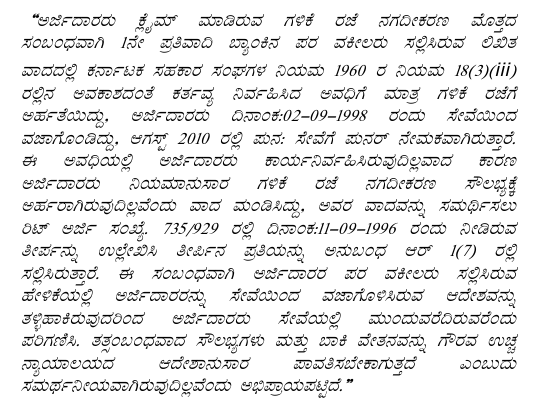
(B) Employment Law - Reinstatement and Consequential Benefits - The court ruled that reinstatement does not automatically entitle an employee to all benefits unless they can demonstrate that such benefits are earned through actual service. Claims for allowances contingent on active service were denied. (Paras 17, 49, 50)
Facts of the case:
The petitioner, an Assistant Manager, was terminated and subsequently reinstated after a tribunal ruling. He claimed various benefits, including arrears of salary and bonuses, which were contested by the bank.
Findings of Court:
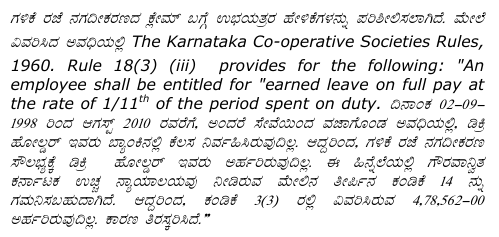
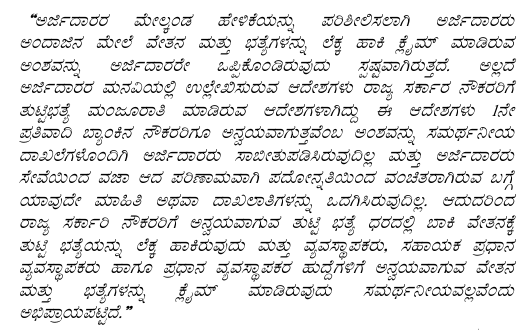
The court found that the petitioner failed to demonstrate entitlement to the claimed benefits, as they were contingent on actual service.
Issues: The court addressed whether the authorities were justified in rejecting the petitioner’s claims for benefits post-reinstatement.
Ratio Decidendi: The court emphasized that reinstatement does not equate to automatic entitlement to benefits; actual service is required to claim benefits like bonuses and leave encashment.
Result: Writ petition partly allowed, directing the bank to spread the arrears over the relevant period for tax relief purposes.
| Table of Content |
|---|
| 1. petitioner terminated and reinstated (Para 2 , 3 , 4 , 5) |
| 2. petitioner's claims for benefits (Para 6 , 7) |
| 3. court's consideration of claims (Para 8) |
| 4. reinstatement does not imply entitlement (Para 9 , 10 , 11 , 12 , 13 , 14 , 15 , 16 , 17 , 18 , 19 , 20 , 21 , 22 , 23 , 24 , 25 , 26 , 27 , 28 , 29 , 30 , 31 , 32 , 33 , 34 , 35 , 36 , 37 , 38 , 39 , 40 , 41 , 42 , 43 , 44 , 45 , 46 , 47 , 48 , 49 , 50 , 51 , 52 , 53) |
| 5. writ petition partly allowed (Para 54 , 55) |
CAV ORDER
The present writ petition is filed seeking the following reliefs:
“(a) a writ in the nature of Certiorari or any other appropriate writ or order quashing the order dated 30.11.2015 passed by the 2nd respondent in Case No.ARB-C:45:CEP:578:2014-15 produced as Annexure-K, the order dated 3.10.2016 passed by the 3rd respondent in Case No.DRB-C/Appeal 03/2015-16 produced as Annexure-L and the order dated 29.7.2017 passed by the 4th respondent in case No.CO:30:CAP:2016 certified copy of which is produced as Annexure-M respectively.
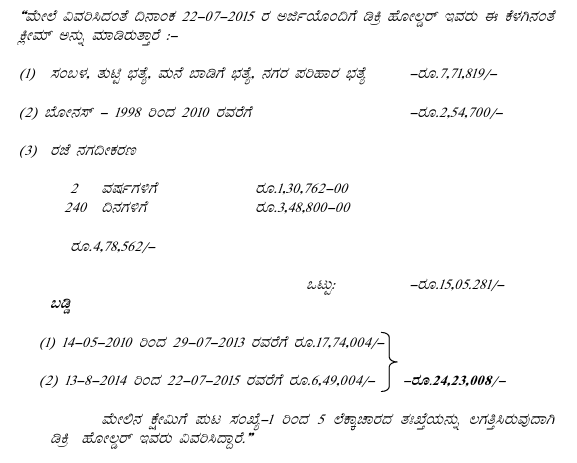
b) a writ in the nature of mandamus or any other appropriate writ or order and direct the 2nd respondent to recover from the 1st respondent entire amount of `.44,74,690/- with interest at 12% pa., from the date of petition as per the representation made by the petitioner dated 22.7.2017 true copy of which is produced as Annexure-K and as claimed in the execution petition dated 9.6.2014, true copy of which is produced as Annexure-J.”
2. The relevant facts necessary for consideration of the present petition are that, the petitioner was working as an Assistant Manager in the first respondent – bank when he was terminated on 2.9.1998. Being aggrieved, the petitioner challenged the said termination in a dispute filed under Section 70 of the Karnataka Co-operative Societies Act, 1959 , [Hereinafter referred to as the ‘Act’] which was dismissed on 19.11.2003. Being aggrieved, the petitioner filed Appeal No.20/2004 before the Karnataka Appellate Tribunal, [Hereinafter referred to as the ‘Tribunal’]. By judgment dated 14.5.2010, the Tribunal allowed the appeal of the petitioner, set aside the order dated 19.11.2003 as well as the termination dated 2.9.1998 and the first respondent was directed to reinstate the petitioner into services of the bank with all consequential benefits and backwages. The order dated 14.5.2010 of the Tribunal was affirmed by this Court in WP No.19115/2010.
3. It is further forthcoming that during the pendency of WP No.19115/2010, consequent to the order dated 22.3.2011 passed on an interim application in the said writ petition, this Court directed the bank to notionally fix the salary of the petitioner admissible as an Assistant Manager from the date of reinstatement and pay all other benefits.
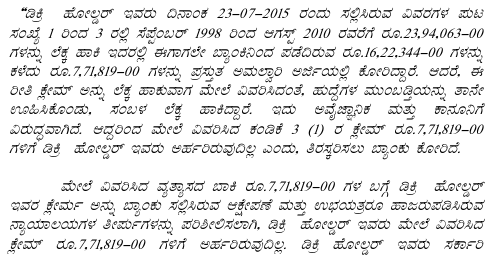
4. Pursuant to the said order dated 22.3.2011, the petitioner was reinstated and joined services on 16.8.2010. WP No.19115/2010 was disposed of by order dated 15.9.2011. The petitioner, thereafter made various representations claiming arrears of salary, dearness allowance, encashment of leave, bonus and other benefits as also promotion and since the same was not acceded to, permission was sought by the petitioner to prosecute the office bearers of the bank. Since the said permission was not accorded, the petitioner preferred WP No.29312/2013 during the pendency of which, on 29.7.2013 the first respondent bank filed a memo along with a calculation placing on record that the petitioner was entitled to a total sum of `16,22,344/- and after various deductions a sum of `12,41,002/- was paid. The manner in which the said calculation was made was also placed on record along with the said memo. Having regard to the said payment, the writ petition was disposed of vide order dated 29.7.2013 and in view of the assertion of the petitioner that the entire amount due and payable had not been correctly quantified and paid, it was observed that such satisfaction was required to be decided in execution proceedings under Section 101