Back


2025 Supreme(Online)(Mad) 59804
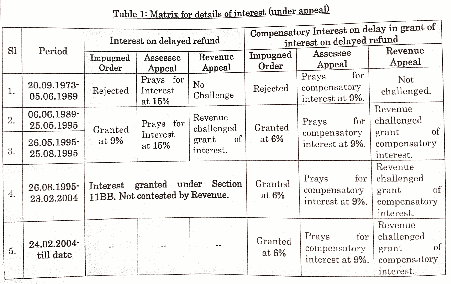
IN THE HIGH COURT OF JUDICATURE AT MADRAS
G.R.SWAMINATHAN, M.JOTHIRAMAN, JJ
Dalmia Cement (Bharat) Ltd. – Appellant
Versus
The Commissioner of Central Excise – Respondent
W.A(MD)Nos.1790 of 2021 & 2061 of 2023 | W.A.(MD)No.593 of 2021
For the Appellants/Petitioners: Mr.Raghavan Ramabadran for Mr.Lakshmi Kumaran & Sridharan
For the Respondents: Mr.AR.L.Sundaresan Assistant Solicitor General assisted by Mr.S.Gurumoorthy for R1 & R2
For Respondent: Mr.Raghavan Ramabadran for Mr.Lakshmi Kumaran & Sridharan
The court held that equitable principles allow for compensatory interest on delayed refunds, reaffirming that interest provisions apply regardless of initial absence in statute.
Headnote:(A) Central Excise Act, 1944 - Sections 11
(B) and 11(BB) - Refund of excise duty paid under protest - Assessee entitled to interest as compensation for delayed refund, with criteria established by precedent cases upheld. (Paras 2, 6, 8)
(B) Interest - Claim for interest divided into categories based on periods of delay in payment; no provision for interest existed initially, leading to subsequent disputes. (Paras 3, 4, 5)
(C) Equitable Determination - Court emphasizes the principles of equity, rejecting claims denied under unjust enrichment retrospectively, while recognizing the right for compensatory interest on delays. (Paras 7, 8)
Facts of the case:
Disputed excise duty pertains to equalised freight charges from 1972-1976, originally refunded following tribunal ruling in 1989; subsequent legal battles arose due to delays in payment of interest.
Findings of Court:
Court upheld the single Judge's ruling on compensation due, distinguishing periods with clear provisions for interest.
Issues: Main issues centered on the applicability of interest before statutory provision enactment and entitlement to compensatory interest for delays.
Ratio Decidendi: The court reinforced that in cases of wrongful withholding of funds, equity allows for compensation, particularly in significant delays without statutory provisions.
Result: Writ appeals dismissed.
| Table of Content |
|---|
| 1. disputed excise duty refund process from original payment to judicial rulings. (Para 1 , 2) |
| 2. arguments regarding interest claims raised by both parties. (Para 3 , 4 , 5) |
| 3. court's reflections on equity and previous judgments. (Para 6 , 7) |
| 4. final ruling on interest and entitlement issues from various claims. (Para 8) |
COMMON JUDGMENT
(Judgement of the Court was delivered by G.R.SWAMINATHAN, J.)
Dalmia Cement (Bharat) Limited is a company manufacturing cements of different grades and varieties. It is an assessee registered under the Central Excise Act, 1944. The case on hand pertains to the period from 01.06.1972 to 15.03.1976. During this period, the assessee had paid excise duty on what was known as equalised freight charges. According to the assessee, this component was not includable while computing excise duty. Hence, excise duty was paid under protest. Subsequently, the assessee filed an application for refund of the same. This request was rejected by the original authority. But the appellate tribunal, New Delhi, CEGAT vide order dated 06.06.1989 held that the equalised freight charges were not includable in the assessable value and upheld the plea for refund and allowed the appeal. Even though the tribunal had upheld the plea of the assessee, refund was not made. In the meanwhile, Section 11(B) of the Central Excise Act, 1944 was amended introducing the concept of unjust enrichment in the matters of refund. Invoking the amended Section 11(B) of the Act, refund was denied. The matter went right upto to the Hon'ble Supreme Court. Following the dismissal of the appeal filed by the revenue on 09.01.2004 by the Hon'ble Supreme Court, refund to the tune of Rs.2,63,69,322/- was sanctioned on 23.02.2004. Since there was delay in paying interest, there was an another round of proceedings and finally, a sum of Rs.2,84,83,203/- was paid on 09.06.2016 as per Section 11 BB of the Excise Act for the period from 26.08.1995 to 23.02.2004.
2.The stand of the assessee was that the interest amount due and payable to them as well as the compensatory interest have not been paid in full and hence, they filed W.P.(MD)No.18012 of 2016. The learned single Judge allowed the writ petition in the following terms:-
“41. The entitlement of the petitioner, though termed ‘interest’, would really fall within the realm of ‘compensation’ as it cannot be denied that the petitioner has been deprived of a substantial amount of capital from 1989 onwards till date and till date of payment. I am thus of the view that the petitioner in this case is clearly entitled to compensation for the loss of capital from the date of success in its appeal before the CEGAT, being 06.06.1989 as well as compensation on the delay on payment of interest as claimed, and I order accordingly.
42. The petitioner is entitled to interest at the rate of 9% from 06.06.1989 till 25.08.1995 on the amount of refund and thereafter at the rates specified in Notifications of the Central Board of Excise and Customs in i) Notification No. 41/2000- (N.T.), ii) Notification No.24/2001- Central Excise (N.T.) Dt. 11/05/2001 (F.No.B-10/1/2001-TRU), iii) Notification No. 17/2002- CE(N.T.) Dt.13/05/2002 (F.No.B-10/3/2002-TRU) and iv) Notification No.67/2003- CE (N.T.) Dt. 12/09/2003 (F.No.04/07/2003 CX.I) and interest at the rate of 6% till date of payment, to be paid over to it within a period of six (6) weeks from date of receipt of a copy of this order.”
Aggrieved by the same, the department filed W.A.(MD)No.2061 of 2023, while the assessee filed W.A.(MD)No.1790 of 2021.
3.The learned counsel for the assessee reiterated all the grounds set out in the memorandum of grounds of writ appeal. The learned Additional Solicitor General also reiterated the stand set out in the grounds of appeal. The counsel on either side filed detailed written statements and also relied on a catena of case laws in support of the respective propositions advanced by them.
4.We carefully considered the rival contenti