
 Back


IN THE HIGH COURT OF JUDICATURE AT MADRAS
Honourable Mr Justice C. SARAVANAN
M/S.K.N.RAJ CONSTRUCTIONS – Appellant
Versus
THE STATE TAX OFFICER – Respondent
COMMON ORDER
These cases were heard twice, once at the time of the admission, and again today. All these writ petitions are being disposed of by this common order.
2. In these writ petitions, the petitioner has challenged the assessment orders in DRC-07 dated 08.11.2024 passed for the respective tax periods by the respondent under Section 74 of the respective GST enactments, as modified by the orders dated 11.11.2024.
3. This is the second round of litigation before this Court. Earlier, the petitioner had suffered adverse assessment orders in respect of the re assessment years on 13.09.2023. Even prior to the aforesaid orders, a sum of Rs.1,42,33,484/- was recovered / paid directly from the petitioner’s bank account on 30.01.2023 towards the tax liability.
4. In this background, by a common order dated 21.08.2024 in W.P.Nos.14865, 14869, 14873, 14875 & 14877 of 2024, wherein these aforesaid assessment orders were challenged, the following order was passed:-
“11. For the reasons stated above, this Court is inclined to set aside the impugned orders dated 13 09 2023 passed by the respondent, with the following directions:-
(i) The orders impugned herein are set aside and the matters are remanded to the respondent in respect of the assessment years 2017-2018, 2018-2019, 2019-2020, 2020-2021 and 2021-2022 for fresh consideration within a period of four weeks from the date of receipt of a copy of this order Since a sum of Rs.1.45 crores was withdrawn from the petitioner's Bank account, this Court is not inclined to impose any further condition.
(ii) The petitioner shall file their reply/objection along with the required documents, if any, within a period of two weeks after the date of receipt of a copy of this order.
(iii) On filing of such reply/objection by the petitioner, the respondent shall consider the same and issue a 14 days clear notice by fixing the date of personal hearing to the petitioner and thereafter, pass appropriate orders on merits and in accordance with law, as expeditiously as possible, after hearing the petitioner and subject to the verification of the payment of the aforesaid amount.
12. With the above directions, these Writ Petitions are disposed of. No costs. Consequently, connected Miscellaneous Petitions are closed.”
5. Pursuant to the aforesaid order, the impugned assessment orders in DRC - 07 has now been passed, wherein the petitioner has been directed to pay a sum of Rs.15,23,52,610/-, together with interest and penalty under Sections 50 and 74 of the TNGST Act. The total amount of tax payable by the petitioner along with interest and penalty comes to Rs.55,86,77,302/-.
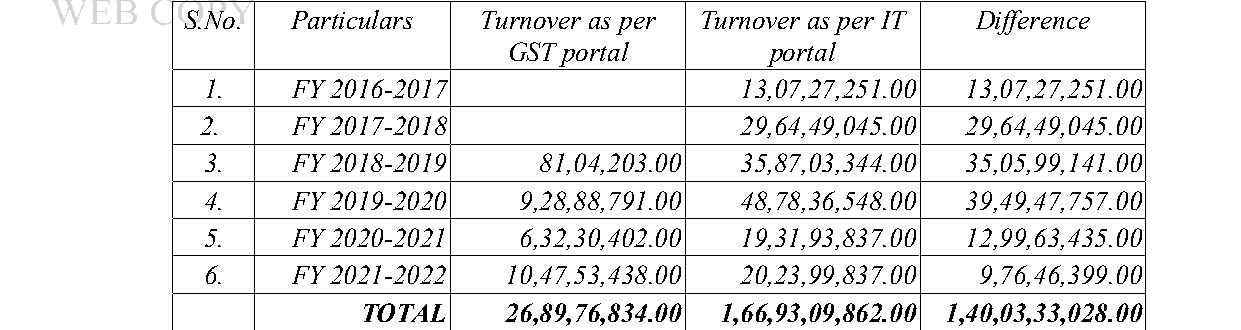
6. The dispute arises on account of the inflated and padded return of income filed by the petitioner for the respective tax periods before the Income Tax Department. The total turnover reported by the petitioner (supply) for the period in disputed is Rs.29,69,00,919.88/-. However, according to the in the Income Tax portal, the petitioner has declared a turnover of Rs.1,66,93,09,862/- for the financial years 2016-17 to 2021-2022.
7. The Department has, on the other hand, concluded that there is a difference between the turnover reported by the petitioner under the respective GST enactments in the annual returns (GSTR-9) and the turnover declared before the Income Tax Department in the IT portal, as detailed below:-
K.N.RAJ CONSTRUCTIONS (As per GST Department Records)
8. The learned counsel for the petitioner submits that the reason for the padded and inflated turnover was to secure contracts in the tenders floated by the Government and various departments of the State Government to qualify in the technical evaluation.
9. It is further submitted that the income declared in the Income Tax Portal cannot be the basis for confirming the demand, particularly when the turnover was inflated solely for the purpose of qualifying the petitioner in the technical bids issued by various Government Departments and local bodies in the State of Tamil Nadu. Therefore,


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


