


 Back


2025 Supreme(Online)(Mad) 75985
IN THE HIGH COURT OF JUDICATURE AT MADRAS
Honourable Mr Justice C. SARAVANAN
M/S.Royal Meridian Impex India Private Limited – Appellant
Versus
THE JOINT COMMISSIONER – Respondent
W.P.No.28705 of 2025|W.P.No.30248 of 2025|W.P.No.36758 of 2025|W.M.P.No.32146 of 2025|W.M.P.No.33933 of 2025|W.M.P.No.41110 of 2025|W.M.P.No.41113 of 2025
For the Appellants/Petitioners: M.Devaraj, G.Purushothaman
For the Respondents: Su.Srinivasan, T.Nalinidhar, T.N.C.Kaushik, T.Ramesh Kutty, S.Venkatesan, M.Santhanaraman, J.Vasu
Failure to pre-deposit mandatory 10% of disputed tax under Section 107 GST Act bars appeal; High Court can permit deposit and remit for merits, with consequential attachments lifted upon deposit.
Headnote:(A) GST - Section 107 of the Central/State Goods and Services Tax Act - Pre-deposit of 10% of disputed tax - Failure to pre-deposit mandatory amount leads to rejection of appeal - Appellate Authority cannot entertain appeal without compliance - Court can grant opportunity to deposit and direct appellate authority to decide on merits - Consequential orders of attachment of bank accounts and property registration are dependent on outcome of appeal.
(B) Writ Jurisdiction - Article 226 - Interim relief - Upon pre-deposit of 10% of disputed tax, attachment of bank accounts shall be lifted - For property under provisional attachment, registering authority directed to complete registration and hand over title deed to jurisdictional assessing officer as security pending disposal of appeal.
Facts of the case:
The petitioner in W.P.No.28705 of 2025, a company, challenged the Order-in-Appeal dated 08.06.2023 which rejected its appeal against an Order-in-Original dated 19.05.2022 (passed during the COVID-19 period) on the ground of non-payment of mandatory 10% pre-deposit of disputed tax under Section 107 of the GST Act. The company expressed willingness to deposit the amount. The related writ petitions sought de-freezing of bank accounts (W.P.No.30248 of 2025) and quashing of provisional attachment with direction to register a sale deed (W.P.No.36758 of 2025). The petitioners in the latter two writs are the former director and the husband of the company's managing director, who claimed that the former director had ceased to be a director and the property was purchased before attachment.
Findings of Court:
The challenge to the Order-in-Appeal must fail because the mandatory pre-deposit under Section 107 was not complied with. The court granted liberty to the petitioner to pre-deposit 10% of the disputed tax in cash from its Electronic Cash Register within eight weeks. Upon such deposit, the appellate authority shall dispose of the appeal on merits without reference to limitation. Consequential reliefs: the bank account attachment shall stand lifted; the registering authorities shall complete the registration of the property and hand over the registered title deed to the jurisdictional assessing officer as security pending the appeal.
Issues: 1. Whether the writ petition challenging the rejection of appeal for non-compliance with mandatory pre-deposit under Section 107 of the GST Act is maintainable? (Held: No, but opportunity to deposit can be granted.) 2. Whether the consequential attachments and registration issues should be resolved pending the appeal? (Held: Yes, subject to pre-deposit.)
Ratio Decidendi: The mandatory pre-deposit under Section 107 of the GST Act is a condition precedent for hearing an appeal; failure cannot be condoned by the appellate authority, but the High Court in its writ jurisdiction may permit the deposit and remit the matter for merits adjudication. Consequential orders (bank attachment and property registration) are tied to the outcome of the appeal and can be modulated accordingly.
Result: Writ Petitions disposed of with directions as above. No costs. Connected miscellaneous petitions closed.
COMMON ORDER
By this Common Order, all these Writ Petitions are being disposed of.
2. In W.P.No.28705 of 2025, the Petitioner has challenged the impugned Order in Order-in-Appeal No.227 of 2023 dated 08.06.2023.
3. By the impugned Order dated 08.06.2023 in Order-in-Appeal No.227 of 2023, the 2nd Respondent / Appellate Authority has rejected the Petitioners Appeal against the Order-in-Original No.11 of 2022-GST (JC) dated 19.05.2022 passed by the 1st Respondent on the ground that the Petitioner had failed to pre-deposit the mandatory 10% of disputed tax.
4. Mr.M.Devaraj, learned counsel for the Petitioner(s) in W.P.Nos.28705 and 36758 of 2025 submits that the Petitioners are willing to deposit the aforesaid 10% of disputed tax as the aforesaid Order-in-Original No.11 of 2022-GST (JC) dated 19.05.2022 was passed during the period when the Country was still under the spell of Covid-19 and that the Petitioner could not muster the required amount of pre-deposit. The other two Writ Petitions in W.P.Nos.30248 and 36758 of 2025 have been filed for the following reliefs:-
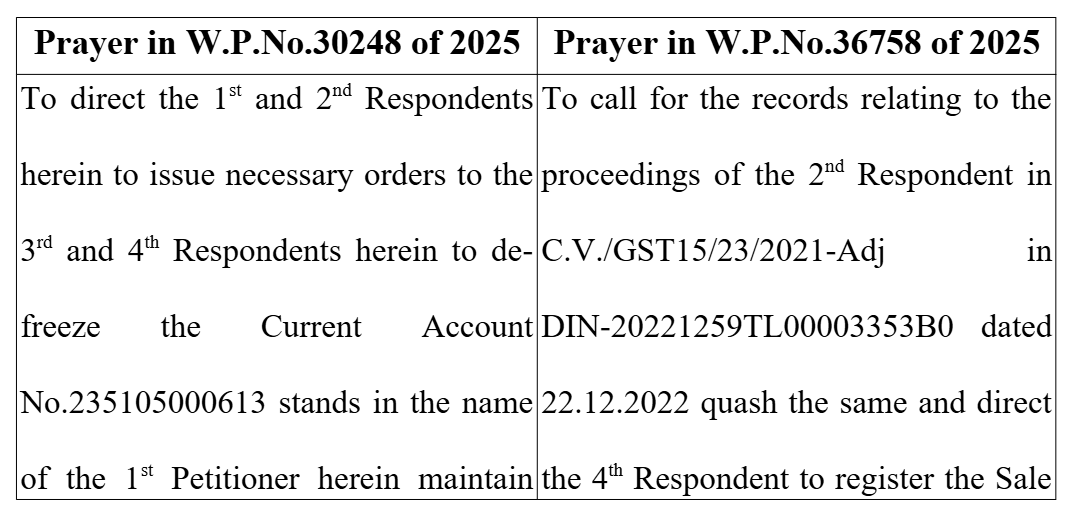
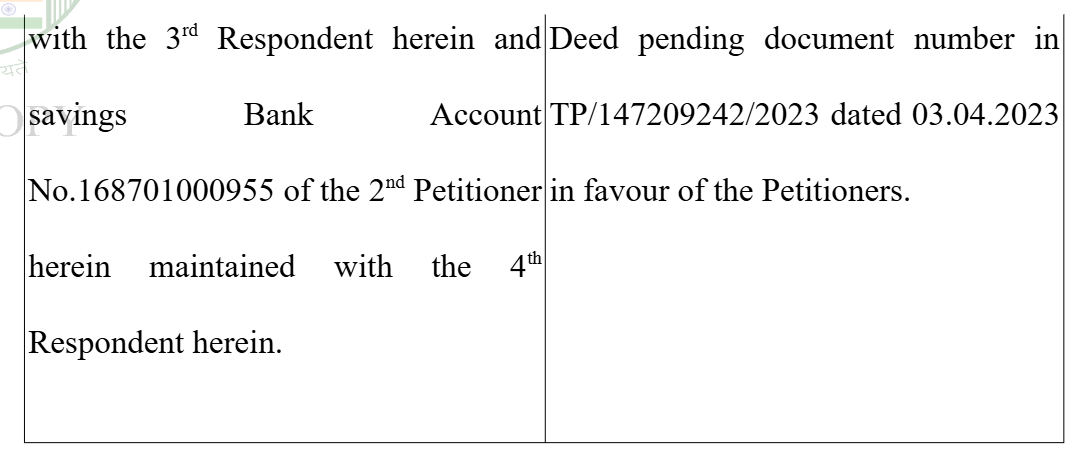
5. These are consequential orders passed in view of the aforesaid Order-in-Original No.11 of 2022-GST (JC) dated 19.05.2022 and the rejection of Appeal vide Order in Order-in-Appeal No.227 of 2023 dated 08.06.2023 impugned in W.P.No.28705 of 2025.
6. W.P.Nos.30248 and 36758 of 2025 have been filed by the former Director the Company / the Petitioner in W.P.No.28705 of 2025 (presently Chairman and Managing Director of the Company), who is none other than the Petitioner’s husband namely Mr.M.Arul Kumaran.
7. The case of the Petitioner is that the Petitioner ceased to be the Director of the Company / the Petitioner in W.P.No.28705 of 2025 as early as 29.05.2022 and that she has been unnecessarily proceeded for the dues of the Company.
8. That apart, it is submitted that the property was purchased which is pending for Registration in view of the attachment proceedings by the Department.
9. Mr.M.Santhanaraman, learned Senior Standing Counsel for the Respondents 1 to 3 in W.P.No.36758 of 2025 submits that these Writ Petitions are devoid of merits and therefore liable to be dismissed.
10. I have considered the submissions made by the learned counsels for the Petitioner(s) and the learned Senior Standing Counsel for the Respondents.
11. The challenge to the Order-in-Appeal No.227 of 2023 dated 08.06.2023 passed by the 2nd Respondent / Appellate Authority against Order-in-Original dated 19.05.2022 passed by the 1st Respondent impugned in W.P.No.28705 of 2025 has to fail on account of failure to mandatory pre-deposit 10% of the disputed tax as is required under Section 107 of the respective GST enactments.
12. The liberty that can be granted to the Petitioner in W.P.No.28705 of 2025 at this stage is to direct pre-deposit 10% of the disputed tax in cash from the Petitioner’s Electronic Cash Register within a period of 8 weeks from the date of receipt of a copy of this order, in which case, the 2nd Respondent / Appellate Authority shall dispose of the Petitioner’s appeal against Order-in-Original No.11/2022-GST (JC) dated 19.05.2022 passed by the 1st Respondent, on merits on its own turn after hearing the Petitioner(s) without reference to limitation.
13. As and when the aforesaid amount is pre-deposited, the attachment of the Bank Account of the Petitioner(s) with the 3rd Respondent Bank which is the subject matter in W.P.No.30248 of 2025 shall stand lifted.
14. As far as the provisional attachments are concerned, there shall be a direction to the Registering Authorities namely the Respondents 4 and 5 to complete the Registration of the property and hand over the registered Title Deed to the jurisdictional Assessing Officer under the respective GST enactments with whom the Petitioner(s) in W.P.No.30248 of 2025 is / are assessed as a security to secure the interest of the Respondents GST Department pursuant to Order-in-Original No.11/2022-GST (JC) dated 19.05.2022, pending disposal of the appea







