
 Back


IN THE HIGH COURT OF JUDICATURE AT MADRAS
Honourable Mr Justice C. SARAVANAN
SUDHA SECURITY PROTECTION FORCE PRIVATE LIMITED – Appellant
Versus
THE ASSISTANT COMMISSIONER (ST) – Respondent
W.P.No.46856 of 2025 | W.P.No.46871 of 2025 | W.P.No.46862 of 2025 | W.P.No.46865 of 2025 | W.P.No.46882 of 2025 | W.P.No.46894 of 2025 | W.P.No.46888 of 2025 | W.P.No.46938 of 2025
COMMON ORDER
By this common order, all the eight Writ Petitions are disposed of. In the following Writ petitions, the Petitioner has challenged the computation of interest under Section 50 of the respective GST Enactment Act .
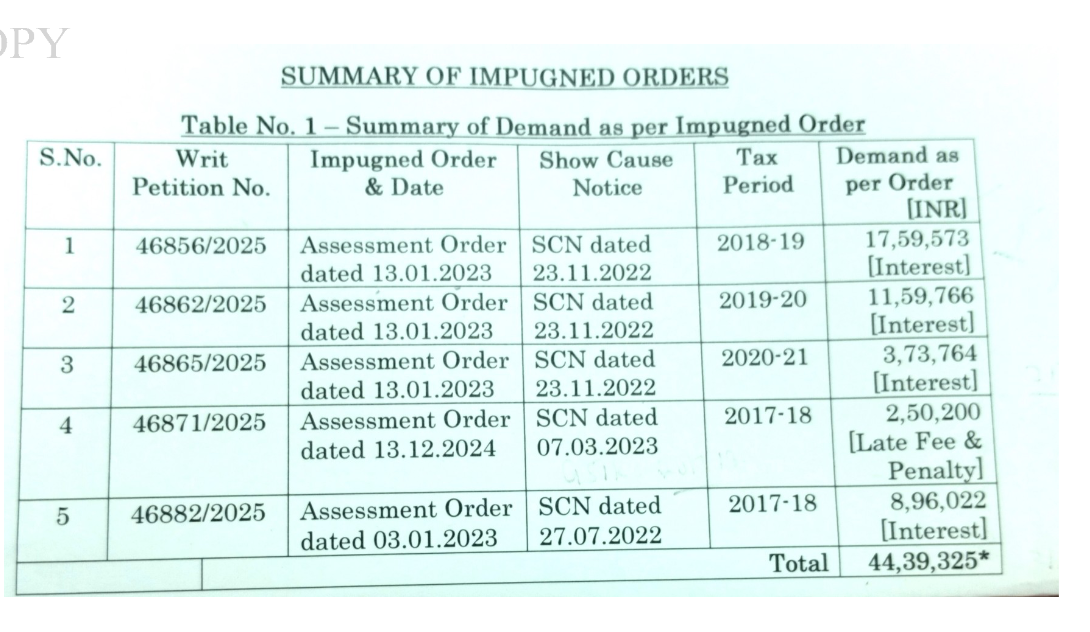
2. Learned counsel for the Petitioner submits that the Petitioner on 20.02.2024 has already paid a sum of Rs.31,39,125/- out of the aforesaid sum of Rs.44,39,325/-. He further submits that the above computation has been made for the first time in the respective impugned Orders. According to the learned counsel for the Petitioner, the amount to be paid towards interest is only Rs.31,39,125/- and not Rs.44,39,325/- and that the computation is incorrect.
3. Learned counsel for the Respondents fairly concedes that the above amount as mentioned above appears to have been paid by the Petitioner.
4. Recording the above submission of the learned counsel for the Respondents, the above mentioned Writ Petitions are disposed by giving an opportunity to the Petitioner to explain the amount payable by the Petitioner towards interest is not over and above Rs.31,39,125/- which was purportedly paid on 20.02.2024.
5. With a view to secure the interest of Revenue, Petitioner is however directed to deposit another Rs.2.5 lakhs over and above the amounts already deposited within a period of 30 days from the date of receipt of a copy of this order.
6. Insofar as the rest of the writ Petitions are concerned as challenge is to the recovery notices issued to the Petitioner’s bank detailed above.
7. In view of the order s passed in so far as the computation of the interest in Writ Petition, the impugned recovery proceedings are directed to be kept in abeyance. Pending further orders by the Respondent. Consequently, all attachment of the Petitioner’s bank account shall stand lifted subject to Petitioner depositing Rs.2.5 lakhs as ordered above.
8. The respondents shall thereafter proceed to pass an appropriate order in so far as the interest is concerned within a period of three months from the date of receipt of a copy of this order .
9. These Writ Petitions stands disposed of with the above observations. No costs. Connected Writ Miscellaneous Petitions are closed.


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


