Back


2025 Supreme(Online)(NCDRC) 3489
NATIONAL CONSUMER DISPUTES REDRESSAL COMMISSION
A.P. Sahi, CJ, Bharatkumar Pandya, J
Y.N. Press – Appellant
Versus
Manager, Canara Bank – Respondent
NC/FA/237/2019 | NC/FA/240/2019 | NC/IA/3073/2022 | 18583/2024
For the Appellants/Petitioners: Mr. Aman Shukla
For the Respondents: Mr. Premtosh K. Misra, Mr. Rajesh K. Gupta
The court established that a bank may incur liability for failure to renew an insurance policy if it has previously taken responsibility for such renewal, impacting compensation to the borrower.
Headnote:(A) Consumer Protection Act, 1986 - Liability of Bank - Insurance Policy - Compensatory Order of Rs.7.00 Lakhs partially allowed against the Bank for failure to renew insurance policy which had lapsed prior to fire incident - Bank's past conduct established obligation to renew policy, failure amounts to deficiency of service - Insurance Company not liable as policy lapsed. (Paras 15, 17, 23, 34, 42)
(B) Evidence in Appellate Proceedings - Additional documents not permitted due to lack of explanation for delayed submission - Police report insufficient for loss assessment; authenticated survey report required for indemnification. (Paras 3, 9, 12)
Facts of the case:
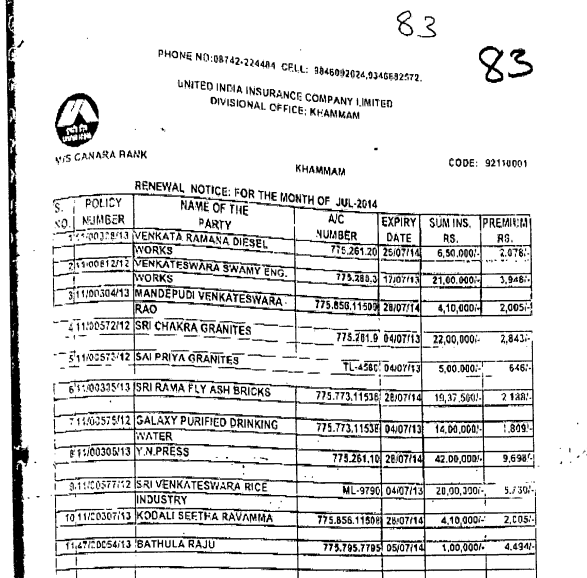
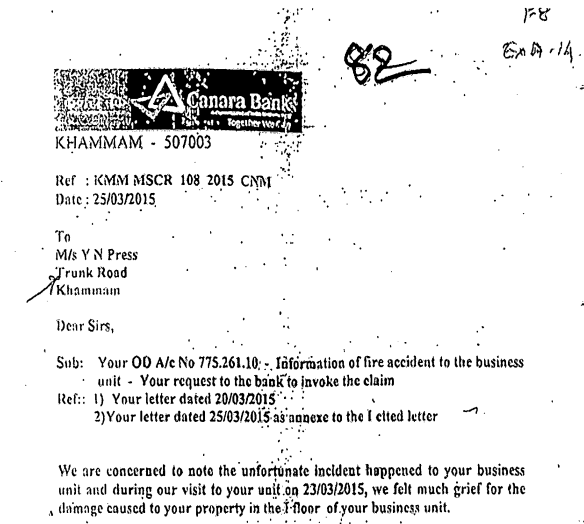
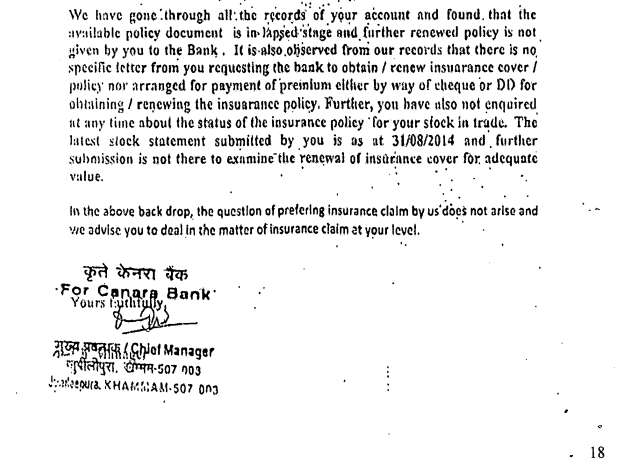
A fire incident occurred on 16.03.2015 affecting the complainant's establishment, claim was denied by the Insurance Company due to a lapsed policy. The complainant argues the Bank had consistently renewed the policy previously and had failed to inform of its lapsing thereby incurring liability. The State Commission initially awarded Rs.7,00,000/- which was contested by both parties.
Findings of Court:
The court reaffirmed the Bank's liability for not renewing the insurance policy and confirmed the compensatory order of Rs.7,00 Lakhs for deficiency of service.
Issues: The primary issue was the liability of the Bank regarding the insurance policy renewal and the validity of submitted evidence for loss assessment.
Ratio Decidendi: The Bank's consistent past actions implied a duty to renew the policy and its failure constituted negligence. The Police report alone does not suffice for claim assessment as per insurance norms.
Result: Bank held liable, complaint awarded Rs.7,00,000/-.
ORDER
PER A.P. SAHI, J., PRESIDENT
These two appeals arise out of a common order passed by the SCDRC Telangana (hereinafter referred to as the State Commission) in Consumer Complaint No. 143 of 2016 whereby the complaint filed by the complainant-Y.N. Press (appellant in NC/FA/237/2019 and respondent no.l in NC/FA/240/2019) has been partly allowed, compensating the complainant to the tune of Rs.7.00 Lakhs for the loss sustained by the complainant in a fire that took place on 16.03.2015. The claim was repudiated by the United India Insurance Company Ltd. (respondent no.2 in NC/FA/237/2019) (hereinafter referred to as the Insurance Company) on the ground that the policy had lapsed and had not been renewed and consequently the complainant had neither any insurable interest nor any surviving right to claim compensation.
Insofar as New India Assurance Co. Ltd., arrayed as respondent no.2 in NC/FA/240/2019, is concerned, it had been wrongly impleaded and therefore vide order dated 24.10.2019 it had been deleted on an application being made in this behalf.
Aggrieved, the complainant preferred the complaint under the Consumer Protection Act , 1986, arraying the Insurance Company as well as the Canara Bank where the goods were hypothecated (appellant in NC/FA/240/2019 and respondent no.l in NC/FA/237/2019) as opposite.parties. Needless to mention that a Cash Credit Agreement dated 29.03.2010 was in existence as against which the stocks of the complainant were hypothecated and to secure the stocks under the agreement the complainant-borrower was enjoined with the obligation of getting the goods insured. It is the said obligation which has become the bone of contention as contained in Clause-12 of the agreement which is extracted hereunder:
"12. That the said goods and the said debts and assets shall be kept at the Borrower's risk and expenses and the Borrower shall at their own expense during the continuance of this security keep the said goods in good and marketable condition and in proper working order and shall likewise at its own expense insure and keep insured the said goods against loss or damage by fire, roit, civil commotion and all such other risks as the Bank shall require for the full market/repiacement value thereof in an insurance office or offices to be approved by the Bank and shall deliver the policies of insurance to the Bank and shall likewise deliver the receipt for the last premium paid for every such policy of insurance and shall assign to the Bank every such policy of insurance and shall pay to the Bank all proceeds of any policy received by the Borrower during the continuance of the security and deliver to the Bank the renewal receipts and policies. In default, the Bank may (but shall not be bound to) keep in good condition and render marketable and in good working order the said goods or effect or renew such insurance. Any premium paid by the Bank and any costs, charges and expenses incurred b the Bank shall be repaid b the Borrower on demand forthwith hypothecated. The Bank shall be entitled without prejudice to all its other rights and powers to debit the amount of such premium costs, charges and expenses to the cash credit accounts of the Borrower in such manner as it deems fit. AH sums received under such insurance shall be applied in or towards liquidation of the amount for the time being due to the Bank as provided therein.
a) The Borrower hereby undertakes to indemnify and keep the Bank indemnified at ait times.
b) The Bank is at liberty and is not bound to effect such insurance at the risk, responsibility and expense of the Borrower with any Insurance Company only to the extent of the value of the security as estimated by the Bank and that in the event of insuring the security, the Bank shall not be considered or deemed to be responsible or liable for non-admission or rejection of the claim wholly or in part whether the claim is made by the Bank or the Borrower.
c) It is expressly undertaken hereby the Borrower th