Back


2025 Supreme(Online)(NCDRC) 3563
NATIONAL CONSUMER DISPUTES REDRESSAL COMMISSION
A.P. Sahi, PRESIDENT, Bharatkumar Pandya, MEMBER
Future Generali Insurance Company Limited – Appellant
Versus
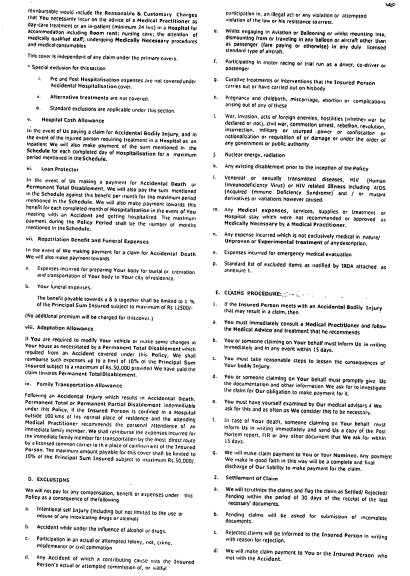
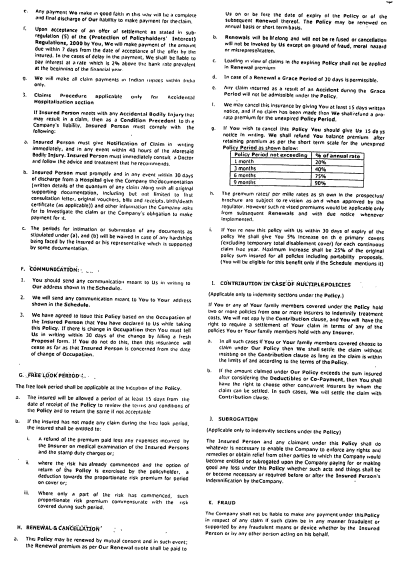
Vijay Singh Gurjar – Respondent
NC/RP/3392/2016 | NC/RP/3393/2016
For the Petitioner:Mr. S. Surender, Advocate, Ms. Akansha Singh, Advocate
For the Respondent:Mr. Avnish Dave, Advocate, Mr. Aadhar Saha, Advocate
Clear distinction exists within insurance policy terms regarding total and partial disability indemnities, emphasizing adherence to contract specifics.
Headnote:(A) Insurance Contracts - Terms of policy defined indemnity for permanent total and partial disabilities - Clear distinction exists in compensation amount payable. (Paras 15, 20, 21)
(B) Consumer Protection Act - Scope of judicial review - Commission cannot rewrite terms of the insurance contract nor exceed its jurisdiction. (Paras 22, 23)
Facts of the case:
The complainant suffered a severe injury in an accident leading to amputation of the arm and claimed total indemnity. District Commission deemed it partial disability; State Commission ruled total, leading to these revision petitions.
Findings of Court:
The terms of the policy clearly stipulate compensation amounts; the complainant's injury classified as permanent partial disability, entitled only to specified indemnity.
Issues: Whether the injury constituted permanent total disability and if the findings of lower commissions overstepped contractual terms.
Ratio Decidendi: The unambiguous terms of the policy clearly define disability types and respective compensations; the court ruled that the respondent only suffered a permanent partial disability as per policy specifications, dismissing claims for total disability compensation.
Result: Revision petitions are allowed, orders of lower commissions set aside.
| Table of Content |
|---|
| 1. claim for indemnity amount arising from injury insurance. (Para 1 , 2 , 3) |
| 2. court's analysis of unambiguous contract terms. (Para 4 , 8 , 15 , 17) |
| 3. arguments regarding interpretation of policy terms. (Para 5 , 10 , 11) |
| 4. court's ruling on defined disability categories. (Para 20 , 21) |
| 5. final verdict regarding allowed claims. (Para 23 , 24) |
ORDER
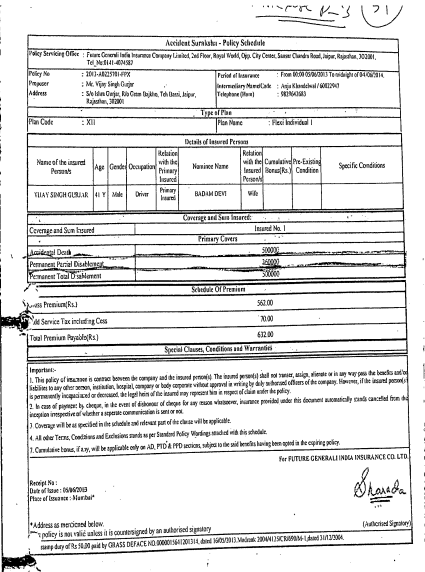
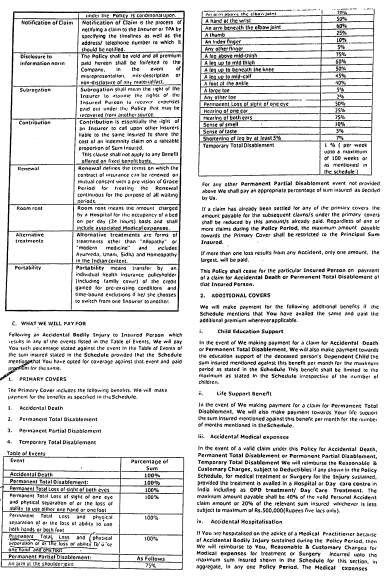
1. The respondent/ complainant had purchased an Accident Suraksha Insurance Policy from the petitioner company, the duration whereof was from 05.06.2013 to 04.06.2014. He unfortunately met with an accident on 02.01.2024, and as a consequence of the said accident his right hand was severely injured that led to its amputation from the shoulder joint. An Insurance claim was filed before the Insurance Company and treating the said dismemberment of the right hand as L a permanent partial disability, 75% of the insured amount as per the terms of the policy was paid to the respondent/ complainant.
2. The respondent accepted the same under protest, claiming that he was entitled for permanent total disability claim of Rs.5,00,000/- and consequently he should be indemnified to the aforesaid extent. Having failed get the claim satisfied, he filed consumer complaint no. 697 of 2014 before the District Commission that was partly allowed on 06.04.2016 holding that the complainant had suffered permanent partial disablement and not permanent total disablement and therefore under the policy he was entitled to the entire claim of Rs.3,60,000/-, and not 75% thereof. Accordingly the balance of 90,000/- was directed to be paid together with interest.
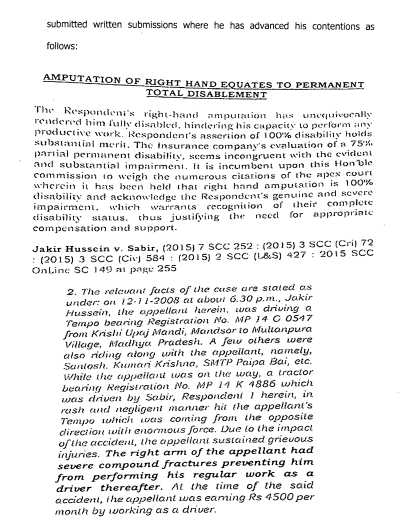
3. The complainant felt aggrieved by the finding of permanent partial disability and consequential reduced payment and therefore FA/642/2016 was filed by the complainant questioning this part of the order of the District Commission. He prayed for an enhanced amount to the tune of Rs.5,00,000/-. The Insurance Company felt aggrieved by the order contending that under the terms of the policy it was only 75% of the amount which was payable and therefore there was no justification to award the entire amount of Rs.3,60,000/-. Both the appeals were heard simultaneously and vide order dated 28.10.2016 the appeal filed by the Insurance Company was dismissed and that filed by the complainant for enhancement was allowed. The State Commission came to the conclusion that the nature of the injury suffered by the complainant amounts to a permanent total disability and therefore the finding on this issue by the District Commission was erroneous, hence the complainant was entitled for permanent total disability indemnity of Rs.5,00,000/-.
4. The Insurance Company has come up assailing the impugned order of the State Commission in these two revision petitions that arise out of the two respective appeals referred to above.
5. Mr. S. Surender, learned counsel for the Insurance Company has advanced a short and a crisp argument contending that the impugned orders of the District Commission extending the full amount of Rs.3,60,000/- for permanent partial disability is against the terms of the policy, and since the parties are bound by the terms of the contract of insurance, the District Commission could not have enhanced the amount payable beyond 75% of the amount payable. The District Commission therefore exceeded by granting more than what was indemnifiable.
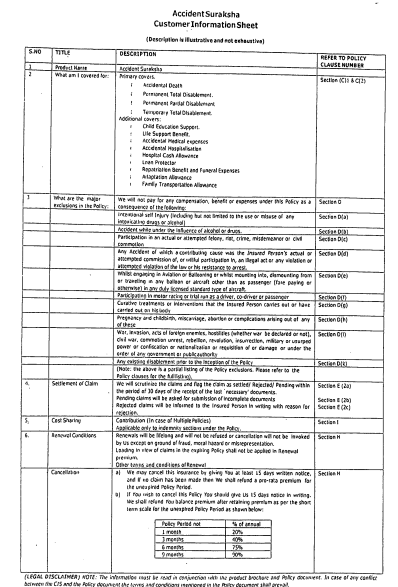
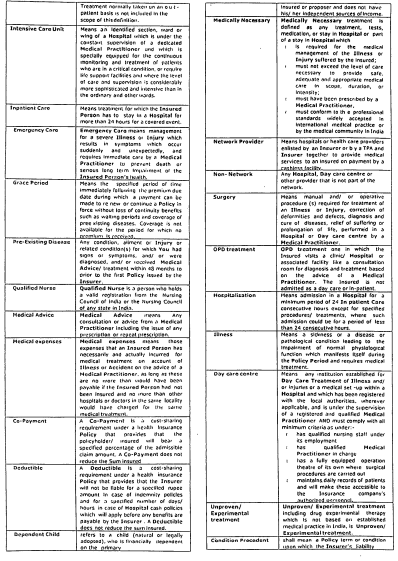
6. He further submits that the State Commission has gone one step ahead by treating the disability to be a permanent total disability on the basis of its own perception, which is in total defiance of the terms of the policy, which defines categorically the nature of the disabilities and the indemnity that is admissible against the injury suffered. He has filed the fair copy of the Accident Suraksha Policy Customer Information Sheet, which records the relevant facilities available and which document remains undisputed. He has also invited the attention of the Bench to the terms of the policy which provides the max