Back


2026 Supreme(Online)(NCLT) 2158
NATIONAL COMPANY LAW TRIBUNAL
Praveen Gupta, Member (Judicial), Ashish Verma, Member (Technical)
Ashok Goenka – Appellant
Versus
Rajeev Ranjan Singh – Respondent
CP (IB) No. 80 of 2025
For the Petitioner/Personal Guarantor: Vibhor Garg, Keshav Tiwari
For the RP: Srijan Mehrotra, Anuj Kumar
For the Res./ Bank: Saurabh Kushwaha
A personal guarantor can initiate personal insolvency resolution process under Section 94 of the IBC, and winding up of the corporate debtor does not bar such proceedings.
Headnote:(A) Insolvency and Bankruptcy Code, 2016 - Sections 94, 95, 96, 97, 99, 100, 101, 102, 104, 105, 106, 107, 108, 109, 110, 111, 112, 208 - Section 79(15) - Limitation Act, 1963 - Article 137 - Application by personal guarantor for initiation of personal insolvency resolution process - The application was filed under Section 94 of the Code read with Rule 6 of the PIRP Rules - The debts were not excluded debts under Section 79(15) - The application was filed within the limitation period prescribed under Article 137 of the Limitation Act - The winding up of the corporate debtor does not bar proceedings against the personal guarantor.
Facts of the case:
The applicant, a personal guarantor, filed an application under Section 94 of the Insolvency and Bankruptcy Code, 2016, seeking initiation of the personal insolvency resolution process (PIRP) in respect of himself. The corporate debtor had defaulted on loans from multiple banks, and the personal guarantor had executed guarantees. The corporate debtor was ordered to be wound up in 2003. The Debt Recovery Tribunal (DRT) crystallized the liability of the corporate debtor and guarantors in 2024. The personal guarantor stated he had no means to repay the debt and filed a no-objection to the initiation of PIRP.
Findings of Court:
The court found that the application satisfied all requirements under Section 94 of the Code and was complete. The debts were not excluded debts. The application was filed within the limitation period, with a fresh default occurring on the date of the DRT order (07.10.2024). The pendency of liquidation proceedings against the corporate debtor does not bar initiation of PIRP against the personal guarantor. The resolution professional also recommended admission of the application.
Issues: Whether the application under Section 94 satisfies the requirements of the Code, whether the debts are excluded debts, whether the application is within limitation, and whether the pendency of liquidation proceedings against the corporate debtor bars the proceedings.
Ratio Decidendi: The court held that a personal guarantor can file an application under Section 94 of the Code for initiation of PIRP, provided the debts are not excluded debts and the application is within the period of limitation. The winding up/liquidation of the corporate debtor does not bar such proceedings against the personal guarantor.
Result: Application admitted; Personal Insolvency Resolution Process initiated.
| Table of Content |
|---|
| 1. application for personal insolvency resolution process (Para 1 , 2 , 3 , 4 , 5 , 6 , 7 , 8 , 9 , 10 , 11) |
| 2. resolution professional's report and recommendations (Para 12 , 13 , 14 , 15 , 16) |
| 3. court findings and order of admission (Para 17 , 18 , 19 , 20 , 21 , 22 , 23 , 24 , 25 , 26 , 27) |
ORDER
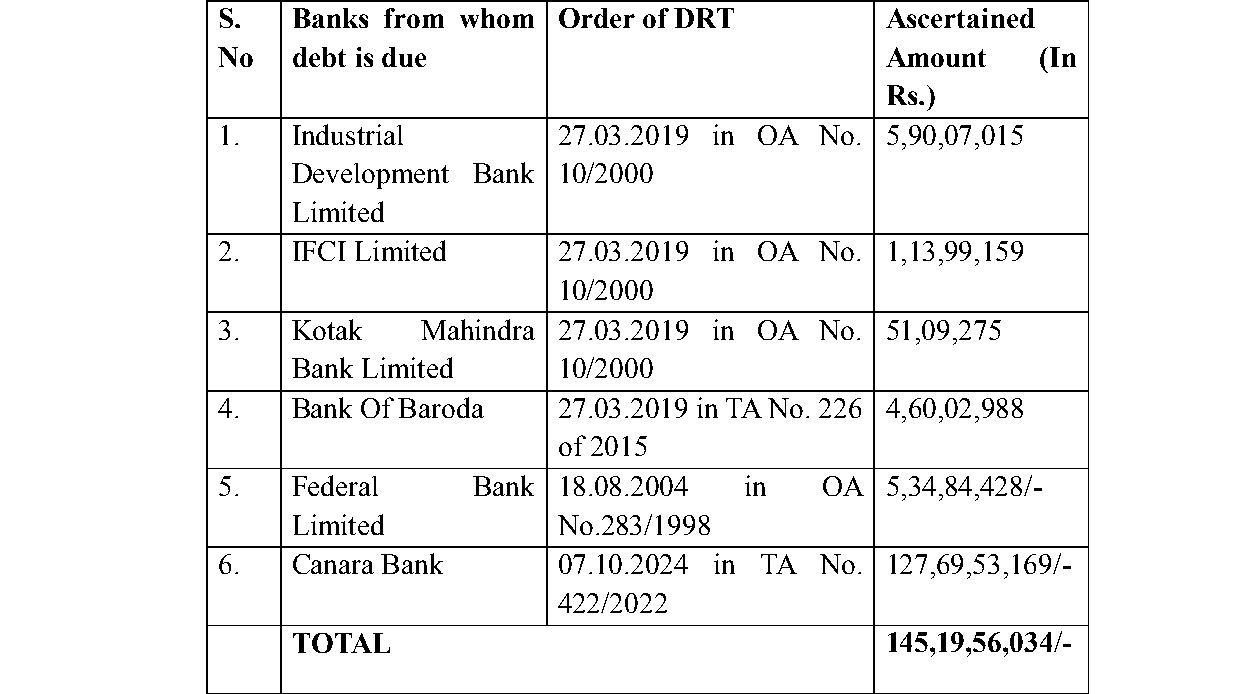
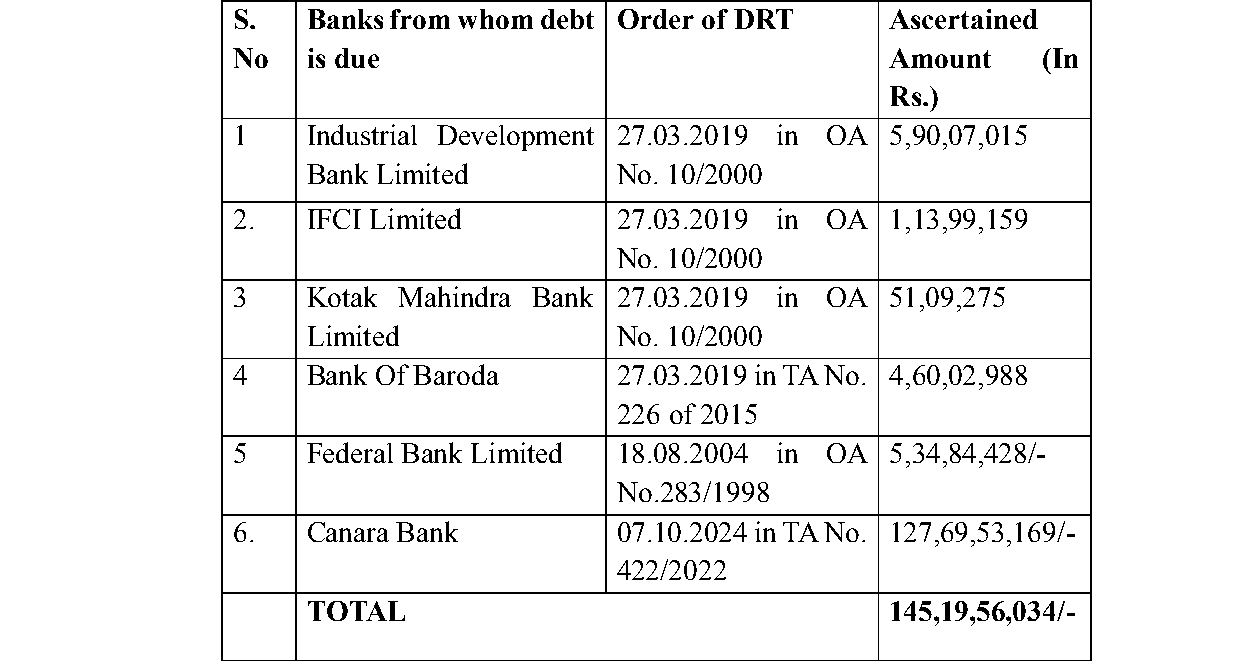
1. The present application has been filed on 07.05.2025 by Mr. Ashok Goenka, the Personal Guarantor to M/s Premier Vinyl Flooring Limited (hereinafter referred to as the “Corporate Debtor”), under Section 94 of the Insolvency and Bankruptcy Code, 2016 (hereinafter referred to as “the Code”) read with Rule 6 of the Insolvency and Bankruptcy (Application to Adjudicating Authority for Insolvency Resolution Process for Personal Guarantors to Corporate Debtors) Rules, 2019 (hereinafter referred to as “PIRP Rules”). Through this application, the Applicant seeks initiation of the insolvency resolution process in respect of himself as the Personal Guarantor to the Corporate Debtor that failed to repay the loan taken as principal borrower from various Financial Creditor banks. The total principal amount of the loan taken from various banks is aggregating to Rs. 145,19,56,034/- (Rupees One Hundred and Forty-Five Crores Nineteen Lakhs Fifty–Six Thousand and Thirty-Four only) along with interest and penalties. The Date of Default, as mentioned in Part III of the Petition with respect to loans taken from various banks are 18.08.2004, 27.03.2019 and 07.10.2024 after determination of the liability by the Debt Recovery Tribunal (DRT).
2. Part I of the application sets out the particulars of the Applicant, whose address is stated as C/o Mr. D.K. Seksaria, 21, Govind Sadan Road, Gadaipur, Mehrauli, New Delhi–110030, as well as the details of the Corporate Debtor, M/s Premier Vinyl Flooring Limited (presently under liquidation by the order dated 12.03.2007 the Hon’ble High Court, Allahabad), having its registered office at 10/1, Industrial Area, Sikandrabad, Bulandshahr, Uttar Pradesh. In view of the aforesaid and in terms of Section 60 of the Code, this Tribunal has the jurisdiction to entertain and adjudicate the present application.
3. Part III of the petitions provides the particulars of the debt, which in the present case totals to Rs. 145,19,56,034/- along with interest and penalties. The dates of default, as reflected therein, are 18.08.2004, 27.03.2019 and
07.10.2024.
4. The Applicant, in the application filed under Section 94 of the Code, has submitted that the Corporate Debtor, in furtherance of its business requirements, approached the financial creditor, Canara Bank apart from the other banks, for the grant of various short-term fund-based and non-fund- based credit facilities, which were sanctioned, renewed, and extended from time to time. The said facilities were secured, inter alia, by a Deed of Personal Guarantee dated 08.07.1995, executed by Mr. Ashok Goenka along with other personal guarantors, in addition to various other securities.
5. Subsequent to the availing of the aforesaid credit facilities, the Corporate Debtor/Principal Borrower failed to adhere to the financial discipline stipulated under the sanction terms. In accordance with the applicable accounting norms followed by the Financial Creditor Bank and the guidelines issued by the Reserve Bank of India, the loan account of the Corporate Debtor was classified as a Non-Performing Asset (NPA) with effect from 31.03.1997. Subsequently, Canara Bank, being the Financial Creditor, issued a demand notice dated 30.05.1998 calling upon the Corporate Debtor as well as the applicant personal guarantor to pay the outstanding loan amount jointly as well as severally, but as they have failed to pay the due amount, the Financial Creditor, Canara Bank, initiated recovery proceedings by filing Original Application, later renumbered as TA No. 422/2022.
6. Thereafter, the Hon’ble High Court of Allahabad, vide order dated
12.03.2003, passed in CP No. 66 of 1999, directed winding up of