Back


2025 MarsdenLR 2162
COURT OF APPEAL PUTRAJAYA
Ahmad Kamal Md Shahid, JCA
KEMENTERIAN KEWANGAN MALAYSIA & ANOR – Appellant
Versus
HA PACK INDUSTRY SDN BHD & ANOTHER APPEAL – Respondent
[Civil Appeal Nos: P-01(A)-422-06/2024 & P-01(A)-423-06/2024]
Introduction
[1] There are two (2) Appeals fixed for hearing before us, which we heard on the same day. Firstly, Appeal P-01(A)-422-06/2024 (Appeal 422) filed by Kementerian Kewangan Malaysia (the 1st Respondent) and Ketua Pengarah Kastam, Jabatan Kastam Diraja Malaysia (the 2nd Respondent) (collectively referred to as the Respondents). Secondly, is the Appeal by Ha Pack Industry Sdn Bhd (the Applicant) via Appeal P-01(A)-423-06/2024 (Appeal 423).
[2] Both parties are dissatisfied with the decision of the High Court in a Judicial Review (JR) Application filed by the Applicant who is aggrieved with the decision of the 1st Respondent dated 22 May 2023, which conclusively rejected the Applicant's appeal against the 2nd Respondent's decision refusing remission of the remaining 50% of the Bills of Demand amounting to RM903,757.22, which the Applicant had previously paid.
[3] Having heard the appeals, scrutinising the Records of Appeal and submissions by both parties, we decided to allow the Respondents' appeal in Appeal 422 and to dismiss the Applicant's appeal in Appeal 423. These grounds of judgment (GOJ) contain the full reasons for our decision.
Brief Facts Of The Case
[4] The Applicant is a licensed manufacturing warehouse (LMW) operator pursuant to ss 65 and 65A of the Customs Act 1967 (the Act).
[5] The dispute centred around 675 drop shipment deliveries of raw materials from the Applicant's warehouse to two (2) other LMW companies, namely Syarikat Sin Kwang Plastic Industries Sdn Bhd (Sin Kwang) and Wentel Corporation Sdn Bhd (Wentel), between June and August 2017 (the said deliveries).
[6] These transactions involved a local trading company, Stephen Gould Malaysia Sdn Bhd, (Stephen Gould) which ordered goods from the Applicant for direct delivery to Sin Kwang and Wentel.
[7] The following process and manner of deliveries were undertaken:-
a) Sin Kwang and Wentel would order raw materials/components for the requirements of their manufacturing activities from Stephen Gould;
b) Stephen Gould would thereafter order the raw materials from the Applicant;
c) Upon completion of the same and upon request of Stephen Gould, the Applicant would deliver the raw materials directly to Sin Kwang and Wentel respectively;
d) The Applicant would subsequently issue an invoice requesting the payment from Stephen Gould; and
e) Stephen Gould would then issue an invoice requesting for payment from Sin Kwang and Wentel, respectively.
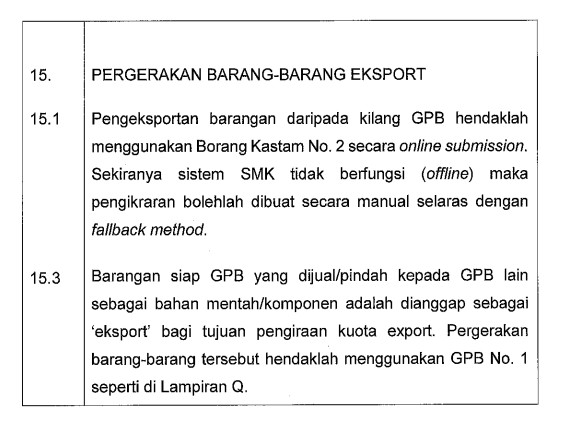
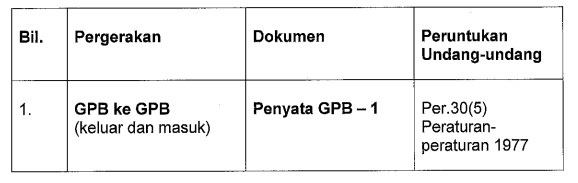
[8] The Applicant contends that the drop shipment transactions as above are permitted and should be considered as the Applicant's export quota in accordance with the guidelines published by the Royal Malaysian Customs Department.
[9] Important to these proceedings is that vide a Mutual Non-Disclosure Agreement dated 1 March 2016 executed between the Applicant and Stephen Gould, the Applicant was prohibited from disclosing its identity to the customers of Stephen Gould, including, but not limited to Sin Kwang and Wentel.
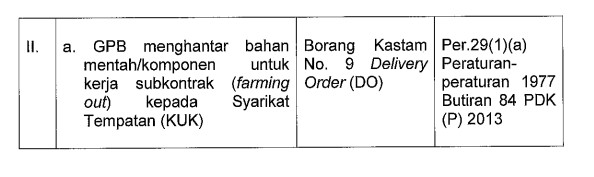
[10] The Applicant contends that it had then declared the said deliveries using Customs Form 9 when LMW General Form should have been used and requested Sin Kwang and Wentel to endorse 'Delivery Order' and Stephen Gould to acknowledge receipt of the deliveries, in which LMW Lampiran 1 should have been used.
[11] Pursuant to an audit conducted on the Applicant, the 2nd Respondent took the position that the said deliveries were all local sales, and accordingly issued Bills of Demand, both dated 19 July 2019, demanding payment of goods and services tax (GST) amounting to RM102,312.14 as well as the payment of import duties amounting to RM1,705,202.31 (the Bills of Demand).
[12] The Applicant had filed an appeal to the 2nd Respondent, dissatisfied with the issuance of the Bills of Demand.
[13] However, in the meantime, pending the Appeal, the Applicant had made payments by instalments totalling RM903,757.22, being 50% of the total sum demanded.
[14]Vide letter from the 2nd Respondent dated