
 Back


IN THE HIGH COURT OF KARNATAKA AT BENGALURU
S.R.KRISHNA KUMAR, J.
Bhandary Gas Agency, Represented By Proprietor, Manjunath Bhandary – Petitioner
Versus
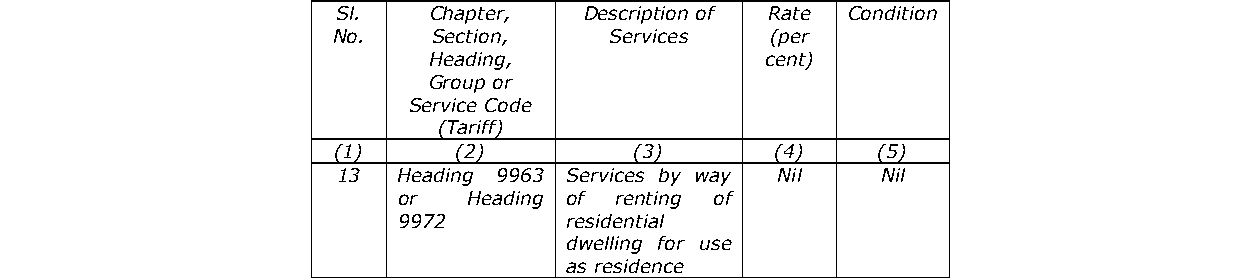
Joint Commissioner Of Commercial Taxes, DGSTO, Malnad Division, Shivamogga – Respondent
Writ Petition No. 9950 of 2024 (T-RES)
Decided On : 05-11-2025
| Table of Content |
|---|
| 1. petitioner seeks relief against gst assessment. (Para 1 , 2) |
| 2. arguments regarding residential dwelling definition. (Para 6 , 7) |
ORDER :
S.R. KRISHNA KUMAR, J.
In this petition, petitioner seeks for the following reliefs:-
“a) Issue a Writ of Certiorari or any direction to quash and set aside the order bearing No.ZD2901240163160 dated: 10.01.2024 under S.107 of the KARNATAKA GOODS AND SERVICES TAX ACT , vide Annexure-A as it is without jurisdiction , arbitrary , void and illegal.
b) Issue a Writ of mandamus or any direction allowing the application dated: 26.09.2022 vide Annexure-G.
c) Issue a Writ of Mandamus or direction to the Respondent No.2 refund the amount of Rs.62,50,716/- along with interest paid by the petitioner under protest.
d) Declare the act of Respondent Authorities of issuing the impugned order vide Annexure-A is arbitrary and bad in the eyes of law.
e) Any other relief/s as this Hon’ble Court deems fit in the interest of justice and equity.”
2. A perusal of the material on record will indicate that on 02.08.2022, the 2nd respondent conducted an audit and prepared a report under Section 65(6) of the GST Act, 2017 and included the rent received from the schedule property, which was leased out by the petitioner with Bhandary Foundation for providing the schedule property for accommodation of students, teachers and staff. On 09.09.2020, the Gram Panchayath has issued the certificate declaring the schedule property as a residential dwelling place. On 17.08.2022, the petitioner filed a response to the audit report explaining as to how the rent collected from residential places is exempted from GST. On 20.08.2022, the 2nd respondent filed a detailed audit report observing that the rent amount collected by the petitioner is from a residential premises and must be exempted from GST. In pursuance of the same, the refund application dated 26.09.2022 having been filed by the petitioner, the 2nd respondent filed a revised audit report by observing that the excess amount paid by the petitioner in a sum of Rs.62,50,716/- which was paid under protest was correct and that the petitioner was not entitled to refund. On 07.11.2022, the petitioner filed objections to the revised audit report highlighting that the fee collected from the petitioner was in relation to the scheduled property which is a residential premises and was being used for the accommodation of students, staff and teachers, despite which, the 2nd respondent proceeded to pass orders dated 10.11.2022 and 17.12.2022 rejecting the refund request. Aggrieved by the said refund rejection orders, the petitioner filed an appeal on 17.01.2023. On 25.01.2023, the 2nd respondent prepared a revised audit report stating that the amount paid by the petitioner under protest was not in excess. The petitioner filed an appeal against the audit report dated 25.01.2023. The petitioner preferred appeals dated 17.01.2023 and 06.03.2023 against the rejection of refund application as well as the revised audit report, to which the 2nd respondent issued the impugned Endorsement dated 23.03.2023 and 1st respondent passed the impugned order dated 10.01.2024 rejecting the appeal filed by the petitioner for refund, who is before this Court by way of the present petition.
3. Heard learned counsel for the petitioner and learned AGA for the respondents and perused the material on record.
4. Learned AGA for the respondents – State would oppose the petition and submits that there is no merit in the petition and that the same is liable to be dismissed.
5. The issue in controversy relating to Entry 13 of Notification 9/2017 dated 28.06.2017 namely, “service by way of renting of residential dwelling for use as a residence” came up for consideration before the Hon’ble Division Bench of this Court in the case of Taghar Vasudeva Ambrish vs. Appellate Authority for Advance Ruling Karnataka, Bengaluru and others – ILR 2022 KAR 3285, wherein it was held as under:-
“In this writ petition, the soli
AI
The court held that leasing residential premises for student accommodation qualifies for GST exemption, underpinning strict interpretation of exemption notifications in favor of the taxpayer.

Hostel services provided for residential purposes qualify for GST exemption under relevant notifications, emphasizing the interpretation of exemption notifications should favor the taxpayer.

Point of Law : Benefit of exemption notification cannot be denied to the petitioner on the ground that the lessee is not using the premises.

The court affirmed that leasing of premises as a hostel for students constitutes a residential dwelling under GST law, qualifying for tax exemption regardless of the lessee's use.




It is well settled that rights of parties will have to be determined on basis of rights available to them on date of suit.
The court ruled that acknowledgment of rent exceeding statutory thresholds affirms jurisdiction under the Transfer of Property Act, negating claims under the Karnataka Rent Act.


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


