Back


2026 Supreme(Del) 192
IN THE HIGH COURT OF DELHI AT NEW DELHI
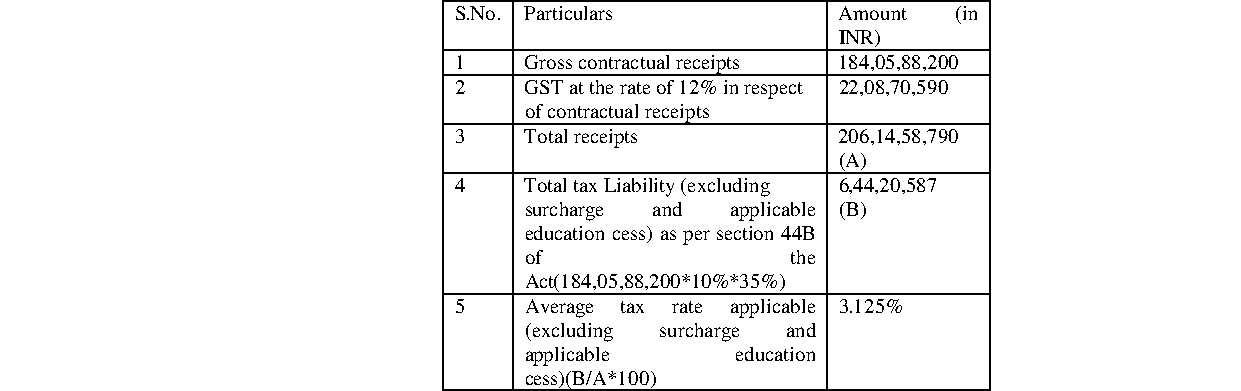
V. KAMESWAR RAO, VINOD KUMAR, JJ.
Pgs Geophysical As - Petitioner
Versus
Income Tax Department, International Tax Circle 2(2)(2) New Delhi & Anr. - Respondents
W.P.(C) 9678 of 2025
Decided On : 20-02-2026
For the Petitioner:Mr. Salil Kapoor, Ms. Soumya Singh, Ms. Ananya Kapoor, Mr. Sumit Lalchandani and Ms. Sakshi Rustagi, Advocates
For the Respondents: Mr. Gaurav Gupta, SSC, Mr.Shivendra Singh, Mr. YojitPareek, JSCs, Mr Surya
Jindal, Advocate.
The court ruled that seismic survey services do not constitute Fees for Technical Services under Section 44DA but are taxable under Section 44BB, reaffirming the principle of consistency in tax assessments.
Headnote:(A) Income Tax Act, 1961 - Section 197 and Section 44BB - Petitioner challenged withholding tax certificate at 7% for tax year FY 2025-26, contending it should be at 3.125% per previous orders; Revenue claimed income taxed as Royalty/Fees for Technical Services (FTS) under Section 44DA. The court found no justification for increasing the withholding rate and referenced its prior decision, which established that similar seismic survey services do not amount to FTS. The Revenue failed to provide reasoning for the change in tax characterization. (Paras 1, 46-53)
Facts of the case:
The petitioner, a non-resident company providing geophysical services, contested the Revenue's order imposing a 7% withholding tax on substantial payments for seismic surveys to be provided to an Indian entity, which differed from the previous year’s lower rate of 3.5%.
Findings of Court:
Impugned order found unjustified without basis for increased tax and remanded back for reconsideration within three weeks.
Issues: The court addressed if the withholding tax rate was correctly raised without justification and whether the income in question qualifies as FTS or Royalty.
Ratio Decidendi: The judgment reaffirmed that seismic survey activities by the petitioner were previously classified under Section 44BB, and the Revenue lacked grounds for reclassification to 44DA.
Result: Writ petition allowed; order under Section 197 set aside.
| Table of Content |
|---|
| 1. background details of the case. (Para 1 , 2 , 3 , 4 , 5 , 6 , 7) |
| 2. arguments for lower withholding tax. (Para 9 , 10 , 11 , 12 , 13 , 15 , 16) |
| 3. judicial observations on the case. (Para 21 , 22 , 23 , 25 , 29) |
| 4. analysis of tax provisions applicability. (Para 44 , 45 , 46 , 47 , 48 , 49) |
| 5. final decision and remand of the case. (Para 54) |
JUDGMENT :
V. KAMESWAR RAO, J.
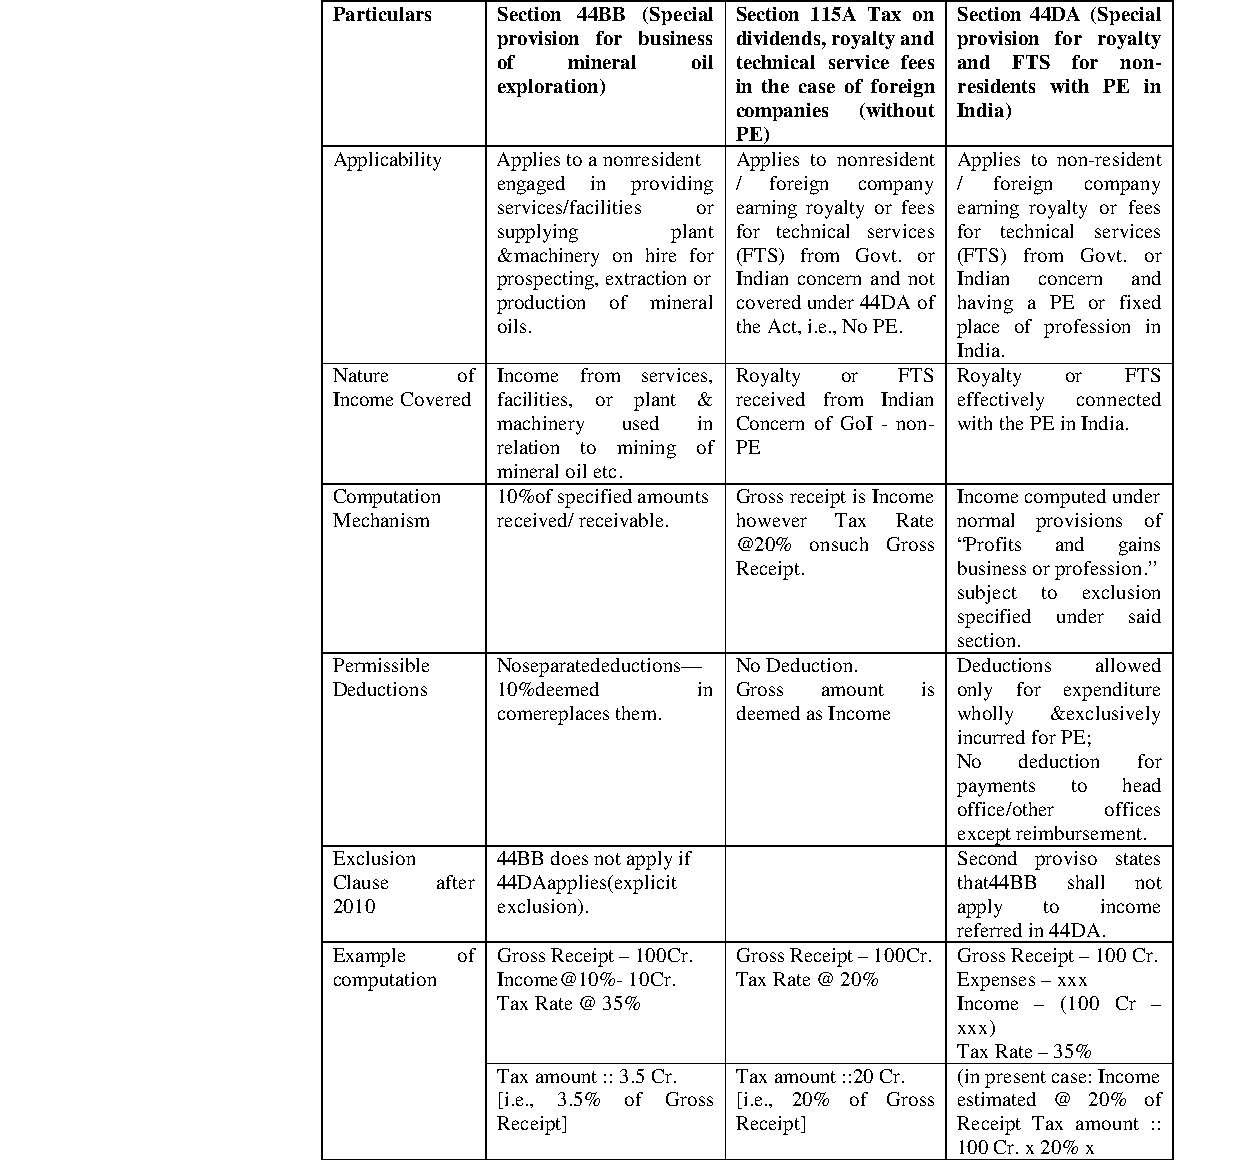
1. The present petition has been filed seeking directions to quash a certificate and order dated 01.05.2025 (impugned order) passed by the respondent No.1/the Revenue under Section 197 of the Income Tax Act, 1961 (the Act) in the case of the petitioner for the Financial Year (FY) 2025- 26, relevant to Assessment Year (AY) 2026-27, whereby a withholding tax of 7% of gross receipts has been imposed on the petitioner.
2. At the outset, we may narrate a brief factual background of the present controversy, as borne out from the petition. The petitioner is a non- resident company and is incorporated in Norway. It is engaged in the business of providing geophysical services to oil and gas industry. It conducts seismic surveys and provides offshore seismic data acquisition and other associated services such as processing and interpretation of such data. On 20.11.2024, the petitioner received a Letter of Award (LOA) from the Oil and Natural Gas Commission (ONGC) bearing no.DLI/2024/BB4SEC/1311217/ZV5AC24001 for hiring its services for 2D and 3D broadband seismic data acquisition, pursuant to which, the parties viz., the petitioner and ONGC entered into a contract on 27.12.2024 bearing no.DLI/2024/BB4SEC/1311217/ZV5AC24001/9010039479 whereby the petitioner is to provide services in relation to 2D and 3D Broadband seismic data for acquisition at the eastern offshore of India.
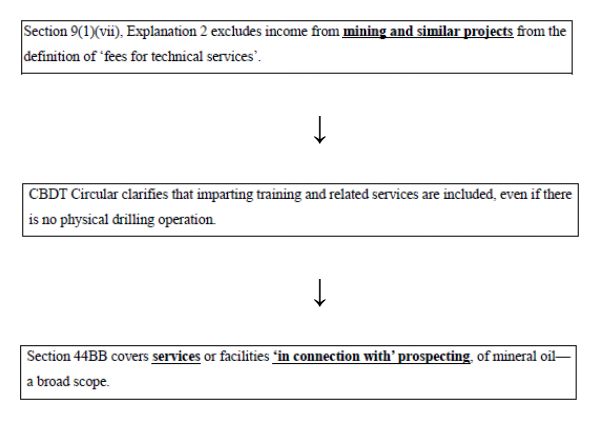
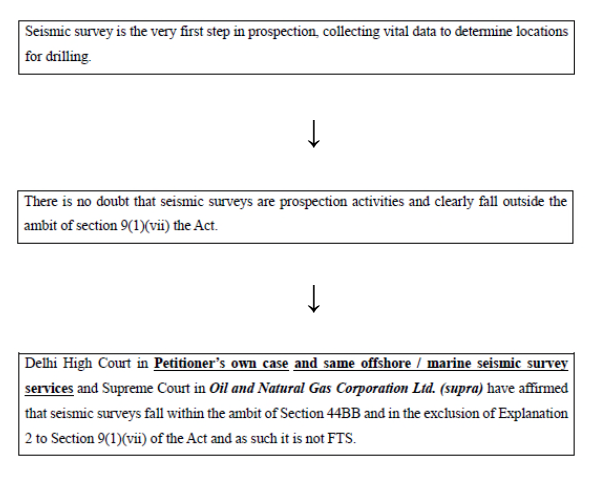
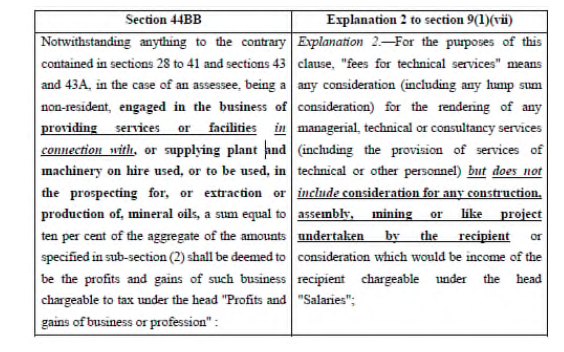
3. Since the petitioner was to receive $22,905,098 (equivalent to Rs. 206,14,58,790) pursuant to the aforesaid LOA in relation to 2D &3D Broadband seismic data acquisition in the FY 2024-25, relevant to AY 2025-26, it applied for a certificate under Section 197 of the Act, requesting the Revenue to grant a lower Tax Deductible at Source (TDS) at the rate of 3.125% by application dated 23.12.2024. In the application, while conceding that as the contract arises in India, the activities of the petitioner are taxable in India, the petitioner contended that since the activities are integral to extraction of oil and gas, the same are liable be taxable as per the provision of Section 44BB of the Act, by relying upon the judgment of the Supreme Court in the case ofONGC v. CIT, [2015] 376 ITR 306, wherein the Court, after examining a bundle of services, including seismic survey services held that that the profits should be computed in accordance with the provisions of Section 44BB of the Act which is a specific provision for computing income of non-resident from provision of services or facilities in connection with or supplying plant and machinery on hire used, to be used in prospecting or extraction or production of mineral oil in India. Reliance was also placed on the judgment dated 08.04.2016 of this Court in the petitioners’ own case in respect of AY 2008-09, titledPGS Exploration (Norway) AS v. Additional Director of Income Tax, 2016:DHC:2949-DB wherein it was held that the activity of 2D/3D seismic survey carried on by the petitioner in connection with exploration of oil, was not in the nature of ‘Fees For Technical Services’ (FTS) in terms of Explanation 2 to Section 9 (1)(vii) of the Act. Accordingly, the petitioner requested for issuance of a certificate under of the Act at the rate of 3.125% as per its calculation, reproduced below:
4. Pursuant to the filing of the said application, the petitioner filed another clarification letter dated 03.01.2025 wherein it provided all the other documents requisitioned by the Revenue, including the copy of the contract, tax residency certificate, etc. The Revenue, considering that the services rendered by the petitioner are taxable under section 44