
 Back


IN THE HIGH COURT OF GUJARAT AT AHMEDABAD
A.S.SUPEHIA, PRANAV TRIVEDI, JJ.
Vijay Ghanshyam Gadhiya Son Of Shri Ghanshyam Gadhiya - Appellant
Versus
Union Of India & Anr. - Respondent
Special Civil Application No. 611 of 2026
Decided On : 20-01-2026
| Table of Content |
|---|
| 1. section 114 imposes penalties for improper export behavior. (Para 5) |
| 2. no jurisdictional error found; alternative remedy exists. (Para 7) |
ORDER :
(PER : HONOURABLE MR. JUSTICE A.S. SUPEHIA)
1 The present writ petition has been filed seeking quashing and setting aside of the Order-in-Original dated 08.10.2025 passed by the Additional Commissioner of Customs, Surat imposing personal penalty of Rs.425,27,99,100/- under Section 114 of the Customs Act, 1962.
2 At the outset, when this Court has pointed out to learned advocate for the petitioner Mr.Paresh Dave about the alternative remedy of filing the appeal under the Customs Appeal Rules, 1962, against the impugned order, it is submitted that since the order is passed bereft of jurisdiction and the penalty which has been imposed is disproportionate, this Court has the jurisdiction and authority to examine the impugned order.
2.1 It is submitted by learned Advocate Mr.Dave that the petitioner is a local supplier who supplies natural diamonds to M/s. Universal Gems situated in Special Economic Zone (SEZ) at Sachin, Surat, is fastened with exorbitant penalty. It is submitted that the action of the respondents in passing the aforesaid order is without jurisdiction as both, i.e. the natural diamonds as wells as artificial (lab grown diamonds) are freely exported and hence the penalty which is imposed by the impugned order for felicitating the export of the diamonds by M/s. Universal Gems is required to be quashed and set aside.
2.2 In support of his submission learned advocate Mr.Dave for the petitioner has placed reliance on the decision of this Court in the case of Shangrila Latex Industries Ltd vs. Union of India 2016 (340) E.L.T. 465 (Guj.), judgement of the Andhra Pradesh High Court in the case of Commissioner of Customs & Central Excise, Hyderabad-II Vs. H.B.Cargo Services., 2011 (268) E.L.T. 448 (A.P), and finally on the judgement of the Supreme Court in the case of Chairman-cum-Managing Director, Coal India Limited & Anr Vs. Mukul Kumar Choudhuri & Ors., (2009) 15 SCC 620 , with regard to proportionality of punishment (penalty) imposed upon the petitioner which is exorbitant.
3 Per Contra, learned Senior Standing Counsel Mr.Shashvata Shukla appearing for the respondents, has referred to the provisions of Sections 113 and Section 114 of the Customs Act, 1962 and submitted that, in fact, the petitioner has felicitated the export of the diamonds of various firms i.e. six in number which are mentioned in the impugned order amounting to Rs.425 crores. Thus, it is urged that the petitioner having an alternative remedy, the present writ petition is required to be dismissed.
4 We have heard the learned advocates appearing for the respective parties.
4.1 It is the case of the petitioner, that he learnt the process of assorting diamonds in the year 2000, and thereafter was engaged in trading as a Broker in diamonds in May, 2001. He used to purchase rough selection of diamonds, and sell the same in the market after assorting them in local market, and the year 2012, he opened his workshop for processing of rough diamonds. However, after Covid-19 pandemic he started working as broker in diamonds, and the trading activity has been discontinued since May, 2021.
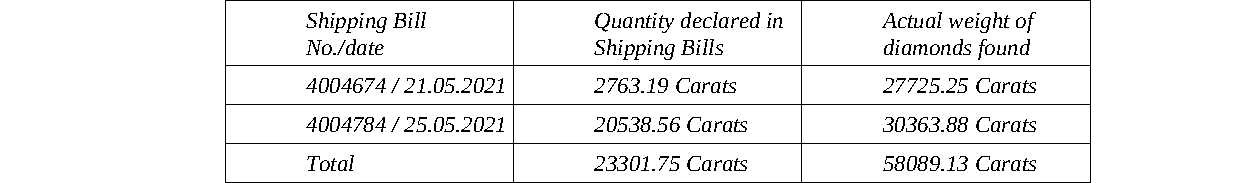
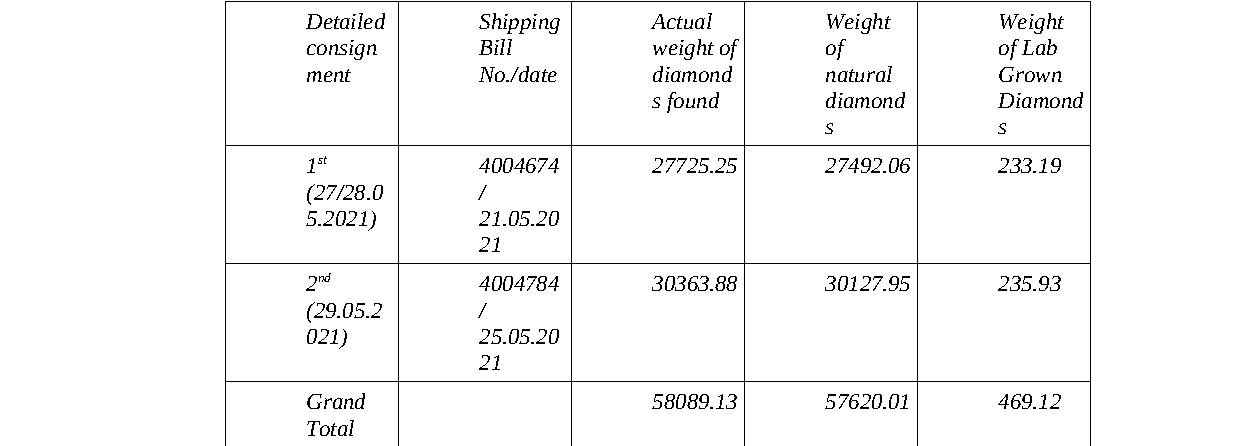
4.2 M/s. Universal Gems commenced its business activities in SEZ, Surat from 25.02.2021. On an information received that M/s. Universal Gems attempted to export Cut and Polished Diamonds mixed with polished lab grown diamonds in guise of lab grown diamonds under two shipping bills nos. 4004674 dated 21.05.2021 and 4004784 dated 25.05.2021, for which they had no permission, and accordingly, the consignment was kept on hold by the Customs authority, and examination of the consignment was done on 27.05.2021, and it was noticed that large number of consignment was mis- declared and their was also vast variation in weight also. Accordingly, search was conducted at the premises of M/s. Universal Gems and various documents were s
AI
The imposition of penalties under the Customs Act is valid when evidence demonstrates active complicity in illegal export activities, justifying the severity of the penalty.


The tribunal clarified the procedural requirements for admissibility of statements made under section 108 of the Customs Act, establishing that improper evidence leads to invalidation of confiscation....

Fraudulent amendment of shipping bills requires adherence to statutory evidential procedures; failure renders penalties invalid.

The main legal point established in the judgment is the imposition of penalties under the Customs Act, 1962 and the liability of an overseas entity for participating in a conspiracy to evade customs ....


An indispensable Tool for Legal Professionals, Endorsed by Various High Court and Judicial Officers
Please visit our Training & Support
Center or Contact Us for assistance

Scan Me!
India’s Legal research and Law Firm App, Download now!


For Daily Legal Updates, Join us on :


 Back to top


