Back


2026 Supreme(Gau) 1008
THE GAUHATI HIGH COURT (HIGH COURT OF ASSAM, NAGALAND, MIZORAM AND ARUNACHAL PRADESH)
MICHAEL ZOTHANKHUMA, KAUSHIK GOSWAMI, JJ.
Commissioner Of Cgst And Excise – Appellant
Versus
M/s Rishu Enterprise – Respondent
C.Ex.App./6 of 2025
Decided On : 22-04-2026
For the Appellant : Mr. S.C. Keyal
For the Respondent: Ms. M.L. Gope, Ms. N. Hawelia
Monetary thresholds for filing appeals must be calculated based on valid, non-time-barred tax demands. Aggregating time-barred claims with valid demands to artificially surpass the minimum monetary limit for an appeal is impermissible, rendering such appeals non-maintainable.
Headnote:(A) Finance Act - Section 73 - Limitation period - Monetary limits for government litigation - Consolidation of assessment years - Maintainability of appeal - Statutory interpretation. An appeal by a revenue authority before a higher judicial forum requires the tax effect to meet a specified monetary threshold. Each financial year constitutes a separate assessment period; consolidated notices covering multiple years are generally impermissible unless justified by exceptional circumstances such as complex fraud where isolation of years is impossible. Time-barred claims cannot be included to artificially reach a monetary threshold, and the calculation of the tax effect must exclude such barred claims to determine if the appeal is maintainable. (Paras 13, 31, 45, 47)
Facts of the case:
Revenue authorities issued a single consolidated demand notice covering four financial years by invoking an extended limitation period due to alleged suppression of facts. The combined tax demand exceeded the minimum monetary threshold required for filing an appeal before the High Court. The assessee contested the maintainability of the appeal, arguing that the tax demands for individual years were below the threshold and that part of the claim was time-barred.
Findings of Court:
Upon examination, it was determined that the demand for the earliest financial year was barred by the statute of limitations. Excluding the time-barred portion, the remaining tax demand fell below the monetary limit set by the government’s policy for reducing litigation. Consequently, the plea for maintainability was rejected based on the fiscal threshold guidelines.
Issues: Whether a consolidated demand notice covering multiple financial years satisfies the minimum monetary threshold for an appeal when a portion of that claim is time-barred.
Ratio Decidendi: Monetary thresholds for appeals must be satisfied based strictly on valid, non-time-barred tax demands. The aggregation of claims across multiple financial years that includes time-barred periods to bypass jurisdictional monetary limits is impermissible. Appellate jurisdiction cannot be invoked if the actionable tax demand, after excluding time-barred claims, fails to reach the prescribed benchmark.
Result: Appeal dismissed.
| Table of Content |
|---|
| 1. summary of case background and appellate questions. (Para 1 , 2 , 3 , 18 , 19 , 20 , 21) |
| 2. parties' contentions regarding maintainability and tax obligation. (Para 4 , 5 , 6 , 7 , 8 , 9 , 10 , 11 , 12 , 13 , 14 , 15 , 16 , 17) |
| 3. court's analysis of monetary thresholds and limitation periods. (Para 22 , 23 , 24 , 25 , 26 , 27 , 28 , 29 , 30 , 31 , 32 , 33 , 34 , 35 , 36 , 37 , 38 , 39 , 40 , 41 , 42 , 43 , 44 , 45 , 46) |
| 4. final determination on appeal maintainability based on monetary limits. (Para 47 , 48 , 49) |
JUDGMENT :
M. Zothankhuma, J.
1. Heard Mr. S. C. Keyal, learned counsel appearing for the appellant. Also heard Ms. M. L. Gope and Ms. N. Hawelia, learned counsels appearing for the respondent.
2. The present appeal makes a challenge to the Final Order No. 75177/2022 dated 08.02.2024 passed by the Hon’ble CESTAT, Kolkata, in Service Tax Appeal No. 75509/2022 by which the appellant’s demand for Service Tax was held to be not sustainable, on the ground that the same had been made merely on the basis of Form 26 AS and by granting an extended period of limitation by the Adjudicating Authority for making such a claim.
3. The substantial questions of law that were framed and the Preliminary objection, which is question No. (iii), are as follows:
“(i) Whether the Tax Authorities can raise and confirm a Service Tax demand solely on the basis of the entries in Form 26-AS issued by the Income Tax Department, which has not been rebutted by an assessee.
(ii) Whether the CESTAT, Kolkata was right in holding that the investigation and the consequential show-cause-notice issued to an assessee was not permissible, by invoking the extended period of limitation under Section 73 of the Finance Act, 1994.
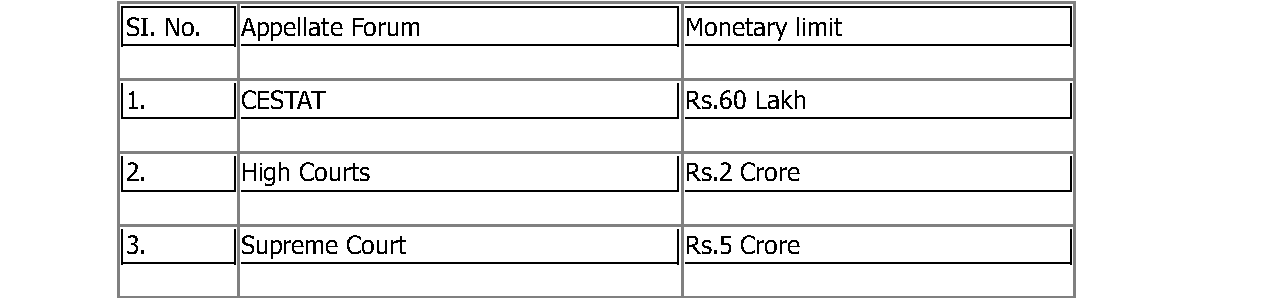
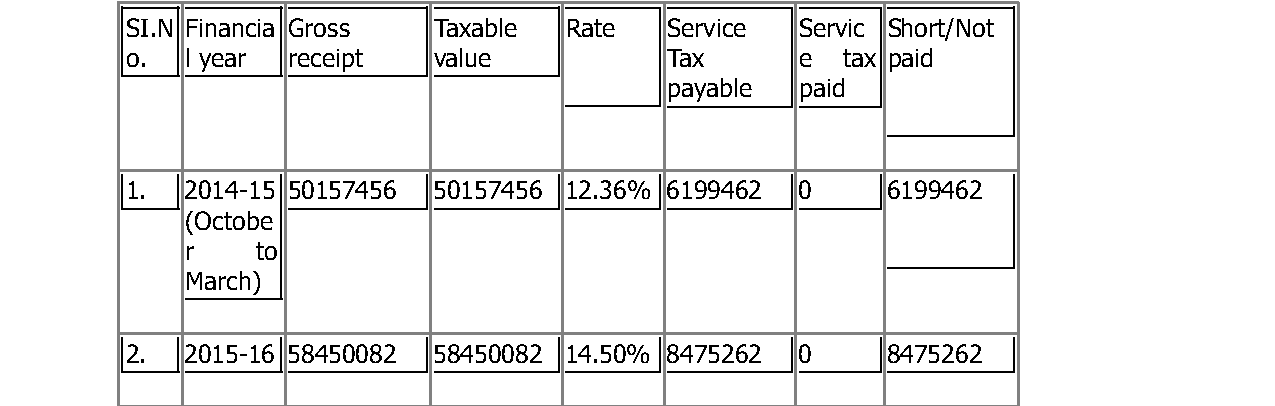
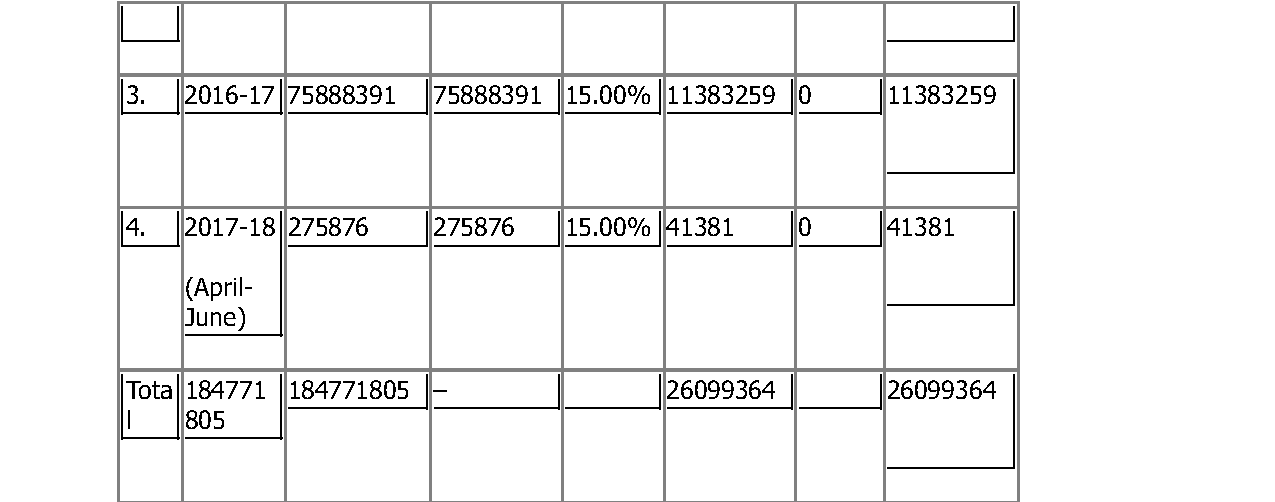
(iii) Whether the appellant could have filed an appeal on the basis of a composite notice demanding Service Tax from 4 (four) assessment years, the total of which crosses the monetary limit of Rupees 2 Crores, without any of the Service Tax for each individual assessment year having crossed the above threshold.”
4. The appellant challenges the Final Order No.75177/2024 dated 08.02.2024 passed by the learned CESTAT, Kolkata on various grounds, one being that the learned Appellate Tribunal has failed to appreciate the respondent/assessee's conduct, which involves non- compliance with statutory requirements and failure to furnish documentary evidence i.e. suppression of facts, despite being given ample opportunity to give reasons why Service Tax should not be paid for the period from 2014-2015 to 2017-2018.
5. The case of the appellant is that the respondent/assessee did not submit any written reply to the Demand-cum-Show-Cause Notice dated 31.12.2020. It did not provide work orders, payment vouchers or running bills to support its contention that the services provided were not liable to Service Tax. Instead, reliance was placed on income tax records including Form-26AS and Audited Financial Statements, which by themselves were insufficient to rebut the Service Tax demand.
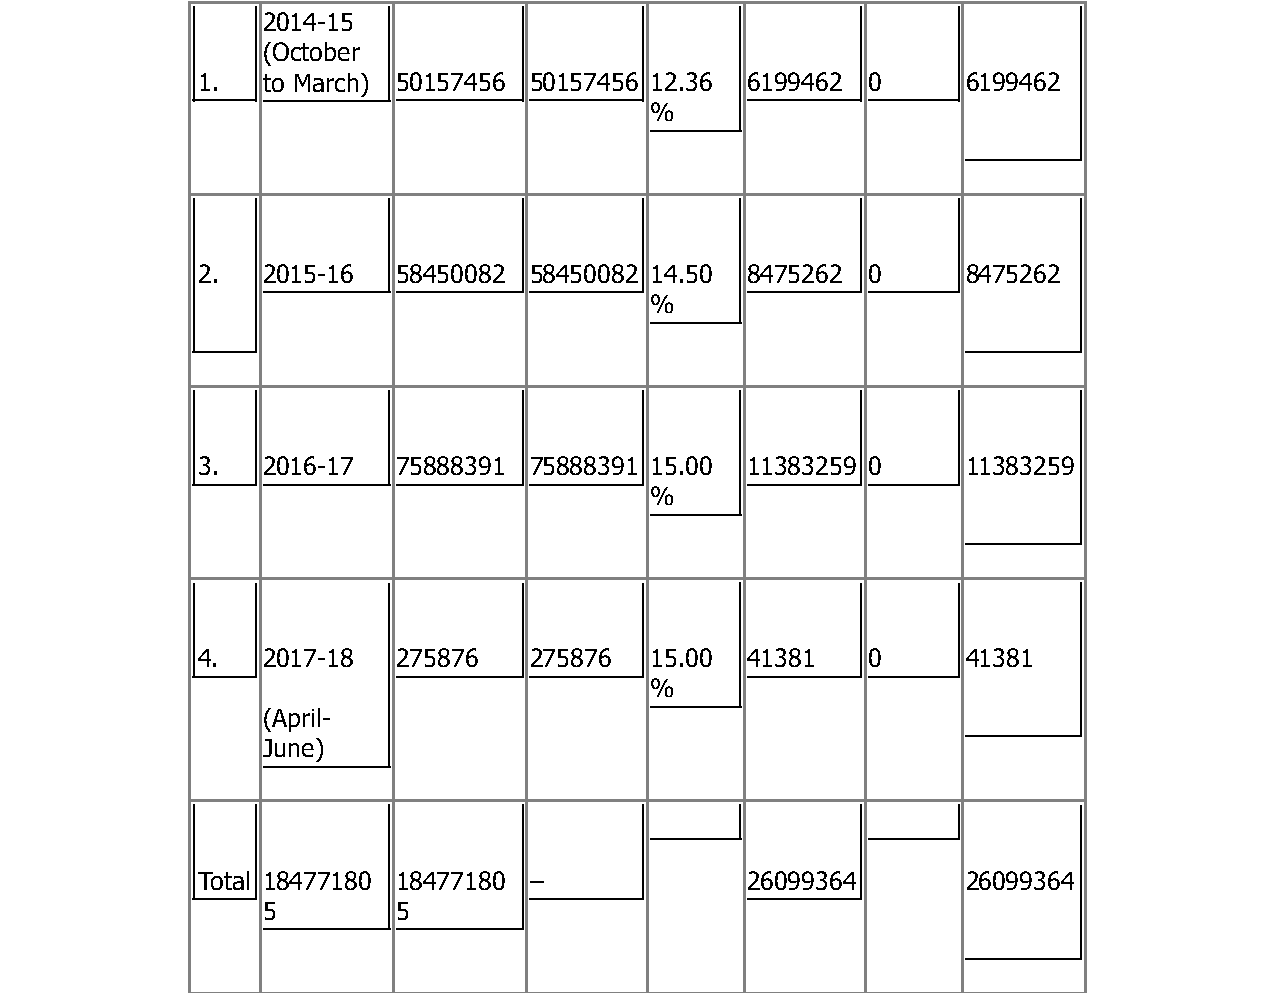
6. The further case of the appellant is that the learned Appellate Tribunal erred in concluding that Service Tax demand based solely on Form-26AS was unsustainable. Also in the absence of any supporting documents or explanation from the respondent/assessee, the Adjudicating Authority was justified in confirming the Service Tax demand of Rs.2,60,99,364/-, for the period from 2014-2015 to 2017-2018.
7. The respondent's case on the other hand is that the assessee in their reply to the Demand-cum-Show- Cause Notice, vide letter dated 20-02-2021, prayed for allowing them 30 days’ time to submit relevant documents, besides the Form-26AS for the years 2014-2015 to 2017-2018, Audited Balance Sheets and copies of the Income Tax Returns submitted for the above period. Further, since they could not locate Work Orders relating to the earlier years, they prayed for time from the Adjudicating Authority to collect the required documents and submit the same. However, the same was