Back


2025 Supreme(All) 3861
HIGH COURT OF JUDICATURE AT ALLAHABAD
SANDEEP JAIN, J.
United India Insurance Co. Ltd. – Appellant
Versus
Smt. Sandhya Mishra And Others – Respondents
First Appeal From Order No. 641 of 2004 Along with Cross Objection No. 14 of 2025
Decided On : 16-12-2025
For the Appellant : Anubhav Sinha, Vijay Kant Dwivedi
For the Respondents: A.N. Srivastava, Ajit Singh Rana, Amrendra Nath Rai, Bhanu Bhushan Jauhari, N.K. Srivastava, P.K. Srivastava, Sanjay Singh.
In motor accident claims, contributory negligence requires evidence beyond mere allegations. Compensation must be computed based on net income after income tax, incorporate future prospects according to established guidelines, and apply valid deductions for personal expenses, ensuring the total award serves as just compensation for surviving dependents.
Headnote:(A) Motor Vehicles Act, 1988 - Section 173 - Indian Penal Code - Sections 279, 337, 338, 427, 304-A - Motor accident claim - Contributory negligence - Assessment of compensation - Evidence of charge-sheet filed against the offending vehicle driver serves as prima facie proof of negligence in the absence of evidence to the contrary - Court emphasized the standard of preponderance of probability over proof beyond reasonable doubt in civil claims. (Paras 5, 8, 9, 10)
(B) Income Tax deductions - Compensation computation - Net income for compensation purposes is determined by deducting statutory tax liability from gross salary - Future prospects are admissible as per beneficial rules for victims above a specific age threshold - Number of dependents necessitates a specific deduction for personal expenses to arrive at just compensation - Interest rates on awards should reflect prevailing statutory or notified guidelines to ensure adequacy of relief. (Paras 2, 3, 5, 6, 11, 12, 13)
Facts of the case:
An appeal was filed by an insurer challenging an award granted for the death of a victim in a road collision, alleging contributory negligence and erroneous computation of salary and future prospects. Claimants cross-objected, seeking enhancement of compensation, arguing that the tribunal failed to account for correct income tax deductions, future prospects, and proper interest rates.
Findings of Court:
The court observed that the insurer failed to provide evidence of contributory negligence, relying solely on the charge sheet which implicated the offending driver. It held that compensation must be assessed on net salary after mandatory tax deductions. Additionally, it found the non-award for future prospects and incorrect deduction for personal expenses and interest rates to be erroneous, warranting modification of the tribunal's award.
Issues: The central issues were the applicability of contributory negligence based on police records, the correct methodology for calculating net income, and the entitlement to future prospects and revised interest rates for the dependents.
Ratio Decidendi: Negligence is determined on a balance of probabilities, and police investigative records constitute sufficient basis for finding of liability absent rebuttal. Compensation awards must be just, accounting for net income, statutory future-earning prospects, and appropriate personal expenditure deductions derived from the number of dependents.
Result: Appeal dismissed; cross-objection allowed; compensation amount modified and enhanced.
| Table of Content |
|---|
| 1. factual background of the accident and the respective contentions regarding liability and compensation. (Para 1 , 2 , 3 , 7 , 8) |
| 2. standard of proof for negligence in motor vehicle claims is preponderance of probability, not beyond reasonable doubt. (Para 4 , 5 , 6 , 9 , 10 , 11) |
| 3. dismissal of the insurance company's appeal due to lack of evidence supporting contributory negligence. (Para 12 , 13) |
JUDGMENT :
SANDEEP JAIN, J.
Order On Appeal :-
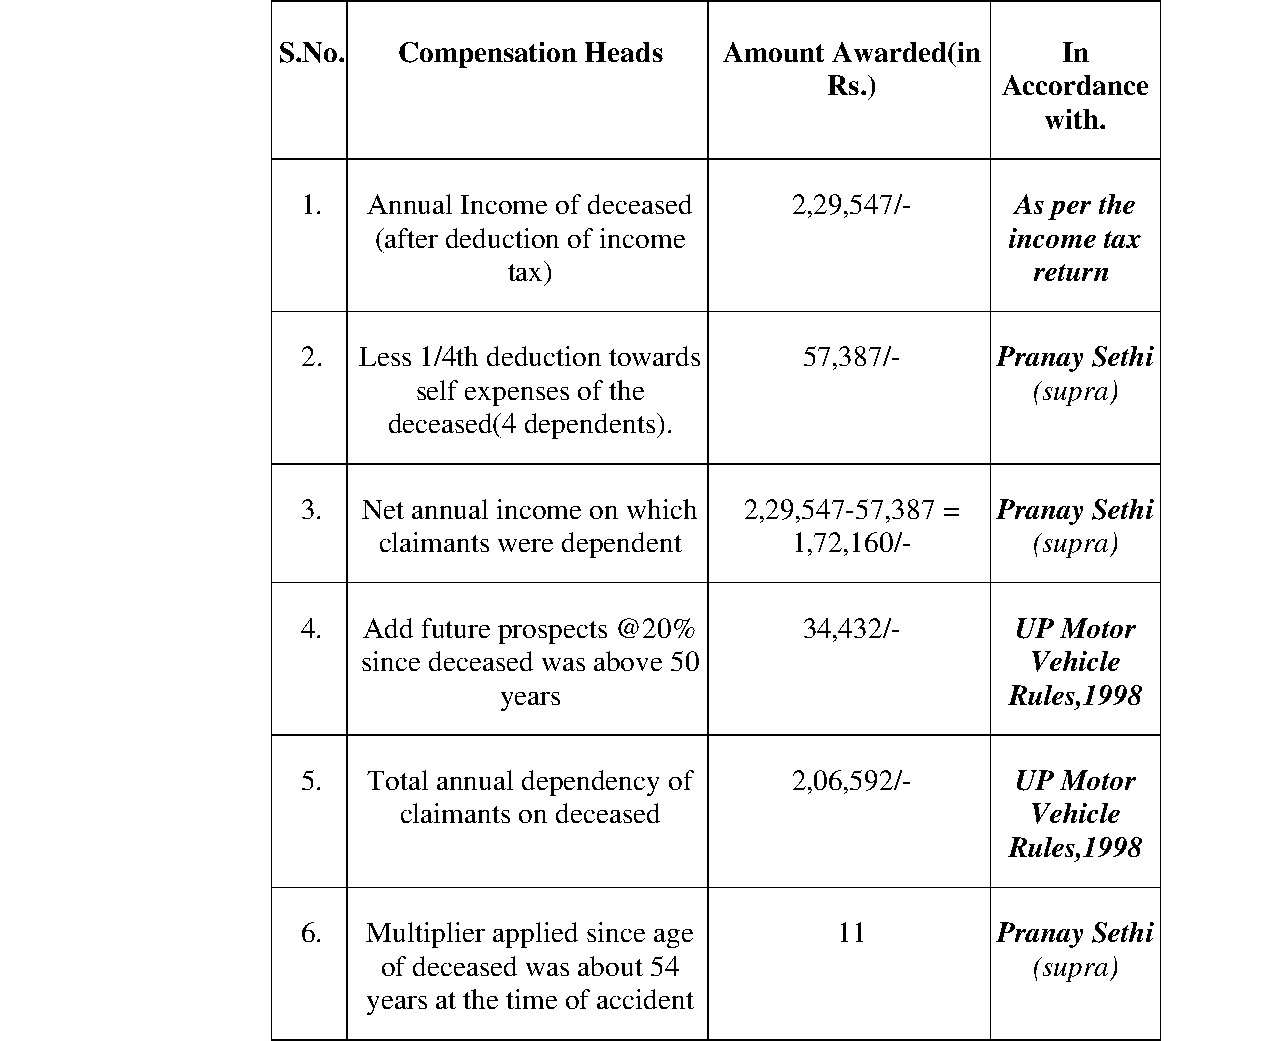
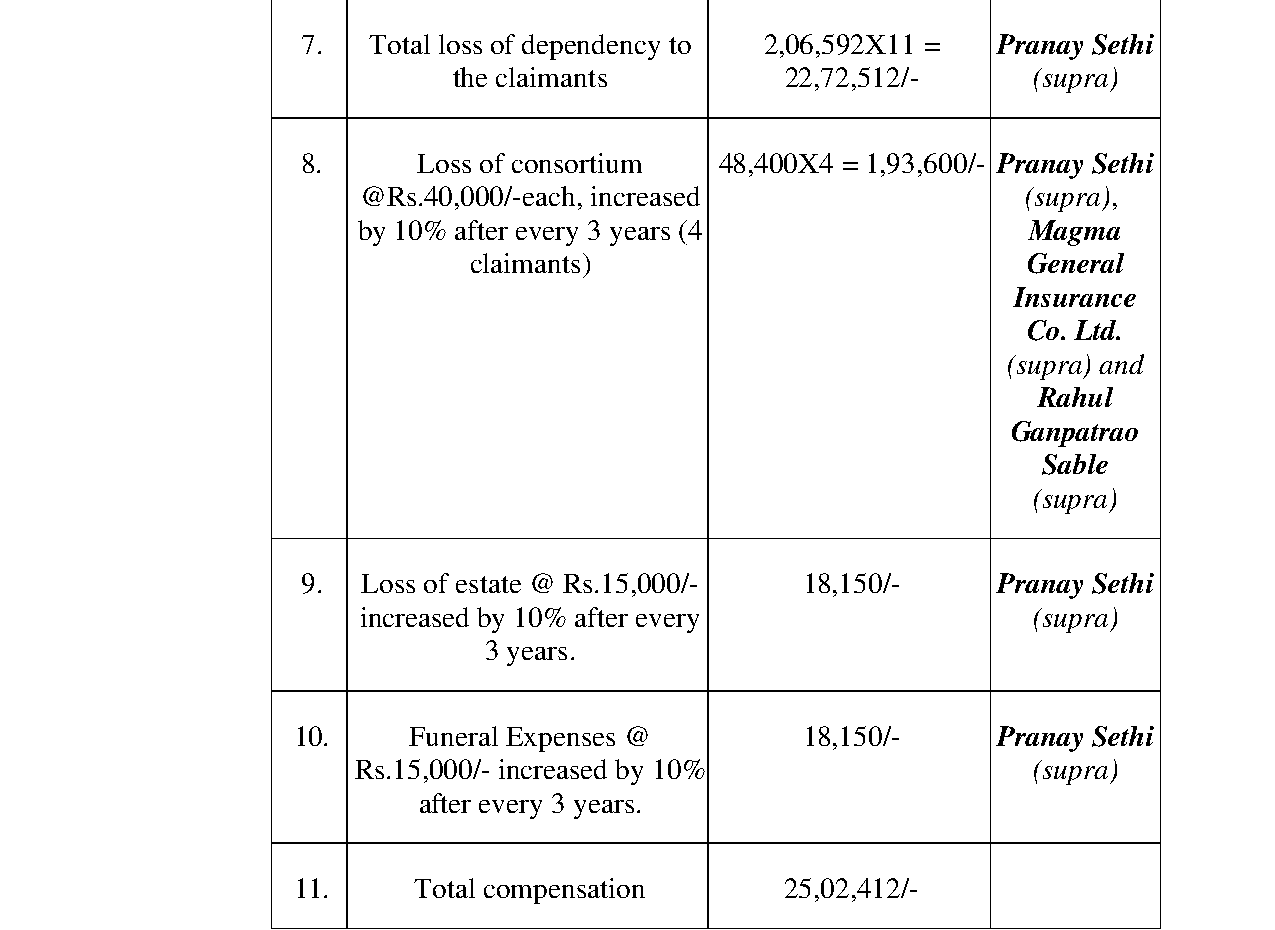
1. The instant appeal under Section 173 of the Motor Vehicles Act, 1988 has been preferred by the Insurer of the offending truck no. PB-29-B- 9079 against the impugned judgment and award dated 05.12.2003 passed by Motor Accidents Claims Tribunal/ Additional District & Sessions Judge, Court No. 3, Shahjahanpur in Motor Accident Claim Petition No. 166/2001 ( Smt. Sandhya Mishra and others v. Mukhtyar Singh and others ), whereby for the untimely death of Sushil Kumar Mishra in a road accident which occurred on 23.04.2001, a compensation of Rs. 18,68,852/- along with interest at the rate of 6.5% per annum has been awarded to the claimants, which has been ordered to be indemnified by the insurer of the offending truck no. PB-29-B-9079.
2. Learned counsel for the appellant- insurance company submitted that the deceased- Sushil Kumar Mishra was travelling in a Santro car No. UP-15-L-4798, which was being driven in a rash and negligent manner at the time of the accident, which collided head on with the truck No. PB- 29-B-9079, but the tribunal has held otherwise. It was submitted that since the accident occurred head on, there was at least 50% contributory negligence on the part of the driver of the above car, which has been ignored by the tribunal. It was further submitted that the deceased was a salaried employee, whose salary was in excess of Rs. 2.50/- lacs per annum, but no amount of income tax has been deducted from his salary by the tribunal while assessing the compensation, which is erroneous. With these submissions, it was prayed that the appeal be allowed.
3. Per contra, learned counsel for the claimants-respondents submitted that no witness was examined by the owner, insurer and driver of the offending truck, as such, there is no evidence to presume that there was any contributory negligence on the part of the driver of the car, in which, the deceased was travelling at the time of the accident. It was further submitted that as per the evidence adduced by the claimants before the tribunal, the accident occurred due to the sole negligence of the offending truck driver, and after investigation in the criminal case, charge sheet has also been submitted against the offending truck driver, which amply proves the rash and negligent driving of the truck driver. It was further submitted that since the deceased was about 54 years old at the time of the accident, compensation towards future prospects of the deceased at the rate of 20% of his income was admissible to the claimants under Rule 220-A of the UP Motor Vehicle Rules, 1998, but the tribunal has not awarded any amount towards it. It was further submitted that since there were four dependents of the deceased, only 1/4th amount was required to be deducted towards the personal expenses of the deceased, but the tribunal has deducted 1/3rd amount, which is erroneous. It was further submitted that the claimants were also entitled to enhanced compensation under non-pecuniary heads and also enhanced interest at the rate of at least 7% per annum as per Rule 220-A of the UP Motor Vehicle Rules, 1998. With these submissions, it was prayed that the appeal be dismissed and the cross-objection preferred by the claimants for enhancement of compensation be allowed.
4. I have heard learned counsel for both the sides and perused the impugned judgement of the Tribunal and the documents submitted with the appeal.
5. The Apex Court in the case of ICICI Lombard General Insurance Company Limited vs. Rajani Sahoo and Others (2025) 2 SCC 599, has hel