Back


2026 Supreme(Online)(ITAT) 5280
INCOME TAX APPELLATE TRIBUNAL (DELHI BENCH)
Anubhav Sharma, Judicial Member, Amitabh Shukla, Accountant Member
Microteck Infrastructure Private Limited – Appellant
Versus
PCIT Delhi-4 – Respondent
ITA 3112/DEL/2025[2020-21]
For the Appellants/Petitioners: S.S. Nagar, CA
For the Respondents: Mukesh Kumar Jha, CIT(DR)
Revision u/s 263 upheld where AO passes mechanical scrutiny order without verifying key issues like creditors/advances despite incomplete evidence from assessee; lack of enquiry renders order erroneous and prejudicial.
Headnote:(A) Income Tax Act, 1961 - Section 263 - Revisionary jurisdiction - Assessment order u/s 143(3) r.w.s. 144B accepting returned income without verification of issues like stock differences, sundry creditors, advances against booking, unsecured loans, purchases, set off of losses, tax rate option u/s 115BAA, and auditor's fee increase - Pr. CIT invoked revision holding order erroneous and prejudicial due to lack of enquiry by AO - Tribunal upheld, observing assessee failed to provide complete details/confirmations to AO during assessment and AO passed mechanical order without independent verification or application of mind, despite scrutiny selection for abnormalities. Explanation 2 to s.263 applicable where no enquiry made on issues requiring investigation. (Paras 3,4,9,10,11)
(B) Income Tax Act, 1961 - Section 263 - Principles - AO is investigator, not merely adjudicator; failure to enquire into facts provoking inquiry renders order erroneous; revision justified if order prejudicial to revenue due to non-enquiry, even if details later provided to Pr. CIT. Mechanical acceptance of incomplete submissions in scrutiny case invalid. (Paras 9,11)
Facts of the case:
Assessee filed return declaring income accepted in scrutiny assessment without additions. Pr. CIT revised order u/s 263 finding AO failed to verify stock valuation changes, creditor details (no PAN/address/ageing), incomplete confirmations for advances/loans from parties (notices u/s 133(6) yielded partial responses), EWS bookings (only 4/132 receipts), squared-off unsecured loans, purchases, losses set off, s.115BAA conditions, and auditor fee jump. Assessee claimed all details provided to AO; Tribunal noted admissions of incomplete submissions and AO's silence on verification.
Findings of Court:
Assessment order set aside by Pr. CIT confirmed by Tribunal; AO to re-examine issues with opportunity to assessee.
Issues: Whether AO conducted necessary enquiries/verification on scrutiny issues; whether order erroneous/prejudicial for invoking s.263; adequacy of assessee's evidence submission.
Ratio Decidendi: Revision u/s 263 valid where AO omits enquiry on material issues in scrutiny assessment, accepting incomplete details mechanically; assessee's later submission to Pr. CIT immaterial - focus on assessment proceedings lapses by both parties.
Result: Assessee's appeal dismissed.
| Table of Content |
|---|
| 1. assessee challenges pcit's section 263 revision. (Para 1 , 2 , 3) |
| 2. pcit identifies ao's inadequate enquiries on wip, creditors. (Para 4 , 5 , 6) |
| 3. tribunal finds assessee and ao deficient in evidence. (Para 7 , 8 , 9 , 10) |
| 4. section 263 valid for ao's lack of enquiry. (Para 11 , 12) |
ORDER
PER AMITABH SHUKLA, AM,
The captioned appeal has been preferred by the assesseeagainstorder dated 18.03.2025 of the Pr. Commissioner of Income Tax-4, New Delhi, [hereinafter referred to as ‘ld. PCIT’] arising out of assessment order dated 26.09.2022 passed u/s 143(3) of the Income Tax Act, 1961 pertaining to Assessment Year 2020-21. The word ‘Act’ herein this order would mean Income Tax Act, 1961.
2. The assessee has raised following grounds of appeal:-
1. Whether on the facts and the circumstances of the case and in law, the Ld.CIT(A) has erred in deleting the addition of Rs. 9,11,40,892 as bogus purchases u/s 37(1) of the Income Tax 1961 as the assessee has not furnished any documentary evidence in respect of business activities carried out by the parties (seller) during the relevant year ?"
2. Whether on the facts and the circumstances of the case and in law, the Ld.CIT(A) has erred in deleting the addition of Rs. 89,14,186/- on account of disallowance of sundry creditors u/s 68 of the Income Tax Act, 1961" as the assessee had failed to furnish the copy of account & confirmation of the said transaction during the assessment proceedings inspite of providing sufficient opportunity by issuing notices u/s 142(1)/show cause notice.
3. The principal controversy raised by the assessee through the impugned appeal is regarding the invocation of revisionary authority under section 263 by the ld. PCIT, Delhi-4. It is the case of the assessee that the impugned assessment order under section 143(3) dated 29.09.2022 does not falls in the category of an order being erroneous in so far as it is prejudicial to the interest of the Revenue and hence deserves to be set-aside and quashed.
4. We have heard rival submissions in the light of material placed on records. At the outset, we deem it appropriate to briefly recapitulate the facts recorded by ld. PCIT in his impugned order as under:-
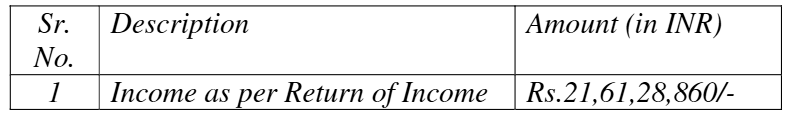
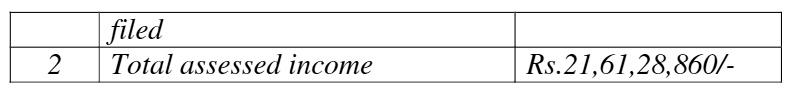
“…... The brief facts emanating from the record is that the assessee filed its Return of Income for the Financial Year (F.Y.) 2019-20, relevant to Assessment Year (A.Y.) 2020- 21 on 13.02.2021, declaring total income of Rs. 21,61,28,860/-. Subsequently the case was selected for scrutiny through CASS.
2. Thereafter, the assessment was finalised under section 143(3) read with Section (r.w.s.) 144B of Income Tax Act, 1961 (hereinafter called 'the Act') on 26.09.2022, accepting return income of Rs 21,61,28,860/-
3. On perusal of the assessment records, it was observed that during the course of assessment proceedings, with respect to the issue of difference between closing and opening stock of WIP, the assessee has claimed that, the difference had arisen because in A.Y. 2019-20, closing WIP of Rs. 5,59,42,71,022/- was shown in column 2 of schedule part-A-manufacturing account of ITR whereas during the year under consideration, opening WIP of the same amount was reflected in column 7 of schedule part-A trading account. However in support of its claim, assessee had only attached relevant extract of ITR. Further on perusal of Note 18 of the financial statements, assessee has also made additions in inventories to the tune of Rs. 60,39,33,050/- during the year under consideration. During the course of assessment proceedings, the FAU has not verified this issue with proper justification and supporting evidences/purchase register/ confirmation etc while accepting your contention.
3.1. On perusal of Balance Sheet, it was noticed that assessee had shown sundry creditors to the tune of Rs. 7,79,15,547/- as on 31.03.2020, During the course of assessment proceedings, the FAO has accepted the contention of the assessee without making any enquiry/investigation. Assessee had submitted d