Back


2026 Supreme(Online)(ITAT) 9824
INCOME TAX APPELLATE TRIBUNAL (MUMBAI BENCH)
Amit Shukla, Judicial Member, Makarand Vasant Mahadeokar, Accountant Member
Quant Transactional Services Private Limited – Appellant
Versus
DCIT- 8(1)(2), Thane – Respondent
ITA No. 9330/Mum/2025 | ITA No. 9329/Mum/2025 | ITA No. 9331/Mum/2025 | ITA No. 9332/Mum/2025
For the Appellants/Petitioners: Vimal Punmiya
For the Respondents: Annavaram Kosuri
Mere disallowance of bona fide claims from books does not attract penalty u/s 271(1)(c)/270A without proof of falsity or misreporting.
Headnote:(A) Income-tax Act, 1961 - Sections 271(1)(c), 270A, 250, 274, 32 - Penalty for furnishing inaccurate particulars or under-reporting/misreporting of income - Assessee company claimed depreciation on block of assets and certain expenses despite no active business operations and assets seized - Mere disallowance of claims based on books of account does not automatically attract penalty unless falsity, concealment or conscious misreporting established - Penalty not leviable on depreciation claims as assets disclosed in financial statements and claim bona fide - Foreign travelling expenses without business nexus attract penalty under S.271(1)(c) - Routine compliance expenses (audit fees, ROC fees, legal fees) not misreporting - Penalty proceedings require specific charge in notice u/s.274; mechanical adoption of quantum findings invalid. (Paras 13-32)
(B) Penalty distinct from quantum assessment - Unsustainable claim not equivalent to inaccurate particulars (Reliance Petroproducts (322 ITR 158)). Penalty needs positive finding of deliberate dishonesty, not mere disallowance. (Paras 5,6,9,10,12,14,20)
Facts of the case:
Assessee in BPO/securities business filed returns declaring losses/nil income; no business activity as assets seized; claimed depreciation and expenses disallowed; penalties levied u/s.271(1)(c) for AY 2015-16,2016-17 and u/s.270A for AY 2017-18,2018-19, confirmed by CIT(A).
Findings of Court:
For AY 2015-16, penalty sustained only on foreign travelling expenses (Rs.1,21,271), deleted on depreciation; recompute penalty. For other years, penalties deleted in full.
Issues: Whether disallowance of depreciation/expenses without business activity constitutes furnishing inaccurate particulars or misreporting justifying penalty; validity of penalty notice u/s.274.
Ratio Decidendi: Penalty not attracted by bona fide claims on disclosed facts/books even if unsustainable; requires proof of falsity/suppression beyond quantum disallowance. Depreciation allowable on block unless ex facie false; routine expenses not penalized absent evidence of bogus nature.
Result: Appeals partly allowed (AY 2015-16), allowed (other AYs).
| Table of Content |
|---|
| 1. no business activity; claims disallowed leading to penalties. (Para 1 , 2 , 3 , 4) |
| 2. assessee contests penalties as bona fide claims. (Para 5 , 6 , 8 , 9 , 10 , 11) |
| 3. ay 2015-16: penalty only on foreign travel upheld. (Para 12 , 13 , 14 , 15 , 16 , 17) |
| 4. ay 2016-17: penalty deleted; ad hoc disallowances insufficient. (Para 18 , 19 , 20 , 21) |
| 5. ay 2017-18: inconsistency and routine expenses; penalty deleted. (Para 22 , 23 , 24 , 25) |
| 6. ay 2018-19: compliance expenses/write-off not misreporting; penalty deleted. (Para 26 , 27 , 28 , 29 , 30) |
| 7. appeals partly/fully allowed; partial penalty sustained. (Para 31 , 32) |
आदेश/ORDER
PER BENCH:
These four appeals filed by the assessee are directed against the separate orders passed by the learned Commissioner of Income Tax (Appeals), National Faceless Appeal Centre (NFAC), Delhi [hereinafter referred to as "CIT(A)"] under section 250 of the Income-tax Act, 1961[hereinafter referred to as "the Act"], confirming the penalties levied by the Assessing Officer under section 271(1)(c) for A.Ys. 2015–16 and 2016–17 and under section 270A for A.Ys. 2017–18 and 2018–19. Since common facts and identical issues are involved, these appeals were heard together and are being disposed of by way of this consolidated order for the sake of convenience.
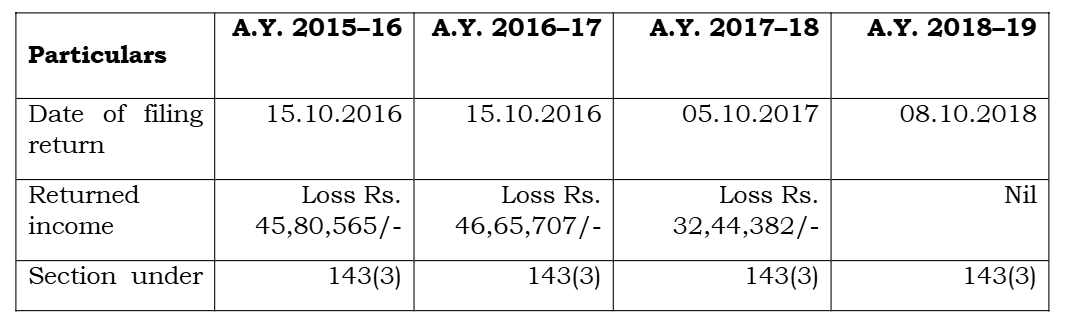
2. Common Facts are such that the assessee is a company engaged in the business of Business Process Outsourcing (BPO), clearing business and acting as custodian of securities. However, during all the years under consideration, it was consistently noted by the Assessing Officer that the assessee could not carry out any business activity. The returns of income for the relevant assessment years were filed declaring losses or nil income. The cases were selected for scrutiny under CASS and statutory notices under sections 143(2) and 142(1) were issued from time to time. In response, the assessee furnished certain details and explanations, though in some years no effective compliance was made. A consistent feature emerging from the record is that the assessee itself admitted, as noted by the Assessing Officer, that its office premises, assets, books and records had been taken over or seized by Reliance Capital Ltd. and Quant Capital Pvt. Ltd. Further, it was also noted that no bank transactions were carried out in certain years and there was complete absence of business operations.
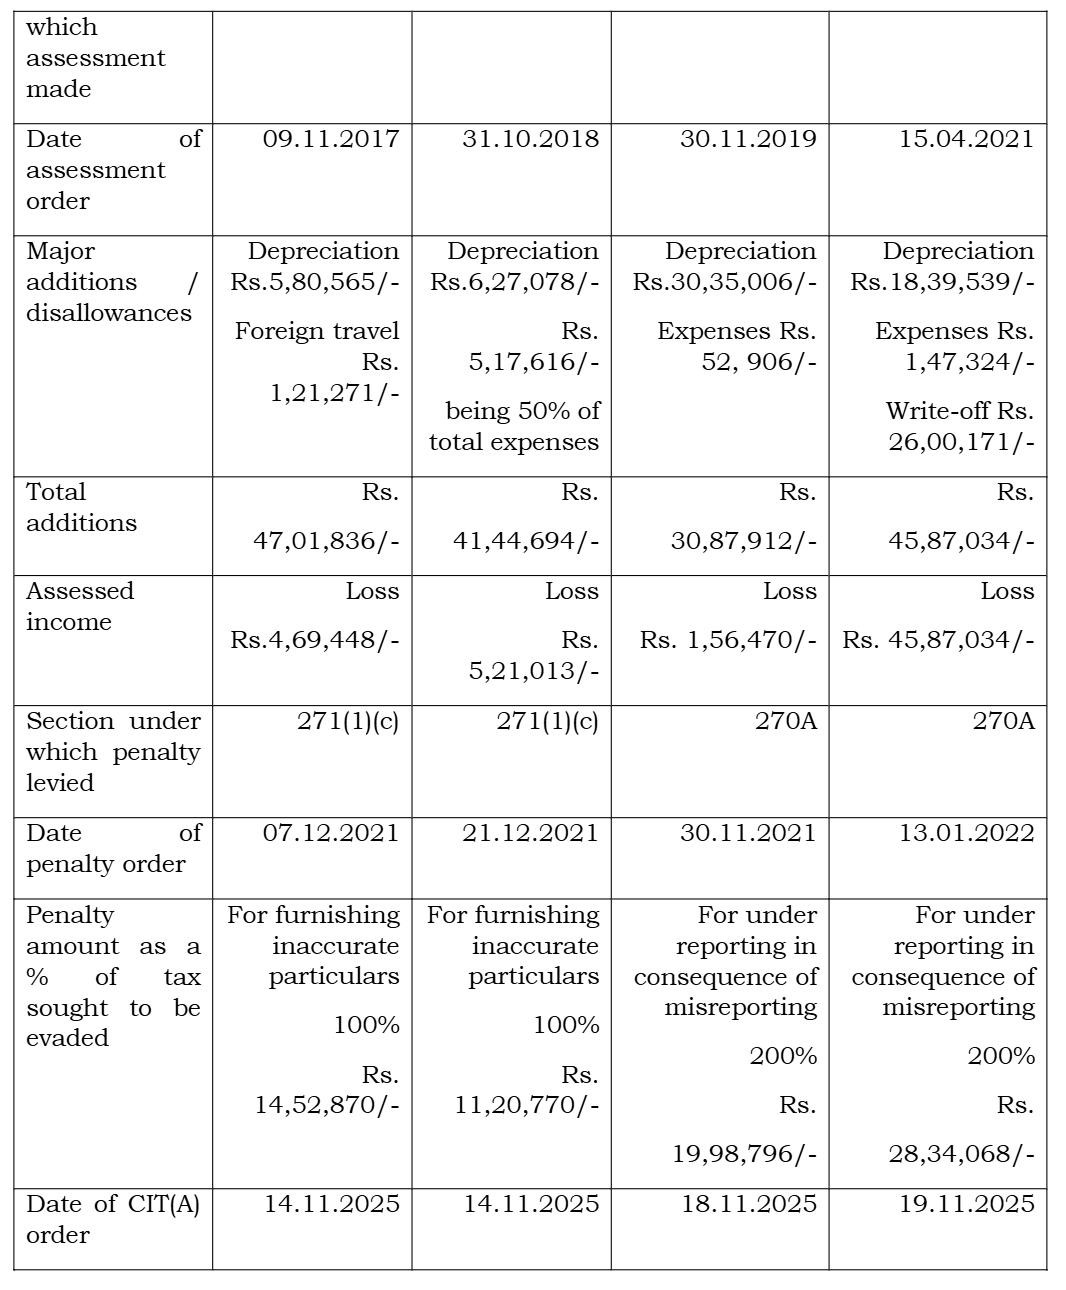
3. Despite the above position, the assessee claimed depreciation on plant and machinery and also claimed various expenses such as travelling expenses, legal and professional expenses and other administrative expenses in the profit and loss account. The explanation of the assessee before the Assessing Officer was that the assets were “kept ready for use” and therefore depreciation was allowable on the principle of passive use. It was further submitted that the expenses were incurred in the normal course of business. The Assessing Officer, however, rejected the explanation of the assessee on the ground that the assessee was not in possession of any assets and had not carried out any business activity during the relevant years. It was held that there was no question of assets being put to use, even passively, and therefore the claim of depreciation was not allowable. Similarly, other expenses were disallowed on the ground that the assessee failed to establish that the same were incurred wholly and exclusively for the purposes of business. In some years, partial disallowance of expenses was made, whereas in later years, entire expenses were disallowed. In A.Y. 2018–19, even the claim of write-off was disallowed for want of supporting evidence.
4. Consequent to the above disallowances, the Assessing Officer initiated penalty proceedings. For A.Ys. 2015–16 and 2016–17, penalty was initiated under section 271(1)(c) for furnishing inaccurate particulars of income. For A.Ys. 2017–18 and 2018–19, penalty was initiated under section 270A on the ground of under-reporting of income in c