Back


2025 Supreme(Online)(Mad) 61994
IN THE HIGH COURT OF JUDICATURE AT MADRAS
C.SARAVANAN, J
D. Tamil Selvi – Appellant
Versus
MJR Hospitality and Services Apartments – Respondent
W.P. (MD) No. 30938 | W.P. (MD) No. 5328
For the Appellants/Petitioners:
Notices under the old tax regime are deemed valid under new provisions if compliant with updated procedures; lack of necessary authority sanction voids reassessment actions.
Headnote:(A) Income Tax Act, 1961 - Sections 148, 149, 151, and 271AAC(1) - Taxation and Other Laws (Relaxation and Amendment of Certain Provisions) Act, 2020 - Assessment orders challenged for 2016-2019 - Notices issued under the old regime deemed show-cause notices under Section 148A(b) post-amendment - Requirement for prior approval from higher authority in new regime specified under Section 151 - Limitation period clarified for valid issuance of reassessment notices. (Paras 1-30)
(B) Legal Fiction and Compliance - Legal fiction created by court ensures notices issued under old regime must be treated as valid under new provisions; delays in communication of information and approvals impact timeline for reassessment. (Paras 8-10, 114)
(C) Authority Jurisdiction - Non-compliance with sanction requirement specified under Section 151 renders reassessment notices and orders invalid. (Paras 26-30)
Facts of the case:
The petitioners challenged assessment orders for assessment years from 2016 to 2019 based on notices issued within the extended timelines during the transition period of tax reforms originating from amendments made in the Income Tax Act, 1961. The assessment orders were set aside due to lack of required sanction from specified authorities in multiple instances.
Findings of Court:
Court held that notices issued beyond prescribed time limits under the new regime are invalid unless appropriate sanctions are obtained, thereby reaffirming compliance with the updated procedural requirements following the amendments.
Issues: The court addressed whether the notices were still valid under the old regime after amendments came into effect and the jurisdiction of assessing officers concerning sanction requirements for the reassessment process.
Ratio Decidendi: The court determined that omissions regarding necessary authority sanctions violated jurisdictional mandates, and failure to comply with limitation timelines rendered the assessments void. Furthermore, it emphasized the necessity for compliance with the newly established procedures regarding reassessment notices.
Result: The assessment orders and penalty notices were set aside and the cases were remitted to the Assessing Officer for fresh orders.
| Table of Content |
|---|
| 1. challenge to assessment orders based on amended provisions (Para 1 , 2) |
| 2. supreme court directive on reassessment notices and show-cause procedures (Para 3 , 4 , 5) |
| 3. confusion due to the transition to new income tax provisions (Para 6 , 7 , 8) |
| 4. deemed notices and provisions retroactivity explained (Para 9 , 10 , 11) |
| 5. legal fiction allows procedural compliance under new provisions (Para 12 , 13) |
| 6. clarification of timelines for reassessment under new and old regimes (Para 14 , 15 , 16 , 17 , 18) |
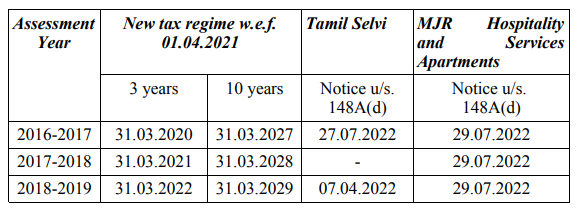
| 7. limitations under new and old regime per assessment years (Para 19 , 20 , 21) |
| 8. authority requirements for issuing assessments under various timelines (Para 22 , 23 , 24 , 25) |
| 9. consequences of lacking proper authority in reassessment notices (Para 28 , 29) |
| 10. final order set aside and remittal of cases for fresh determination (Para 30) |
C.SARAVANAN, J.
By this common order, all six writ petitions are being disposed of. In these writ petitions, the two petitioners are challenging the respective assessment orders passed on the following dates for the corresponding assessment years.
| Assessment Year | D.Tamil Selvi | MJR Hospitality and Services Apartments | ||||
| W.P. (MD) No. | Assessment Order Date | Penalty Notice u/s 271AAC(1) | W.P. (MD) No. | Assessment Order Date | Penalty Notice u/s 271AAC(1)/ 271(1)(c) | |
| 2016 - 2017 | 30938/24 | 26.05.2023 | 20.12.2023 | 5328/25 | 31.03.2023 | 31.03.2023 |
| 2018 - 2019 | 30939/24 | 21.03.2024 | 29.03.2024 | 5329/25 | 31.03.2023 | 31.03.2023 |
| 2017 - 2018 | 30940/24 | 29.03.2022 | 21.03.2024 | 5330/25 | 31.03.2023 | 31.03.2023 |
2. These notices were issued under the old regime as it stood prior to 31.03.2021. However, a new provision came into force thereafter with effect from 01.04.2021. Following the introduction of the new regime, effective from 01.04.2021, there were large-scale challenges to proceedings initiated under the old regime, in the light of the amendments made to the provisions of the Income Tax Act, 1961 .
3. In this context, the Hon'ble Supreme Court passed an order in Union of India and Others vs.Ashish Agarwal, (2023) 1 SCC 617 , on 04.05.2022. The relevant portion of the said decision is extracted below:-
''28. In view of the above and for the reasons stated above, the present appeals are allowed in part. The impugned common judgments and orders [Ashok Kumar Agarwal v. Union of India, 2021 SCC OnLine All 799] passed by the High Court of Judicature at Allahabad in WT No. 524 of 2021 and other allied tax appeals/petitions, is/are hereby modified and substituted as under:
28.1. The impugned Section 148 notices issued to the respective assessees which were issued under unamended of the IT Act, which were the subject-matter of writ petitions before the various respective High Courts shall be deemed to have been issued under -A of the IT Act as substituted by the Finance Act, 2021 and construed or treated to be show-cause notices in terms of -A(b). The assessing officer shall, within thirty days from today provide to the respective assessees information and material relied upon by the Revenue, so that the assessees can reply to the show-cause notices within two weeks thereafter.
28.2. The requirement of conducting any enquiry, if required, with the prior approval of specified authority under Section 148 -A(a) is hereby dispensed with as a one-time measure vis-à-vis those notices which have been issued under of the unamended Act from 1-4-2021 till date, including those which have been quashed by the High Courts.
28.3. Even otherwise as observed hereinabove holding any enquiry with the prior approval of specified authority is not mandatory but it is for the assessing officers concerned to hold any enquiry, if required.
28.4. The assessing officers shall thereafter pass orders in terms of Section 148 -A(d) in respect of each of the assessees concerned; Thereafter after following the procedure as required under -A may issue notice under (as substituted).
28.5. All defences which may be available to the assessees including those available under