Back


2025 Supreme(Kar) 846
IN THE HIGH COURT OF KARNATAKA AT BENGALURU
V KAMESWAR RAO, T.M.NADAF, JJ.
Mr. Deepak Raheja - Appellant
Versus
Union Of India - Respondent
WA NO. 478 of 2024
Decided on : 19-05-2025
Advocate Appeared:
For the Appellant :SRI. AJESH KUMAR S, ADVOCATE
For the Respondent:SMT. ANASUYA DEVI K S, SRI. K N PHANINDRA, SMT. KRUTIKA RAGHAVAN, SRI. PRASHANTH N HEGDE, SRI. VAKITI VINEETH REDDY, ADVOCATE FOR SMT. APARNA MAHESH HIREMATH, ADVOCATE, SRI. BHAIRAV KUTTAIAH, ADVOCATE
Judicial review of banking decisions is restricted; lenders may assign loans classified as stressed without borrower consent, as upheld by the Reserve Bank of India guidelines.
Headnote:(A) Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002 - Judicial Review of Banker's Decisions - The court dismissed the intra-court appeal against assignment of loans as the account was classified as stressed (SMA-1), holding lenders may assign stressed loans without prior notification to the borrower. The learned Single Judge noted the prudence in banking decisions and the limited scope of judicial review in such matters (Paras 16-17, 10).
(B) Principles of Natural Justice - No violation occurred as the account was stressed, justifying the assignment. The court determined that the appellant's legal arguments did not meet statutory prerequisites as per RBI's Master Circulars, thus validating the decisions made (Para 10).
(C) Banking Regulation - Lenders have discretion under RBI guidelines to classify and assign loans without mandatory notice as per evolving financial distress parameters, reinforcing the autonomy of banks in assessing borrower accounts (Paras 12-14).
Facts of the case:
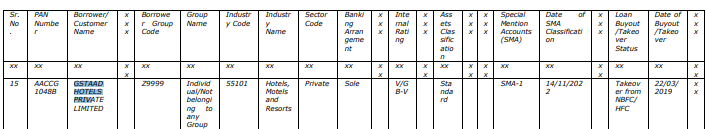
The appellant, engaged in hospitality, challenged the assignment of its loans due to claimed non-notification of account status. The loan account, amounting to INR 450 Crores and revolving credit of INR 50 Crores, faced issues post-COVID-19 lockdowns. The account was classified as SMA-1 as of 14.11.2022.
Findings of Court:
The assignment and subsequent actions were found compliant with banking regulations and acknowledged the lenders' rights to assess and assign (Paras 16-17).
Issues: The primary questions revolved around the legality and notification related to the assignment of the loan account.
Ratio Decidendi: Assignment of loan does not require prior consent of the borrower, especially when the account is classified as stressed as per RBI norms, reinforcing the lenders' prerogative in managing financial assets (Paras 76-78).
Result: Appeal dismissed.
| Table of Content |
|---|
| 1. background of the banking dispute. (Para 2 , 3 , 4) |
| 2. appellant's claims against loan reassignment. (Para 5 , 6 , 7) |
| 3. insights into legal frameworks guiding loan assignments. (Para 8 , 10 , 11) |
| 4. judicial limitations on banking decisions. (Para 12 , 13) |
| 5. assessing statutory compliance in loan assignments. (Para 14 , 15 , 16) |
| 6. claims of appellant regarding eligibility under eclgs. (Para 19 , 20 , 21 , 22 , 23 , 24 , 25 , 26) |
| 7. legal implications of account classification as npa/sma. (Para 28 , 29 , 30 , 31 , 32 , 33) |
| 8. allegations of improper assignment of loan. (Para 36 , 37 , 39 , 40 , 41 , 42) |
| 9. disputes regarding the financial status of the appellant. (Para 46 , 47 , 48 , 49 , 51) |
| 10. arguments of respondent regarding assignment legality. (Para 56 , 57 , 58 , 59 , 60) |
| 11. defense of respondent regarding assignment compliance. (Para 66 , 67 , 68 , 69 , 70) |
| 12. conclusion on the writ appeal. (Para 73 , 74) |
| 13. court's analysis and final decision. (Para 75 , 76 , 78) |
JUDGMENT :
V. KAMESWAR RAO, J.
This intra-court appeal has been filed by the appellants Sri. Deepak Raheja and Smt. Anita Raheja as Directors of Suspended Board of GSTAAD Hotels Pvt. Ltd. and GSTAAD Hotels Pvt. Ltd., challenging the order dated 28.02.2024 passed by the learned Single Judge in WP No.6037/2023, whereby the learned Single Judge has dismissed the writ petition filed by GSTAAD Hotels Pvt. Ltd., by stating in paragraphs No.16 and 17 as under:
“16. It would become germane to notice the judgment of a coordinate Bench in the case of M/S NITESH RESIDENCY HOTELS PRIVATE LIMITED v. UNION OF INDIA [W.P.No.2004 of 2022 decided on 8-08-2022] in answer to two submissions one all the respondents not being a State under Article 12 of the Constitution and other being the concept of Emergency Credit Loan Guarantee Scheme and banker's prerogative. The coordinate Bench has held as follows:
"E. AS TO EMERGENCY CREDIT LOAN GUARANTEE SCHEME AND BANKER'S PREROGATIVE:
(i) The ECLG scheme promulgated by the Central Government which the petitioner's counsel heavily banked upon in support of his case, at its guideline 18 (xiv) imposes an obligation on the lender bank to secure its interest by taking all reasonable measures. The same reads:
"The payment of guarantee claim by the Trustee Company to the lending institution does not in any way take away the responsibility of the lending institution to recover the entire outstanding amount of the credit from the borrower. The lending institution shall exercise all the necessary precautions and maintain its recourse to the borrower for entire amount of credit facility owed by it and initiate all necessary actions for recovery of the outstanding amount, including such action as may be advised by the Trustee Company."
When the lender Banks in given facts & circumstances of the case take a decision as dictated by the prudence, for abruptly recalling the credit facilities, it is not for the courts to sit in appeal over their wisdom. Writ Courts neither have means nor the expertise to re-evaluate the "prudential decisions" of the Banks that are made in the ordinary course of their commercial transactions with accumulated wisdom in the trade.
(ii) After all, the scope of judicial review of 'Bankers Decisions' is too restrictive, as observed by a Division Bench of this Court in MANNE GURUPRASAD vs. M/S.PAVAMAN ISPAT PVT. LTD 10; paragraphs III (iii) &
(iv) of the said decision read as under:
"(iii) In matters between the Banker & borrower, a Writ Court has no much say except in two situations: where there is a statutory violation on the part of the Bank/financial institution, or where the Bank acts unfairly/unreasonably; Courts exercising constitutional jurisdiction u/A 226 do not sit as Appellate Authorities over the acts & deeds of the Bank and seek to correct them; even the doctrine of fairness/reasonableness does not convert the Writ Courts into appellate authorities over administrative decisions concerning the Banking busin