Back


2025 Supreme(Del) 495
IN THE HIGH COURT OF DELHI AT NEW DELHI
PRATHIBA M. SINGH, SHAIL JAIN, JJ.
Kurlon Retail Limited - Appellant
Vs.
Sales Tax Officer & Ors. - Respondent
W.P.(C) 13121 Of 2025, CM APPL. 53682 Of 2025 & CM APPL. 53683 Of 2025
Decided On : 28-08-2025
Advocate Appeared:
For the Appellant : Mr. Manish Mishra, Ms. Joybrata Misra and Mr. Sameer Samal, Advs.
For the Respondent: Mr. Sumit K. Batra, Adv.
Important Points
Subject
Taxation - Goods and Services Tax
Act Referred
Headnote
(B) Procedure for Adjudication - The issuance of show cause notices and related orders must provide the affected parties an opportunity to be heard; orders passed without hearing cannot stand. (Paras 10, 12)
Facts of the case:
The appellant challenges the impugned order and notifications levying demand of substantial amounts under GST for the financial year 2019-20 arising from the issuance of show cause notices not properly communicated to it.
Findings of Court:
The demand orders against the petitioner were set aside due to lack of opportunity for response and proper procedure as per judicial precedents, alongside ongoing challenges in parallel notifications.
Issues: The court focused on the validity of notifications, proper counsel procedures, and the implications on ongoing demand orders.
Ratio Decidendi: The court ruled that procedural due process must be observed in adjudication, emphasizing the requirement for parties to receive fair notice and opportunity to respond before decisions are finalized.
Result: The petitions are disposed of; the impugned orders are set aside, granting the petitioner time to respond to the show cause notices.
JUDGMENT :
Prathiba M. Singh, J.
1. This hearing has been done through hybrid mode.
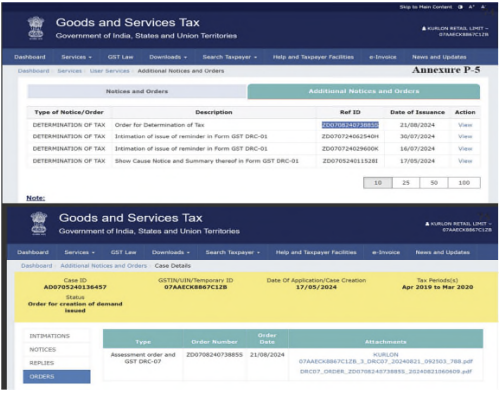
2. The present petition has been filed, inter alia, challenging the impugned order dated 21st August, 2024 passed in respect of Financial Year 2019-20 by the office of Sales Tax Officer Class II/ AVATO, Delhi, raising a demand of Rs. 31,58,436/- under the head of ‘net access ITC availed’. The petition also challenges the vires of Notification No. 56/2023-Central Tax dated 28th December,2023 and NotificationNo.56/2023-State Tax dated 7th July, 2024 (hereinafter ‘impugned notifications’).
3. The validity of the impugned notifications was under consideration before this Court in a batch of petitions with the lead petition being W.P.(C) 16499/2023 titled ‘ DJST Traders Pvt. Ltd. vs. Union of India and Ors. ’ In the said batch of petitions, on 22nd April 2025, the parties were heard at length qua the validity of the impugned notifications and accordingly, the following order was passed:
“4. Submissions have been heard in part. The broad challenge to both sets of Notifications is on the ground that the proper procedure was not followed prior to the issuance of the same. In terms of Section 168A, prior recommendation of the GST Council is essential for extending deadlines. In respect of Notification no.9, the recommendation was made prior to the issuance of the same. However, insofar as Notification No. 56/2023 (Central Tax) the challenge is that the extension was granted contrary to the mandate under Section 168A of the Central Goods and Services Tax Act, 2017 and ratification was given subsequent to the issuance of the notification. The notification incorrectly states that it was on the recommendation of the GST Council. Insofar as the Notification No. 56 of 2023 (State Tax) is concerned, the challenge is to the effect that the same was issued on 11th July, 2024 after the expiry of the limitation in terms of the Notification No.13 of 2022 (State Tax).
5. In fact, Notification Nos. 09 and 56 of 2023 (Central Tax) were challenged before various other High Courts. The Allahabad Court has upheld the validity of Notification no.9. The Patna High Court has upheld the validity of Notification no.56. Whereas, the Guwahati High Court has quashed Notification No. 56 of 2023 (Central Tax).
6. The Telangana High Court while not delving into the vires of the assailed notifications, made certain observations in respect of invalidity of Notification No. 56 of 2023 (Central Tax). This judgment of the Telangana High Court is now presently under consideration by the Supreme Court in S.L.P No 4240/2025 titled M/s HCCSEW-MEIL-AAG JV v. Assistant Commissioner of State Tax & Ors. The Supreme Court vide order dated 21st February, 2025, passed the following order in the said case:
“1. The subject matter of challenge before the High Court was to the legality, validity and propriety of the Notification No.13/2022 dated 5-7-2022 & Notification Nos.9 and 56 of 2023 dated 31-3-2023 & 8-12-2023 respectively.
2. However, in the present petition, we are concerned with Notification Nos.9 &56/2023 dated 31-3-2023 respectively.
3. These Notifications have been issued in the purported exercise of power under Section 168 (A) of the Central Goods and Services Tax Act. 2017 (for short, the "GST Act").
4. We have heard Dr. S. Muralidhar, the learned Senior counsel appearing for the petitioner.
5. The issue that falls for the consideration of this Court is whether the time limit for adjudication of show cause notice and passing order under Section 73 of the GST Act and SGST Act (Telangana GST Act) for financial year 2019-2020 could have been extended by issuing the Notifications in question under Section 168 -A of the GST Act.
6. There are many other issues also arising for consideration in this matter.
7. Dr. Muralidhar pointed out that there is a cleavage of opinion amongst different High Courts of the country. 8. Issue notice on the SLP as also on the prayer for interim relief, returnable on 7-3