Back


2026 Supreme(Bom) 381
IN THE HIGH COURT OF JUDICATURE AT BOMBAY
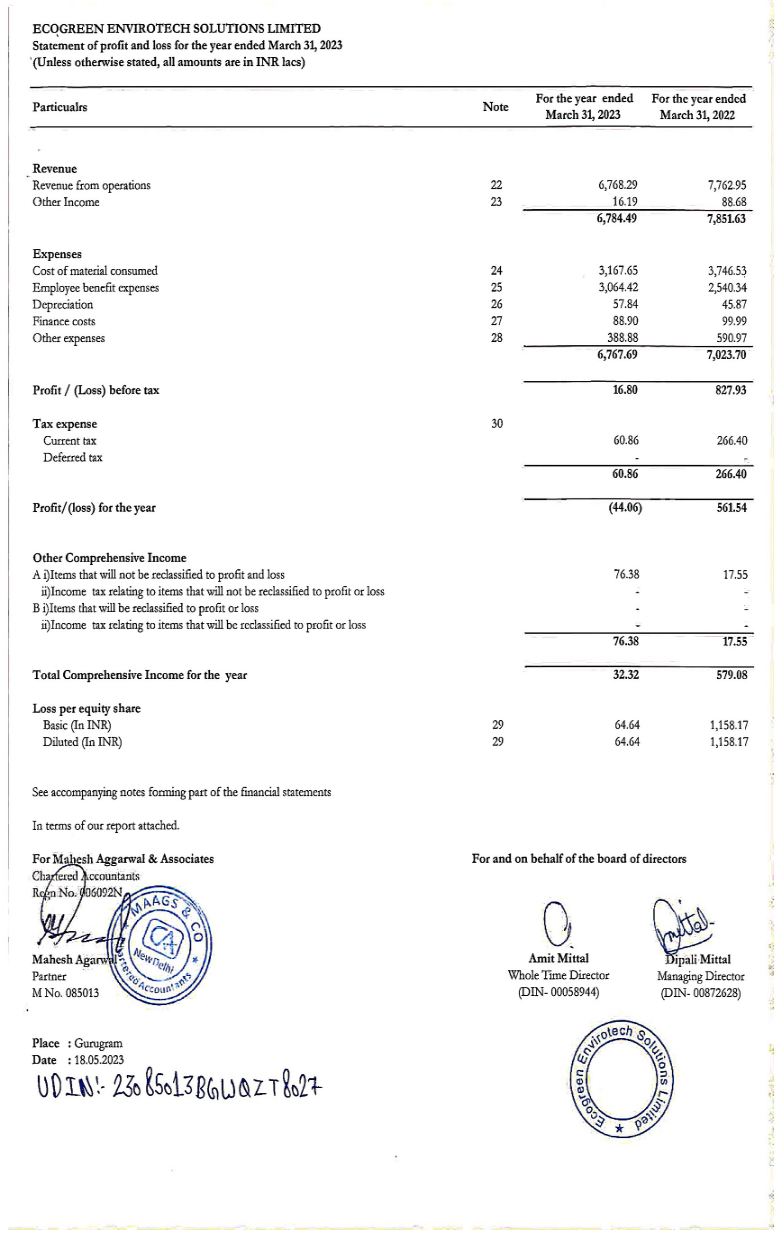
SHREE CHANDRASHEKHAR,C.J., GAUTAM A.ANKHAD, J.
Ecogreen Envirotech Solutions Ltd. – Petitioner
Versus
The Municipal Corporation of Greater Mumbai – Respondent
Writ Petition No.5367 of 2025 Along With Interim Application (Lodging) No.38376 of 2025 Along With Interim Application (Lodging) No.39353 of 2025
Decided On : 13-02-2026
Important Points
Subject
Tenders - Eligibility Criteria
Act Referred
Headnote
(B) Judicial review in tender matters - Limited scope - Courts to defer to tendering authority's interpretation of its terms unless arbitrariness, perversity or malafides shown - No interference if decision-making process fair, transparent and conditions uniformly applied - Author of tender best placed to judge eligibility. (Paras 10,11)
Facts of the case:
Bidder (lead member of joint venture) disqualified in technical bid for tender concerning collection and transportation of solid waste - Financial certificate claimed positive profit after tax for relevant year including OCI, but balance sheet reflected loss - Clarification by Chartered Accountant rejected - 10% earnest money forfeited.
Findings of Court:
Petition lacks merit - No deviation from tender conditions warranted - Uniform formula applied across bidders.
Issues: Whether tender authority must accept Chartered Accountant's certificate incorporating OCI into profit after tax despite balance sheet loss; whether rejection arbitrary given lack of prescribed accounting methodology and differential treatment alleged for other bidder.
Ratio Decidendi: Tender condition uses 'Profit after Tax', not 'Total Comprehensive Income' or OCI - Bidder bound by balance sheet entries - Authority entitled to prescribe and uniformly apply standards without accepting alternative methodologies - Explanation via OCI invites deviation from apparent documents. Result : Writ petition dismissed without costs; interim applications disposed of.
For the Petitioner:Mr. Sharan Jagtiani, Senior Advocate, with Mr. Farhan Khan, Mr. Kaushik Poddar, Mr. Pankaj Uttaradhi and Mr. Ravish Ajay Mishra, Advocates
For the Respondents:Mr. Nikhil Sakhardande, Senior Advocate with Mr. Pralhad Paranjpe and Ms. Oorja Dhond, i/by Ms. Komal R. Punjabi, Advocates, Mr. Vijay Gotarne, Ex. Engineer (SWM) Planning is present in Court, Smt. Lavina Kripalani, Assistant Government Pleader, Mr. Girish Godbole, Senior Advocate with Mr. Siddhartha Puthoor, Mr. Janmesh Vora, Advocates, i/by Mehta & Padamsey.
| Table of Content |
|---|
| 1. eligibility requires positive pat for five fys. (Para 1 , 2 , 3) |
| 2. oci included in pat under ind as. (Para 4) |
| 3. pat from p&l excludes oci uniformly. (Para 5 , 6) |
| 4. balance sheet entries bind; no oci re-interpretation. (Para 7 , 8 , 9) |
| 5. judicial review limited in tender matters. (Para 10) |
| 6. reliance energy inapplicable to bid rejection. (Para 11) |
| 7. petition dismissed upholding tender decision. (Para 12) |
JUDGMENT :
GAUTAM A. ANKHAD, J.
The petitioner challenges its disqualification by the respondent no.1 in the technical bid in respect of Tender at serial no.6 (2025_MCGM_1179484_1) (Group-6) for collection and transportation of municipal solid waste from wards of the Brihanmumbai Municipal Corporation to transfer stations and final disposal sites. The petitioner is the lead member in a Joint Venture comprising C.E. Infra (India) and Aakshya Infra Projects Private Limited, who are arraigned as respondent nos. 5 and 6 respectively in the present proceedings.
2. On 14th May 2025, the respondent no.3 (Deputy Chief Engineer (Solid Waste Management) Planning) invited e-tenders. By a corrigendum dated 25th June 2025, the eligibility condition relating to “Profitability” under section 2C and section 6F was modified, the relevant portions of which read as under:
Section 2 Clause “C” & Section 6 Clause “F”
“Profitability”
Modified as
Profit after Tax as certified by ‘Chartered Accountant’ should be Positive for last five consecutive financial years (2019-20, 2020-21, 2021-22, 2022-23, 2023-24) of the Bidder and parent/subsidiary/SPV for which experience is being claimed.
Instead of
Profit after Tax as certified by ‘Chartered Accountant’ should be Positive for “Any Three Years” out of the last five consecutive financial years of the Bidder and parent/subsidiary/SPV for which experience is being claimed. The profit shall not be negative for the last two consecutive financial years.”
3. The petitioner submitted its bid along with a Financial Certificate dated 3rd July 2025. Upon scrutiny, the respondent no.3 noticed that while the Financial Certificate reflected a positive Profit after Tax of Rs.32.32 lakhs for Financial Year 2022-23, the balance sheet of the petitioner showed a loss of Rs.44.06 lakhs. A clarification was sought on 23rd September 2025. In response, on 24th September 2025, the petitioner’s Chartered Accountant clarified that though the Profit & Loss Account reflected a loss, upon considering the next entry of Other Comprehensive Income (“OCI”) as per Indian Accounting Standards (“Ind AS”), the total comprehensive income was Rs.32.32 lakhs (positive) and therefore the certificate reflected a positive profit after tax. On 17th November 2025, the petitioner’s bid was rejected for inadequate financial capacity and it was informed that 10% of the earnest money deposit will stand forfeited as per the tender conditions. This action is the subject matter of challenge in this petition.
4. Mr. Sharan Jagtiani, the learned senior counsel appearing for the petitioner submits that the tender conditions inter alia requires the bidder to have sufficient financial capacity. The petitioner’s company is profitable for all 5 years and the profit after tax for FY 2022-23 is also positive. The learned senior counsel submits that the petitioner is a subsidiary of a listed company and is required to follow the Ind AS under which certain re-measurement gains/losses on defined benefit obligations are reflected separately as OCI and not in the Profit & Loss Account. Under the Generally Accepted Accounting Principles (“GAAP”), the OCI forms part of the profit/loss computed. According to the learned senior counsel, if OCI is considered, then the petitioner’s Total Comprehensive Income (post tax) is Rs.32.32 lakhs positive. He contends that the authorities ought to accept the Chartered Accountant’s certificate, since the tender condition does not prescribe any specific accounting methodology. He submits that the aggregate profit after tax of the