


 Back


2025 Supreme(Del) 614
IN THE HIGH COURT OF DELHI AT NEW DELHI
PRATHIBA M. SINGH, SHAIL JAIN, JJ.
M/S. V.R. Impex Through Its Proprietor Mr. Vishal – Petitioner
Versus
Commissioner Of Delhi Goods And Services Tax And Anr. – Respondents
W.P.(C) 5264 of 2025 & CM Appl. 23941 of 2025
Decided On : 11-08-2025
For the Petitioner: Mr. Parveen Kumar Gambhir, Adv.
For the Respondents: Ms. Vaishali Gupta, Adv.
Retrospective cancellation of GST registration requires adequate reasoning and cannot be applied mechanically.
Headnote:The petitioner challenged the retrospective cancellation of its GST registration effective 30th August 2019. The court noted several decisions ruling such cancellations impermissible, emphasizing that proper reasoning is essential for retroactive actions. The court held the original order invalid without adequate justification, affirming cancellation only from the notice's date.
| Table of Content |
|---|
| 1. challenge to gst cancellation based on procedural inadequacies. (Para 2 , 3) |
| 2. importance of substantiated reasoning for retrospective actions. (Para 5) |
JUDGMENT :
Prathiba M. Singh, J.
1. This hearing has been done through hybrid mode.
2. The present petition has been filed by the Petitioner challenging the retrospective cancellation of its GST registration with effect from 30th August 2019 vide order for cancellation of registration dated 16th March, 2023.
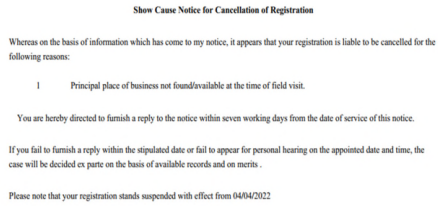
3. A Show Cause Notice dated 4th April, 2022 (hereinafter, ‘SCN’) for cancellation of GST Registration was issued to the Petitioner on the ground that the principal place of business was not found at the time of field visit. However, it is the case of the Petitioner that this SCN did not put to the Petitioner that the GST registration cancellation would be given effect to retrospectively. Relevant portion of the SCN is extracted herein below:
4. Retrospective cancellation of GST Registration in this manner has been held to be impermissible by this Court in various decisions, including in terms of the judgments in ‘Subhana Fashion v. Commissioner Delhi Goods and Service Tax (W.P. (C) 12255/2024)’, “M/S Balaji Industries v. The Principal Commissioner CGST Delhi
5. The relevant portions of the decision in Subhana Fashion (supra) is as under:
“10. It is apparent to note that non-payment of dues for a period of three months is not a prescribed ground for cancelling the petitioner’s GST registration.
11. It is also important to note that the impugned order sets out a tabular statement, which indicates that no amount has been determined as payable by the petitioner. The Central Tax, State Tax, Integrated Tax and Cess payable by the petitioner is reflected as, “0.0”.
12. Apart from the above, the impugned order has also been passed in violation of principles of natural justice. Although the SCN called upon the petitioner to appear for a personal hearing at the appointed date and time, no such date or time was indicated. Thus, in effect the petitioner was not afforded an opportunity to be heard.
13. In view of the above, we set aside the impugned order. The respondents are directed to restore the petitioner’s GST registration forthwith.”
6. The relevant part of the judgment in “M/s Balaji Industries (Vipin Kumar) (Supra) is as under:
“8. It is apparent from the above that the reasons as set out in the impugned order were not the reasons as set out in the SCN. Further, the SCN also did not propose cancellation of the petitioner’s GST registration with retrospective effect from 11.09.2017.
9. The petitioner filed an appeal against the impugned order cancelling its registration. However, the same was rejected by the appellate authority by the order dated 14.05.2024 on the ground that the petitioner’s appeal was barred by limitation.
10. As noted above, the reason for which the petitioner’s GST registration was cancelled was not reflected in the SCN. Although, the petitioner claims that it did not receive the SCN, it is apparent that even if it had, the same provided it no opportunity to respond to the reasons as set out in the impugned order cancelling its GST registration.
11. As noted above, the petitioner is not aggrieved by the cancellation of its GST registration as it had closed down its business. The petitioner is, essentially, aggrieved by cancelling of its GST registration with retrospective effect.
12. The present petition was listed on 29.08.2024 and the learned counsel appearing for the respondents sought time to take instructions.
13. The learned counsel for the respondents states that the respondents have no objection if the cancellation of the petitioner’s GST registration is made operative with effect from the date of the SCN, that is, with effect from 24.05.2022.
14. In view of above, the present petit







