Back





2026 Supreme(Raj) 709
HIGH COURT OF JUDICATURE FOR RAJASTHAN BENCH AT JAIPUR
ASHUTOSH KUMAR, J.
Munni Devi Sharma wife of Ram Avtar Sharma - Appellant
Versus
Suresh Kumar Son of Mangu Ram - Respondent
S.B. Civil Miscellaneous Appeal No. 538 of 2013
Decided On : 06-01-2026
For the Appellant : Mr. Vinay Mathur, Adv.
For the Respondent: Mr. Virendra Agarwal, Adv. With Ms. Anjali Assat, Adv.
Income tax returns are statutory documents usable for determining a deceased's annual income. Furthermore, if a deceased is categorized in the 40-50 age group for applying a multiplier of 13, future prospects must be awarded at 30% and cannot be reduced to 15%.
Headnote:(A) Determination of income - Reliance on income tax returns - Statutory document on which reliance may be placed to determine the annual income of the deceased (Para 10).
(B) Quantum of Compensation - Future prospects - Deceased in age group 40 to 50 years - Where a multiplier of 13 is applied based on the age group, the addition towards future prospects should be 30% - Granting only 15% future prospects while maintaining the multiplier for the 40-50 age group is an error and lacks justification (Para 9).
Facts of the case:
Claimants sought compensation for the death of a person in a motor accident. The deceased was aged 50 years and 3 months. The Tribunal applied a multiplier of 13 and considered the deceased in the 40-50 age group. The High Court maintained the multiplier of 13 but reduced the future prospects from 30% to 15% on the ground that the deceased was slightly over 50 years.
Findings of Court:
The determination of income can be based on income tax returns as they are statutory documents. Regarding future prospects, once the age group is considered as 40 to 50 years and a multiplier of 13 is adopted, future prospects must be granted at 30% and cannot be reduced to 15% without justification.
Issues: Whether income tax returns are authoritative for determining the annual income of the deceased and whether future prospects can be reduced to 15% when the multiplier of 13 is applied for a deceased in the 40-50 age group.
Ratio Decidendi: Income tax returns are statutory documents admissible for calculating income. For future prospects, the primary consideration is the age group; if the deceased is treated as being in the 40-50 age group to justify a multiplier of 13, a 30% addition for future prospects is mandatory as per Constitutional Bench guidelines.
Result: Compensation enhanced by restoring future prospects to 30%.
Legal Category Hierarchy
-
tort
-
motor accident compensation
-
assessment of compensation
- future prospects
- multiplier
-
assessment of compensation
-
motor accident compensation
-
practice and procedure
-
appeal
- high court
-
appeal
-
evidence
- income tax return
ORDER :
ASHUTOSH KUMAR, J.
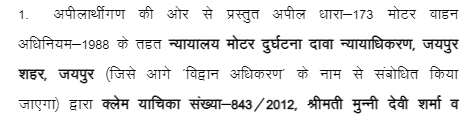
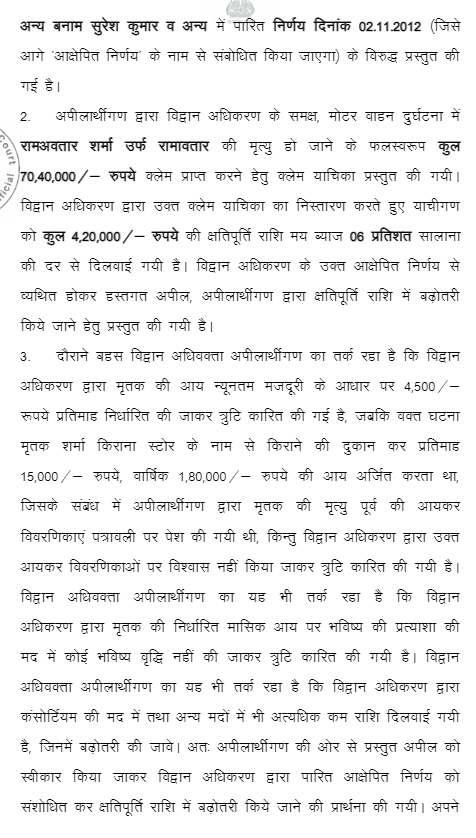
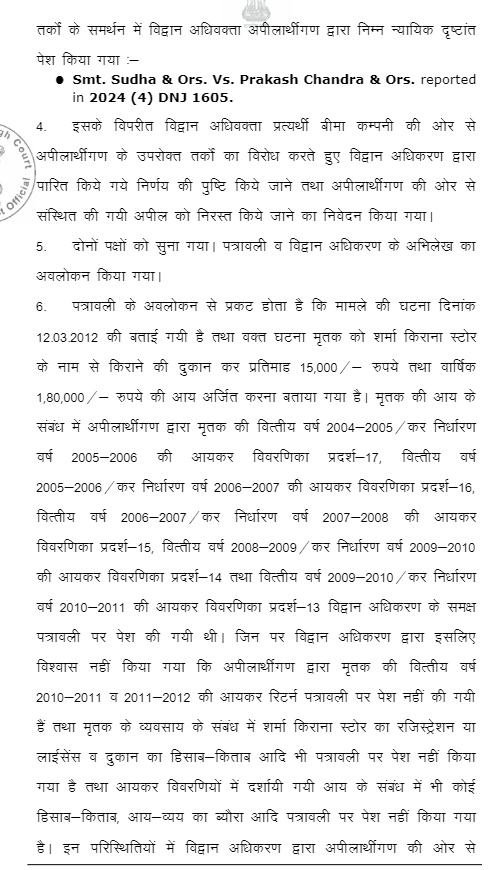
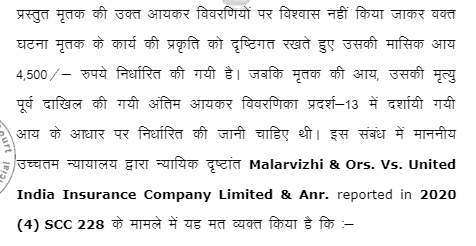
"10. …We are in agreement with the High Court that the determination must proceed on the basis of the income tax return, where available. The income tax return is a statutory document on which reliance may be placed to determine the annual income of the deceased.”
"9. The Tribunal, by recording a finding that the deceased was in the age group of 40 to 50 years, applied the multiplier of 13 while calculating the compensation. The High Court, curiously while maintaining the multiplier of 13 as per the judgment of this Court in compensation only on the ground that the deceased was aged 50 years 3 months on the date of the accident, as such the compensation is to be calculated on account of loss of dependency by granting future prospects at 15% but not 30%. So far as the application of multiplier of 13 by the Tribunal is concerned, the High Court has not interfered with the same. When the age of the deceased was considered in the group of 40 to 50 years, we are of the view that the High Court has committed error in granting only 15% towards future prospects instead of 30%. As per the judgments of this Court, primarily the age group is to be considered. Considering the age group as 40 to 50 years, when the multiplier of 13 is maintained by the High Court, there is no reason or justification for reducing the compensation by granting 15% towards future prospects. Though the learned counsel appearing for Respondent 1 Insurance Company has submitted that the compensation towards future prospects was awarded as per the Constitution Bench judgment of this Court in National Insurance Co. Ltd. v. Pranay Sethi3 but at the same time it is to be noticed that in the very same judgment in para 59.3, while considering the grant of future prospects, this Court has specifically said that the addition should be 30% if the age of the deceased was in the age group of 40 to 50 years. For application of multiplier, the High Court has also accepted the age group of the deceased between 40 and 50 years. In that view of the matter, there is no reason for reducing the compensation by granting future prospects at 15% only."