| 44[FORM VII
[See Rule 47A (4) (e) under Part 1 ] Special Bond to be executed for the Extra Neutral Alcohol (Neutral Spirit)/Grape Spirit/Malt Spirit without Payment of Duty.
Know all men by these presents I/We ..................................................................................................... (herein after called the bounder/s) and Sri ....................................... (herein after called the surety) are bounden to the Governor of Kerala (hereinafter called the Government) in a sum of Rs.............................(Rupees...............................) to be paid to the said Government for which pa
S.RECEIVERS
S.PIPES
S.FORM D-1 | FORM D-1
REGISTER OF WASH BACKS IN THE .........................DISTILLERY | | No Wash back. | | Table of dimensions |
| | Conse Depth
cutive number | | FORM D-3
Distiller’s Account of Materials Used | | Materials | Wash | Weak spirits issued for | | | | S.FORM D-3 (a) | FORM D3- (a)
Distillers Declaration of wash | | I hereby declare that the gravity of the wash made this day in the ....................Distillery is, according to the prescribed Saccharometer corrected for temperature, as shown below, that the total quantity is ............litres and that the quantity of materials used is as follows:- | S.FORM D-3 (b) | FORM D - 3(b)
Statement of wash made and spirit obtained therefrom in the .................
Distillery for the month of................. | | Date when set up | Number of wash back | Materials used | Litres
| S.FORM D-3 (c) | FORM D 3 (c)
Statement showing the quantities and price of
raw materials used in distillation at the ..............
distillery for the month of............... | | Raw materials | Quintal | Rate | Value | S.FORM D 5 | FORM D 5
Distiller’s /Warehouse-keeper’s Account of Warehouse Transactions | | | FORM D 6 (a) | | Note Book of gauges and proofs at the.......................................................................... | Distillery
------------------------
Warehouse | | Vat or receiver number | Dip
----------------
Centimeter
| | S.FORM D 8 | FORM D8 | | Register of spirits received into and issued from each Vat in The .............................. | Distillery
--------------------
Warehouse | | Vat No. |
| | FORM D 8 (a) | | Statement showing the particulars of blending and reducing operations in the | Distillery
--------------------------
Warehouse | | during the quarter ended........................ |
| | | | | FORM D 9 | | Compilation Register of spirits stored,etc., in terms of proof strength in the warehouse of the .................. | Distillery
-------------------
Warehouse | |
| | S.FORM D-9 (a) | FORM D 9 (a) | | Extract from the Compilation Register of spirits stored,etc., in terms of proof
Strength in the ......................... | Distillery
Warehouse | |
| S.FORM D 10 | FORM D 10 | | Compilation register of the weekly abstracts of the register of spirits (in terms of proof strength)
in hand stored issued etc., for the month of ..................................in the.......................distillery/warehouse |
| | | | | S.FORM D 11 | FORM D 11
Statement showing the result of stock taking (terms of proof strength) in the ............distillery/warehouse
for the quarter ended............................................date of stock taking. |
| | | | Received | Issued | | | | S.FORM D 11A | FORM D 11A
Register showing the result of the Quarterly Stock taking (in proof litres)
in the .............................Distillery/Warehouse |
| | | Receipts | Issues | <
| S.FORM D 12 | FORM D 12 | | Chalan for payment of duty on spirits to be
issued from the .................... | Distillery
Warehouse |
| S.FORM D 13 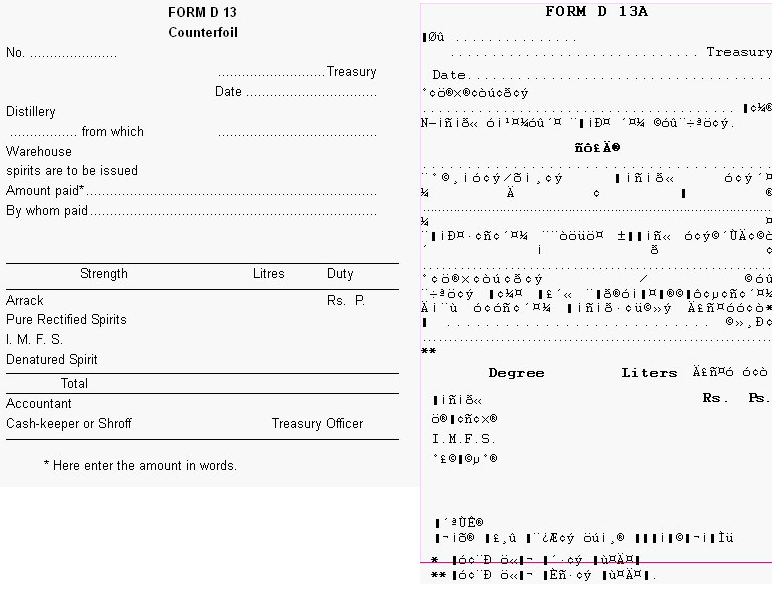
S.FORM D 13B | FORM D 13 B | | No.......... | ......................Treasury
Date......................... | | From | | | | | | FORM D 14 | | Application for issue of permits for transport of spirits | | To | | | The Officer-in-charge of .....Distillery/ Warehouse | | | |
S.FORM D 16 | FORM D 16
Register or permits issued from the .....................Distillery /Warehouse |
| | Application | Permit | Quantity issued | | <
| S.FORM D 17 | FORM D 17
Extract from the Register of permits issued from the .........................Distillery /Warehouse on the |
| | Application | Permit | Quantity issued | | | S.FORM D 18 FORM D 18
(See Rule 77 of Part II) Register of issues of country spirits and of the duty paid thereon in the .........Distillery /Warehouse
S.FORM D 18A | FORM D 18A | | Extract from the register of issues of country spirits and of the duty paid thereon in the month of..................................................from the..............................Distillery /Warehouse | | | | Range | Quantity of country spirits issued | | FORM D 19
Register of issues of Foreign, Denatured, etc, spirits and of the duty paid thereon in the...........
Distillery /Warehouse | Name of Vendor ..................................................
Whether consigned under bond ..................................... |
| | Pure rectified spirits | | FORM D 19A
Extract from the register of issues of Indian made Foreign Spirits Denatured, etc., spirits and of the Duty paid thereon in
the quarter ended.........................................from the .......................Distillery /Warehouse |
| | | Pure rectified
spirits | | | | | S.FORM D 20 | FORM D 20
Comparative Statement of Consumption of Country Spirit in the Several Arrack Vend Areas....................................for the month of .................20................. |
| | | Particulars of spirits purchased from
Distilleries, Warehouses and Excise Depots | | FORM D 21 A | | Diary of the Officer-in-charge of the.................................................Distillery/ Warehouse |
| | Date | Serial number
of transaction | Hour | | S.FORM D 21A_1 | EXCISE DEPARTMENT OF KERALA STATE
FORM D 21 A | | Diary of the officer of the ....................................................... | Distillery
---------------------
Warehouse | for | | the week ended ...............................................................................................
| S.FORM D 24 | FORM D 24
Register of Bonds executed by Distillers /Warehouse-keepers and other for the export and transport of spirits from...............................................................Distillery/Warehouse |
| | | | | | FORM D 25
Register showing the particulars of spirits removed on account of public service From the ..........................................
Distillery / Warehouse......................................during the year. |
| | | | | S.FORM D 26 | FORM D 26 | | | FORM D 26 | | No ......... | Verification Certificate | | S.FORM D 27 | FORM D 27 | | (See Rule 67 of Part II) | | Register of issues of spirits the duty on which has been paid in advance
| | Balance of advance brought forward
Amount paid in advance as per. | Da
| S.FORM D 29 | FORM D 29 | | Register of persons employed by licensed. Distiller/Warehouse-keeper | | | at the ................. | Distillery
-------------------
Warehouse | | S.FORM D 31 | FORM D 31
Register of verification of consignments of liquor received..........................at the.......................Distillery/Warehouse |
| | Permit | Date of | Cask | As
| S.FORM D 31 (b) | FORM D 31 (b)
ULLAGE TABLES FOR LYING CYLINDRICAL STEEL DRUMS |
| | Quotient | Equivalent | Quotient | Equivalent | Quotient | | .305 | .258165 | .353 | .315566 | .401 | .374778 | | | | S.FORM D 31 (b)_2
| | D 31 (b) - Contd.) |
| | Quotient | Equivalent | Quotient | Equivalent | | D 31 (b) - Contd.) |
| | Quotient | Equivalent | Quotient | Equivalent | Quotient |
| S.FORM D 31 (b)_4
| | D 31 (c) - Contd.) |
| | Quotient | Equivalent | Quotient | Equivalent | <
| S.FORM D 32 | FORM D 32 | | Memorandum of overtime fees payable to the under-mentioned Officers
of the ......................................Distillery /Warehouse for the
month of ...................................20........................... | | Name of Officer | Designation | <
S.FORM D 33 | FORM D 33
See Rule 76 of Part II
Register of denaturing operations in the ............................Distillery | | | Denaturing materials | Spirits denatured | | | Date | Description
| S.FORM D 34 FORM D-34
Hypothecation deed to be executed by distillers and Warehouse-keepers This instrument made the. ....... ... .......day of .................. ........20 ............. between ..................................................... (hereinafter called the mortgagors) of the one part and the Governor of Kerala (hereinafter called the mortgagee) of the other part. Whereas by licences or Instruments in writing under the hand of the Commissioner of Excise and bearing date the ......... ...... day of .......................... 20......................... the said Commissioner being duly authorised under the provision of the Abkari Act, 1 of 1077 appointed, the mortgagors to manufacture country spirits in the ............... Taluk and to supply the same for consumption in any of the contract supply area ..................... from the............... day
S.FORM D 35 | FORM D 35
See Rule 7(2) of Part II
Distiller’s notice to set up wash at night | | I hereby give notice that on the ......... day of ........ 20 ..... at ........ O’clock 1 intend to begin set up of wash in the wash room and expect to present declaration for same at.................O’clock. | | ..........................Dated this the ............................day of ................20......... | | |
S.1 Explanatory Note | (This does not form part of the notification, but is intended to indicate its general purport.) In the Abkari policy for the year 2023-2024, announced vide G. O. (Ms.) No. 79/2023/Taxes, dated 27th July, 2023, Government have inter alia decided to enhance the fine to Rupees 50,000 (Rupees Fifty Thousand only) in case of violation of licence conditions by the holder of license under the Kerala Distillery and Warehouse Rules, 1968. In order to carry out the above decision, amendments have to be made in the Kerala Distillery and Warehouse Rules, 1968.
The notification is intended to achieve the above object. |
S.Kerala Distillery and Warehouse (Amendment) Rules, 2023 All Amendments Incorporated at Appropriate place GOVERNMENT OF KERALA | Taxes (G) Department | NOTIFICATION | G. O. (P) No. 147/2023/Taxes. Dated, Thiruvananthapuram, 4th November, 2023
18th Thulam, 1199. S. R. O. No. 1199/2023 In exercise of the powers conferred by Sections 24 and 29 of the Abkari Act, 1 of 1077, the Government of Kerala hereby make the following rules further to amend the Kerala Distillery and Warehouse Rules, 1968 issued by notification under G. O. (Ms.) No. 75/1968/RD dated 1st February, 1968 and published as S.R.O. No. 112/69 in the Kerala Gazette Extraordinary No. 11 dated 18th March, 1969, namely:-- | RULES | | FORM I
(See Rule 4 of Part I)
Licence to Manufacture Spirits in the Distillery | | I, Commissioner of Excise, Kerala State under the provisions of the Rules prescribed for the establishment of distilleries under the Abkari Act 1 of 1077 as subsequently amended, hereby licence you to manufacture spirits in the .............. Distillery from the First day of April upto the last day of March (both days inclusive) subject to the following conditions to be observed by you, the said licensee. | | | S.FORM II FORM II
(See Rule II(b) of Part I)
Licence for the compounding and blending of Indian made foreign liquor and imported
foreign liquor for the purpose of sale. | The Commissioner of Excise, Kerala State under the provisions of the Rules prescribed for the establishment of distilleries under the Abkari Act 1 of 1077 as subsequently amended hereby licence you................................................................................... ......................................................................to compound or blend locally made liquor and imported Foreign Liquor within the premises attached to the ...........................................
S.FORM III FORM III
[See Rule II (d) of Part I]
Licence for the bottling of foreign liquor for the purpose of sale | | The Excise Commissioner, Kerala State under the provisions of the Rules prescribed for the establishment of distilleries under the Abkari Act 1 of 1077 as subsequently amended hereby licence you ................................................. ............................................. to bottle Foreign Liquor for the purpose of sale within the premises attached to the ................... 18(Distillery) from the first day of April.................. to the
S.FORM IV | FORM IV
(See Rule 16 (a) of Part 1)
WAREHOUSE LICENCE
Licence to establish a warehouse for the deposit and keeping of spirits without payment of duty at | | I........... Commissioner of Excise, Kerala State under the provisions of the Rules prescribed for the establishment of distilleries and warehouses under the Abkari Act 1 of 1077 as subsequently amended hereby licence you ........... to establish a warehouse for the deposit and keeping of spirits w
S.FORM IVA | 40[FORM IVA
[See Rule 47A (2) under Part 1] | | Licence for the possession and use of non-duty paid imported/transported Extra-Neutral Alcohol (neutral spirit for alcoholic drinks) Grape Spirit/Malt Spirit in a Bonded Warehouse.
The Commissioner of Excise, Kerala hereby licence you,
....................................................................................................................... to possess and use imported/transported Extra Neutral Alcohol (neutral spirit for alcoholic drinks) Grape Spirit/Malt Spirit on which duty has not been paid to the Government, in your Bonded
S.FORM V FORM V
23[See Rule 51, Part I]
Form of general bond to be executed on the removal of spirits from distilleries for transport without payment of duty. | Know all men by these presents that I/We (......) (hereinafter called the bounden/boundens) and Shri.................. (hereinafter called the surety) are bounden to the Governor of Kerala (hereinafter called the Government) in the sum of Rupees..... to be paid to the Government for which payment. We bind ourselves and our legal representatives | Dated this .........................
S.FORM VI | FORM VI
24[(See Rule 51, PART I)]
Form of special bond to be executed on the removal of spirits from distilleries for transport without payment of duty | | Know all men by these presents that I/We (........... ) (hereinafter called the bounden/boundens) and Shri ......... (hereinafter called the surety) are bounden to the Governor of Kerala (hereinafter called the Government) in the sum of Rs ........... to be paid to the said Government for which payment we bind ourselves and our legal representatives. | Legal Comments "Introduction" - Section II of Kerala Distillery and Warehouse Rules, 1968 addresses definitions and scope related to distilleries, warehouses, and related duties; interpretation is guided by Abkari Act provisions and case law. [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165] "What Section Says" - Section II includes cross-referencing to Rule 55 (wastage allowances) and Rule 27/28 (security and hypothecation) and connects to other rules (e.g., Rule 7 of Kerala Foreign Liquor Rules) to regulate wastage, import, and duty obligations. [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [ASSISTANT COMMISSIONER OF CUSTOMS VS STATE OF KERALA - 2010 0 Supreme(Ker) 881] "Essential ingredients" - Key elements identified in Kerala framework: wastage allowances (R.55; R.11 interplay with R.7(5)); duty payable on rectified/imported liquor; security/hypothecation under Rules 27-28; verification and accounting procedures; attestation by Distillery Officer and Deputy Commissioner; bond/permit regime; and remedies under R.42. [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [ASSISTANT COMMISSIONER OF CUSTOMS VS STATE OF KERALA - 2010 0 Supreme(Ker) 881], [State of Kerala VS K. S. Distillery - 2010 0 Supreme(Ker) 256], [United Spirits Ltd. VS State of Kerala - 2015 0 Supreme(Ker) 1684] "Scope of Section" - Section II and associated Rules cover import, production, storage, and removal of excisable spirits, including imported spirits for compounding/blending and bottling; permissible wastage allowances apply to imported and domestically produced liquor under specified rules; jurisdiction spans distilleries, warehouses, depots, and KSBC monopolies when applicable. [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435] "Punishment for Section" - The material sources focus on penalties for non-compliance (e.g., improper wastage accounting, non-payment of duties, non-compliance with bonds) and may include penalties via compounding or court-imposed remedies; specific penalties appear in various cases under the Abkari Act and Rules, including mandatory duties and potential imprisonment for contraventions in certain statutes. See discussions around compounding and penalties in Karnataka/Uttar Pradesh contexts cited in sources. [015000557?], [MURUGAN AND CO. VS STATE OF MYSORE - 1974 0 Supreme(Kar) 20], [State of Kerala vs T.R. Vijayakumar - 2025 0 Supreme(Ker) 1233] "Legal comments from the given sources with references" - See bullet points below (formatted as: "Keyword" - Summary - [Source Reference]) "Transfer of liability for excise duty" - Incidence of excise duty is anchored to manufacture/production; its collection can be deferred to later stages (e.g., sale or removal) by statutory design, with the primary liability on the manufacturer; see Kerala/Karnataka jurisprudence confirming liability attaches to manufacturer though collection can be staged. [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435], [MURUGAN AND CO. VS STATE OF MYSORE - 1974 0 Supreme(Kar) 20], [State of Kerala VS K. S. Distillery - 2010 0 Supreme(Ker) 256] "Wastage allowance applicability to imported goods" - Rule 7(5) of Kerala Foreign Liquor Rules, 1975 requires wastage allowances for imported spirits to be determined by Kerala Distillery and Warehouse Rules; even if Section 55 does not expressly mention "imported," wastage allowances apply to imported liquor per combined reading of Rules. [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223], [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730] "Wastage calculation method" - Rule 55 and Form D-8/Rule 34 framework provide measurement of wastage in transit; 1% (wooden casks) or 0.1% (metallic containers) allowances per 400 km, max 4% (wooden) or 0.5% (metallic); excess wastage leads to duty liability. Proviso allows rebuttal if deficiency could not have been prevented. [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223], [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730], [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730], [United Spirits Ltd. VS State of Kerala - 2015 0 Supreme(Ker) 1684] "Imported vs. domestic wastage rate alignment" - Kerala approach (post-1984 amendment) standardizes wastage rates for imported and in-state liquor via Rule 7(5) and R.55; court affirmed this alignment to avoid revenue leakage and ensure uniform treatment. [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730], [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223] "Bond and indemnity mechanics" - Removal of spirits from distilleries/warehouses requires an indemnity bond; Rule 7/Rule 47 alignment; Form FL/PD bonds illustrate security and payment obligations for export/removal of spirits; failure to deliver triggers duty payment obligations. [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435], [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [015000 nef?] "Alternative remedies and jurisdiction" - Kerala Abkari Act and Kerala Distillery Rules provide R.42 appeal pathways; writ petitions may be entertained under Art. 226; courts consider whether to direct refund of deposits or adjust against liabilities; jurisdiction concerns arise in inter-state/external trade scenarios. [STATE OF KERALA VS MC. DOWELL & CO. LTD. - 1988 0 Supreme(Ker) 97], [J. P. DISTILLERIES PRIVATE LIMITED, BANGALORE VS STATE OF KARNATAKA - 1997 0 Supreme(Kar) 49] "Export verification certificates and duties" - In export verification regimes (S.17, S.18), courts have held that verification timelines can be directory; duties on exported IMFL may be demanded if verification is timely but not strictly mandatory; deposit refunds ordered in some cases. [STATE OF KERALA VS MC. DOWELL & CO. LTD. - 1988 0 Supreme(Ker) 97], [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435] "Duty on rectified spirit and packaging" - West Bengal/Punjab/Karnataka line of cases discuss whether packaging charges or bottling activities fall within manufacture or service tax; in Kerala context, apportioned duties apply to rectified spirit when used to produce IMFL; packaging charges may be treated as service components rather than manufacture. [State of Kerala vs T.R. Vijayakumar - 2025 0 Supreme(Ker) 1233], [DURGA DISTILLERY VS EXCISE COMMISSIONER - 1989 0 Supreme(Kar) 330] "Role of KSBC monopoly in Kerala" - Post-1984 monopoly shift to KSBC for wholesale IMFL affects who pays and who collects excise duty; liability remains on manufacturers but collection can be routed via KSBC arrangements; cases discuss turnover tax implications and whether duty paid by KSBC is part of turnover. [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435], [Co-operative Company LTD. VS State Of U. P. - 2001 3 Supreme 289] "Duty on wastage in transit (rectified spirit) - evidentiary burden" - The importer bears burden to prove wastage could not be prevented; if not proven, presumption that excess wastage equates to imported quantity stands. R.55/R.11 interplay governs this. [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223], [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730] "Interim custody and seizure disputes" - When seizures of foreign liquor occur in transit, courts may grant interim custody to customs, with compliance requirements under Foreign Liquor Rules and Abkari Act; reflects inter-department procedural interplays. [ASSISTANT COMMISSIONER OF CUSTOMS VS STATE OF KERALA - 2010 0 Supreme(Ker) 881], [United Spirits Ltd. VS State of Kerala - 2015 0 Supreme(Ker) 1684] "Examples of related excise disputes" - Several Indian High Court/Supreme Court decisions cited illustrate the broader framework: Karnataka Excise Act cases on duty liability and wastage, Punjab and Delhi cases on duty attachment timing, and Bihar case on VAT interplay with excise duties. These illustrate consistency of core principles across states. [SREE BALAJI ENTERPRISES, BANGALORE VS EXCISE COMMISSIONER IN KARNATAKA - 2007 0 Supreme(Kar) 29], [SREE BALAJI ENTERPRISES LESSEES: BANGALORE GRAPE WINERY (P) LTD. VS EXCISE COMMISSIONER IN KARNATAKA, JOINT COMMISSIONER OF EXCISE DISTILLERIES - 2007 0 Supreme(Kar) 30], [HOWRAH INDL. ESTATE BONDED WAREHOUSE VS COLLECTOR OF CUSTOMS - 1992 0 Supreme(Cal) 98], [MODI INDUSTRIES LIMITED VS LIEUTENANT GOVERNOR DELHI - 1992 0 Supreme(Del) 314] "Overtime/establishment charges" - Kerala cases discuss establishment costs and overtime-related charges for excise staff; such costs are scrutinized against constitutional limits and statutory provisions; retrospective adjustments were found to require careful alignment with rule changes. [Kerala State Excise Staff Association VS State of Kerala - 1998 0 Supreme(Ker) 666], [United Spirits Ltd. VS State of Kerala - 2015 0 Supreme(Ker) 1684] "Remedies for over-collection or misapplication" - Courts have ordered refunds of excess deposits or duties where demands were found illegal or beyond statutory power; reassessment/remedial action is typical in Abkari/Distillery matters. [Poison Distillery VS State of Kerala - 1988 0 Supreme(Ker) 474], [Devicolam Distilleries Ltd VS State of Kerala, represented by The Secretary to Government, Taxes Department, Secretariat - 2018 0 Supreme(Ker) 574] "Jurisdictional notes on imports and warehousing" - Importer rights to deposit goods in customs/warehouses and the interplay with local Kerala Abkari/Distillery Rules require careful attention to Section 61/68-like provisions in Customs Acts when imported goods are warehoused; the nexus between customs warehousing and excise duties is nuanced. [ASSISTANT COMMISSIONER OF CUSTOMS VS STATE OF KERALA - 2010 0 Supreme(Ker) 881], [Naresh Goyal, Chairman, M/s. Jet Airways (India) Pvt. Ltd. Mumbai VS Circle Inspector of Excise - Crimes (2013)], [HOWRAH INDL. ESTATE BONDED WAREHOUSE VS COLLECTOR OF CUSTOMS - 1992 0 Supreme(Cal) 98] "Key takeaway" - The Kerala Distillery and Warehouse Rules, 1968, and related Kerala Abkari Act provisions establish a structured regime for import, storage, wastage, and duty on spirits; wastage allowances and proper bonds are central, with judicial decisions clarifying the boundaries between manufacture vs. service/packaging, the timing of duty incidence, and remedies for improper demands. [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223], [United Spirits Ltd. VS State of Kerala - 2015 0 Supreme(Ker) 1684], [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435]
| S.DISTILLERY AND WAREHOUSE RULES
Legal Comments "Wastage allowance" - The rules provide a fixed wastage allowance for transit losses (1% per 400 km up to 4% for wooden casks; 0.1% up to 0.5% for metallic containers) and a mechanism to levy duty on excess wastage - [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165] "Imported spirit wastage applicability" - Under Rule 7(5) of the Kerala Foreign Liquor (Compounding, Blending and Bottling) Rules, 1975, wastage allowance applies to imported spirit, and is regulated by the Kerala Distillery and Warehouse Rules 1968; the rate is determined by R.55, even for imported stock - [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165] "Wastage liability presumption" - Where wastage in transit exceeds permissible limits, duty at the tariff rate on the excess is payable, with a proviso allowing refund if deficiency could not have been prevented by proper care and consumption could not occur - [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730], [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165] "Judicial confirmation of wastage framework" - Kerala High Court upheld that distillery/blending units can claim wastage allowances for imported spirit under R.7(5) and R.55; rejection of circular restricting wastage claims - [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165] "Duty upon removal vs production" - The general principle across Karnataka/Kerala precedents: excise duty is a tax on manufacture/production but may be levied at a later stage (e.g., on removal or sale) per Ss. 22/23 Abkari Act and Rule frameworks; the taxing event need not be at the moment of production - [SREE BALAJI ENTERPRISES, BANGALORE VS EXCISE COMMISSIONER IN KARNATAKA - 2007 0 Supreme(Kar) 29], [SREE BALAJI ENTERPRISES LESSEES: BANGALORE GRAPE WINERY (P) LTD. VS EXCISE COMMISSIONER IN KARNATAKA, JOINT COMMISSIONER OF EXCISE DISTILLERIES - 2007 0 Supreme(Kar) 30], [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435] "Import vs manufacture liability debate" - In Kerala and Karnataka lines, liability to pay excise duty often remains with the manufacturer/exporter, even if duty is collected via bonds or via KSBC or other intermediaries; court decisions discuss shifting collection vs incidence, but generally uphold manufacturer as liable unless statute provides otherwise - [Poison Distillery VS State of Kerala - 1988 0 Supreme(Ker) 474], [SREE BALAJI ENTERPRISES, BANGALORE VS EXCISE COMMISSIONER IN KARNATAKA - 2007 0 Supreme(Kar) 29], [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435] "Bonded warehouse interplay" - Warehousing rules (Section 59/68 and related) create a framework where warehoused goods may be stored pending clearance; interest on warehoused goods and the need for bonds are governed by Customs Act provisions (Sections 57-68) and Hyderabad/Madhya Pradesh analogues, with issues of jurisdiction and limitation - [HOWRAH INDL. ESTATE BONDED WAREHOUSE VS COLLECTOR OF CUSTOMS - 1992 0 Supreme(Cal) 98], [DURGA DISTILLERY VS EXCISE COMMISSIONER - 1989 0 Supreme(Kar) 330], [Sun Shine Bar, Vijayanagaram VS Commissioner of A. P. Excise, Hyderabad - 1980 0 Supreme(AP) 356], [Central Warehousing Corporation New Delhi VS Central Bank of India Ltd. , Hyderabad - 1973 0 Supreme(AP) 26] "Interest on warehoused goods" - Section 61(2) interest accrues on the duty when goods are exigible; cases hold interest is payable only on the principal amount due and from the point the duty becomes exigible, not for pre-warehousing periods - [HOWRAH INDL. ESTATE BONDED WAREHOUSE VS COLLECTOR OF CUSTOMS - 1992 0 Supreme(Cal) 98], [Vijai Narain Products Private Limited VS Union of India - 1998 0 Supreme(Mad) 694], [Shaw Wallace Distilleries Ltd. VS STATE OF WEST BENGAL - 2011 0 Supreme(Cal) 1250] "Jurisdiction and territorial limits" - Indian cases on warehousing (Hyderabad, Allahabad etc.) emphasize Section 20 CPC Explanation II for corporate presence and subordinate offices as establishing jurisdiction; combined with warehousing regulations to determine where suits may be filed - [Central Warehousing Corporation New Delhi VS Central Bank of India Ltd. , Hyderabad - 1973 0 Supreme(AP) 26], [Vinayak Beer and Wine Stores VS Commercial Tax Officer, X Circle, Hyderabad - 1982 0 Supreme(AP) 378] "Exclusive privilege tenders and discretion" - In Uttar Pradesh and similar contexts, tender processes for exclusive wholesale rights are constrained by statutory conditions (Conditions 13-15, Rule 417) and are subject to judicial review; winners must meet statutory criteria and cannot be arbitrarily favored - [Sir Shadi Lal Distillery and Chemical Works, Muzaffarnagar VS State of U. P. - 1977 0 Supreme(All) 96] "Licence fee and additional charges" - Karnataka cases scrutinize licence fee quantum, including additions like Rule 7-A Bangalore transit levy; courts have scrutinized the validity of levy increases and the delegated authority to impose fees, emphasizing procedural compliance and statutory limits - [J. P. DISTILLERIES PRIVATE LIMITED, BANGALORE VS STATE OF KARNATAKA - 1997 0 Supreme(Kar) 49], [KAP CHEM LIMITED, BANGALORE VS STATE OF KARNATAKA - 2001 0 Supreme(Kar) 570] "Regulatory scheme for import/export vs. in-state sale" - Decisions discuss whether excise duty on imported liquor can be collected from importers vs. manufacturers; multiple rulings reiterate that duty is on manufacture but collection can be arranged through bonds or depots, with constitutional limits and notifications guiding who ultimately pays and when - [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435] "Overtime/remuneration challenges for excise staff" - Amendments (e.g., Rule 424? and related) on overtime/establishment charges are scrutinized; courts have considered whether overtime fees constitute service charges vs. regular pay, with constitutional limits in government employee remuneration amendments - [Kerala State Excise Staff Association VS State of Kerala - 1998 0 Supreme(Ker) 666], [ASSISTANT COMMISSIONER OF CUSTOMS VS STATE OF KERALA - 2010 0 Supreme(Ker) 881] "Export/monopoly concerns and pricing" - Kerala Abkari Act discussions show government monopolies (KSBC) and their impact on duty incidence, with emphasis that some levies are not strictly “duty of excise” but privilege payments for wholesale monopolies; this affects how turnover tax and excise duties are treated in computations - [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435], [J. P. DISTILLERIES PRIVATE LIMITED, BANGALORE VS STATE OF KARNATAKA - 1997 0 Supreme(Kar) 49] "Transit wastage claims in different modes" - Rule 55 differentiates wastage allowances by container type (wooden vs metal/tankers) and allows deficiency-based duty; courts have treated transit wastage allowances as part of the registered framework allowing recovery for excess wastage beyond permitted limits - [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730], [Modi Distillery VS State Of Uttar Pradesh - 2022 0 Supreme(All) 820] "Proviso-based relief for unavoidable wastage" - The wastage regime includes a proviso allowing waiver where deficiency could not be prevented by proper care and precaution and cannot pass into consumption; this keeps room for equitable relief - [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730], [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165] "Bond forms and indemnities" - Bond concepts (PD15, Form VI) and indemnity bonds bind distillers to pay duty on exports/exports not delivered; the enforceability and Stamp Act treatment (bond vs. agreement) have been litigated, with several rulings clarifying the binding nature and stamp requirements - [Modi Distillery VS State Of Uttar Pradesh - 2022 0 Supreme(All) 820], [State Of Kerala VS Mcdowell And Company LTD. - 1994 0 Supreme(SC) 234] "Procedural due process in licence renewals" - Courts emphasize that license renewal requires valid existing licences; retrospective renewal or equity relief depends on compliance with procedural rules and statutory discretion of licensing authorities; improper renewal can be quashed - [DURGA DISTILLERY VS EXCISE COMMISSIONER - 1989 0 Supreme(Kar) 330] "Overarching theme" - The Kerala Distillery and Warehouse Rules, 1968, together with Abkari Act provisions, create an integrated framework for licensing, storage, transfer, wastage allowance, duty liability, bond obligations, and dispute resolution; courts frequently interpret these statutes through the lens of fairness and lawful exercise of delegated powers - [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State of Kerala VS Polsons Distillery - 2017 0 Supreme(Ker) 1133]
References- Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165- STATE OF KERALA VS MC. DOWELL & CO. LTD. - 1988 0 Supreme(Ker) 97- SREE BALAJI ENTERPRISES, BANGALORE VS EXCISE COMMISSIONER IN KARNATAKA - 2007 0 Supreme(Kar) 29- SREE BALAJI ENTERPRISES LESSEES: BANGALORE GRAPE WINERY (P) LTD. VS EXCISE COMMISSIONER IN KARNATAKA, JOINT COMMISSIONER OF EXCISE DISTILLERIES - 2007 0 Supreme(Kar) 30- J. P. DISTILLERIES PRIVATE LIMITED, BANGALORE VS STATE OF KARNATAKA - 1997 0 Supreme(Kar) 49- Poison Distillery VS State of Kerala - 1988 0 Supreme(Ker) 474- Kerala State Excise Staff Association VS State of Kerala - 1998 0 Supreme(Ker) 666- KAP CHEM LIMITED, BANGALORE VS STATE OF KARNATAKA - 2001 0 Supreme(Kar) 570- HOWRAH INDL. ESTATE BONDED WAREHOUSE VS COLLECTOR OF CUSTOMS - 1992 0 Supreme(Cal) 98- Vijai Narain Products Private Limited VS Union of India - 1998 0 Supreme(Mad) 694- Central Warehousing Corporation New Delhi VS Central Bank of India Ltd. , Hyderabad - 1973 0 Supreme(AP) 26- Shaw Wallace Distilleries Ltd. VS STATE OF WEST BENGAL - 2011 0 Supreme(Cal) 1250- State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435- Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730- Modi Distillery VS State Of Uttar Pradesh - 2022 0 Supreme(All) 820- ASSISTANT COMMISSIONER OF CUSTOMS VS STATE OF KERALA - 2010 0 Supreme(Ker) 881- ిప S.INSTRUCTIONS RELATING TO GAUGE AND PROOF AND ISSUE OF SPIRITS
Legal Comments "Scope and purpose" - Kerala Distillery and Warehouse Rules, 1968 govern establishment, operation, and supervision of distilleries/warehouses, including issue, transport of spirits and inspection; Section relates to gauge/proof and issue of spirits. [“Devicolam Distilleries Ltd VS State of Kerala, represented by The Secretary to Government, Taxes Department, Secretariat - 2018 0 Supreme(Ker) 574”] "Section content — general idea" - Section INSTRUCTIONS RELATING TO GAUGE AND PROOF AND ISSUE OF SPIRITS covers measurement, verification, and delivery of spirits from distilleries/warehouses under rules; foundational to how wastage and transit losses are treated. [“Devicolam Distilleries Ltd VS State of Kerala, represented by The Secretary to Government, Taxes Department, Secretariat - 2018 0 Supreme(Ker) 574”] "Wastage framework (transit) - statutory base" - Rule 55 and Rule 11 (Transit Wastage) set out allowances for wastage in transit and levy of duty on excess wastage, with proviso for refund if deficiency could not have been prevented; this frames excess wastage as duty on imported quantity when applicable. [“State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223”, “Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730”] "Wastage and imported rectified spirit" - Wastage allowances apply to imported as well as state-produced rectified spirit via Rule 7(5) and Rule 55, with later Kerala decisions clarifying applicability to imported stock. [“Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165”, “SREE BALAJI ENTERPRISES, BANGALORE VS EXCISE COMMISSIONER IN KARNATAKA - 2007 0 Supreme(Kar) 29”, “UGAR SUGAR WORKS LIMITED (DISTILLERY UNIT), UGARKHERD, BELGAUM VS STATE OF KARNATAKA - 2004 0 Supreme(Kar) 287”] "Liability focus — duty on production vs. issue" - Kerala/ Karnataka line of cases holds excise duty is primarily a levy on the finished article produced or issued from distilleries/warehouses; levy can be assessed at or after production/issuance, including post-production stages per decisions like Mis. Shinde Brothers and related Kerala/Karnataka authorities. [“00900011458” (contextual), “THIRUMALA DISTILLERIES, TUMKUR VS STATE OF KARNATAKA - 2002 0 Supreme(Kar) 213”] "Distillery duty incumbency" - The primary liability to pay excise duty rests with the manufacturer; in Kerala, despite KSBC monopoly for wholesale, the duty liability remained with distilleries, with certain arrangements allowing KSBC to pay on their behalf in some periods, but not to defeat manufacturer's liability. [“Devicolam Distilleries Ltd VS State of Kerala, represented by The Secretary to Government, Taxes Department, Secretariat - 2018 0 Supreme(Ker) 574”, “State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435”] "Bonded/removal framework" - Rule 47 (removal of spirits from distilleries/warehouses under bond) and Rule 50/52 establish movement under bond and payment of duty before removal; bonds/indemnities secure duty payment. [“State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435”] "Overtime/remuneration context" - Amendments to rules (e.g., Kerala 1984/Rules) and related jurisprudence discuss overtime/remuneration and their enforceability; while not central to gauge/proof, these illustrate regulatory breadth around distillery operations. [“Kerala State Excise Staff Association VS State of Kerala - 1998 0 Supreme(Ker) 666”] "Export and bond mechanics" - Provisions governing export of IMFL and rectified spirit involve bonds for payment if not delivered; bonds serve as security for duty on exported stock; case law confirms duty attaches on export/stock not delivered. [“State Of Kerala VS Mcdowell And Company LTD. - 1994 0 Supreme(SC) 234”, “Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165”] "Verification and time limits" - Time limits for production of verification certificates in export/verification contexts are directory rather than mandatory, with duties challenged if misapplied; echoes the principle that procedural timings in excise can be directory. [“STATE OF KERALA VS MC. DOWELL & CO. LTD. - 1988 0 Supreme(Ker) 97”] "Wastage computation mechanics" - Rule 55 sets detailed computation for wastage allowances (1% for wooden casks, 0.1% for metal containers, with caps); excess wastage triggers duty, subject to proofs of preventability. [“State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223”, “Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730”] "Judicial test – vires and interpretation" - Courts strike down rules that overstep statute (e.g., Rule 67 ultra vires in AP case); ensure rule-making stays within Section 71 powers and the Act’s Schedule. [“DURGA DISTILLERY VS EXCISE COMMISSIONER - 1989 0 Supreme(Kar) 330”] "Overarching constitutional frame" - Kerala Abkari Act and Kerala Distillery Rules fit within Article 265 and List II entries; duties must align with statutory descriptions of excise, and rules must fall within delegated rule-making power. [“State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223”], [“State of Kerala VS K. S. Distillery - 2010 0 Supreme(Ker) 256”] "Interplay with other acts" - Cross-referenced cases involve Abkari Act, Distillery Rules, and Board Rules; in several judgments, the court emphasizes that levy is on excisable articles and not merely a contractual/service charge, preserving statutory tax character. [“State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223”, “Vindhyachal Distilleries Pvt. Ltd. VS State of Madhya Pradesh - 2006 0 Supreme(MP) 594”] "Duty on transit losses – presumption and rebuttal" - The law recognizes a presumption that excess transit wastage implies import into the state, which the importer can rebut by presenting materials to show non-import or non-detrimental transit; if not rebutted, duty may be recoverable. [“Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165”] "Refund direction where overcharged" - Courts have directed refund of excess excise duty where demands were illegal or penalties not properly authorized, reinforcing taxpayer protections within excise administration. [“STATE OF KERALA VS MC. DOWELL & CO. LTD. - 1988 0 Supreme(Ker) 97”], [“The Co Operative Sugars Ltd VS Govt Of Kerala - 1994 0 Supreme(Ker) 433”] "Notable Scope Point - packaging vs manufacture" - In packaging-service debates (e.g., packaging charges under Rule 65(76)(b) as service tax), courts clarified that packaging activities could fall outside traditional "manufacture" and may attract service tax, illustrating boundary between manufacturing duty and ancillary services; relevant to gauge/proof discourse by highlighting the substance of transactions. [“Vindhyachal Distilleries Pvt. Ltd. VS State of Madhya Pradesh - 2006 0 Supreme(MP) 594”] "Export-duty bonds clarity" - Bond-based export obligations ensure payment on short delivery or non-delivery of exported rectified spirit; bonds are integral to ensuring govt revenue from exports. [“State Of Kerala VS Mcdowell And Company LTD. - 1994 0 Supreme(SC) 234”] "Writ petitions and interim orders" - Kerala judgments show courts can dismiss writs for frivolous interim relief and impose exemplary costs where misrepresentation or improper conduct is alleged in petitions (contextual relevance to procedural handling). [“Devicolam Distilleries Ltd VS State of Kerala, represented by The Secretary to Government, Taxes Department, Secretariat - 2018 0 Supreme(Ker) 574”] "Key takeaway" - Section IN RELATING TO GAUGE AND PROOF AND ISSUE OF SPIRITS anchors measurement, verification, and legitimate collection of duty via the established machinery; it interacts with wastage allowances, transit rules, and bond-based removals to determine when and how excise duties attach to stock moving through distilleries and bonded warehouses. [“Devicolam Distilleries Ltd VS State of Kerala, represented by The Secretary to Government, Taxes Department, Secretariat - 2018 0 Supreme(Ker) 574”]
S.PLANT
Legal Comments "Scope of Section" - Wastage allowances for imported spirit apply under R.55 read with R.7(5) to imported spirits; wastage rate set in Rule 55 governs both imported and domestic, via Kerala Foreign Liquor Rules cross-application [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165]. "Essential ingredients" - Wastage allowances (1% per 400 km, max 4% in wooden vessels; 0.1% per 400 km, max 0.5% in metallic/tanker containers) plus provision for actual loss and duty on excess wastage as per Rule 55 and proviso; duty payable at tariff rate for excess wastage where not accounted for satisfactorily [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730]. "Introduction" - Kerala Distillery and Warehouse Rules (1968) and Abkari Act regulate import, production, storage, transit, and duty on spirits; Rule 7(5) and Rule 55 govern wastage allowances and duty implications for imported as well as domestic liquor [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223], [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730]. "What section Says" - Rule 55 provides wastage allowances; Rule 7(5) ties wastage allowance to imported spirits via the imported-case framing; aggregation of wastage and duty applies where excess wastage is not satisfactorily accounted; Section 17/18 mechanisms contextualize excise duty on manufacture/import depending on stage and instrument; the presumption of importation for excess wastage applies unless rebutted [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223], [State of Kerala VS K. S. Distillery - 2010 0 Supreme(Ker) 256]. "Scope of Section" - Distillery/Blending units may claim wastage allowances for imported spirits under R.7(5) read with R.55; the mechanism covers wastage in transit and in transit loss; the scope includes both imported and in-state spirits per amendments and cross-notifications [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223], [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165]. "Essential ingredients" - Wastage calculation methodology (London Proof litres; end-quarter accounting; provisional allowances; actual loss allowed if proven) and circulars that interpret R.7(5) to include imported spirit wastage; duty on excess wastage remains payable if not satisfactorily explained [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730]. "Punishment for Section" - Not a criminal section; penalties arise as charges/claims for excise duty deficiency or demand for duty on excess wastage; if excess wastage is not accounted or rebutted, duty payable; where illegitimate demands are raised, courts have struck down or remitted such demands and ordered refunds (e.g., warded against excess wastage demands; case law dismissals/remittals) [Poison Distillery VS State of Kerala - 1988 0 Supreme(Ker) 474], [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223], [The Co Operative Sugars Ltd VS Govt Of Kerala - 1994 0 Supreme(Ker) 433]. "Judicial trend (select cases)" - Kerala High Court and Supreme Court have repeatedly held that: (a) duty is primarily on manufacture but may be collected later; (b) wastage rules apply to imported as well as domestic, via R.7(5) and R.55; (c) challenges to wastage-duty computations must be grounded in statutory provisions; (d) where legality is unsettled, remand or refund orders follow (McDowell & Co.; Devicolam Distilleries; State of Kerala v. K.S. Distillery) [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [Poison Distillery VS State of Kerala - 1988 0 Supreme(Ker) 474], [Devicolam Distilleries Ltd VS State of Kerala, represented by The Secretary to Government, Taxes Department, Secretariat - 2018 0 Supreme(Ker) 574], [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435]. "Essential ingredients" - Bonding/indemnity framework for removal of spirits and import; Rule 28 (hypothecation) and Rule 27 (security deposit) are required alongside Rule 7(1)-(4) and 11 to ensure payment of duties on removal or export; security deposits not linked to production capacity; binding to observe licence conditions (Rule 28) [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State of Kerala VS Polsons Distillery - 2017 0 Supreme(Ker) 1133]. "Scope of Section" - The rules create a comprehensive regime tying wastage allowances to transit and import status; a distillery may import under Form FL, but wastage allowances are regulated by R.55 (and cross-Rules) to determine liability for excess wastage; if import-related wastage exceeds allowances, duty is due [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223]. "Penalty (non-compliance)" - If wastage is proven to exceed allowed limits and not satisfactorily explained, the licensee pays duty at tariff rate for the excess; if proper care/precautions are shown, refund may be ordered; improper or arbitrary levies have been struck down by courts (e.g., excess wastage/demand quashed) [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [Poison Distillery VS State of Kerala - 1988 0 Supreme(Ker) 474]. "Consistency with statutory framework" - The Kerala Abkari Act, Distillery and Warehouse Rules (1968) and the Kerala Foreign Liquor Rules (1975) together authorize wastage allowances and the tariff-duty regime; amendments (1984) unify wastage rates across imported and domestic, aligning Rule 7(5) with Rule 55; court interpretations uphold consistency with Art. 14 and substantive due process in taxation within Excise framework [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165], [015000WL references]. "Operational principle" - The burden of proof lies on the licensee to establish actual wastage within permitted limits; failure to prove leads to duty liability; the presumption of importation for excess wastage stands unless rebutted with evidence [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223], [Messrs Elite Distilleries, Beverages Co. Rep. by its Proprietor T. R. Vijayakumar VS State Of Kerala - 2011 0 Supreme(Ker) 730]. "Remedies and remedies framework" - Writ petitions challenging excise/duty or wastage demands: courts have dismissed appeals (State of Kerala v. McDowell) or remitted for fresh disposal with directions to Board of Revenue; alternative remedy under R.42 of the Distillery Rules may be available depending on the nature of the order/appellate remedy [Poison Distillery VS State of Kerala - 1988 0 Supreme(Ker) 474], [Circle Inspector of Excise VS Super Star Distilleries - 2004 0 Supreme(Ker) 165]. "Cross-jurisdictional relevance" - Several other states’ excise/duty regimes exhibit similar mechanics (Karnataka, AP, UP) where excise duty attaches to manufacture but collection can be deferred; cases on warehousing, duty on wastage, and compounding/fee regimes illustrate the common jurisprudence: duty on manufacture; collection at sale/issue under bond; wastage allowances; security for duty [SREE BALAJI ENTERPRISES, BANGALORE VS EXCISE COMMISSIONER IN KARNATAKA, BANGALORE - 2007 0 Supreme(Kar) 31], [State Of Kerala VS Maharashtra Distilleries LTD. - 2005 4 Supreme 435], [MURUGAN AND CO. VS STATE OF MYSORE - 1974 0 Supreme(Kar) 20]. "Reference points" - Rule 55(4) (transit wastage over 0.5% in transit) debated; Kerala SC/HC decisions hold that wastage allowances operate within statutory framework and do not create unlimited liability on imported stock; the 0.5% benchmark may be subject to judicial scrutiny (State of Kerala v. McDowell; Basheer, J. decisions) [State of Kerala VS K. S. Distillery - 2010 0 Supreme(Ker) 256], [State of Kerala VS Mc Dowell & Co. Ltd. - 1990 0 Supreme(Ker) 223]. "Policy and public interest" - The rules balance revenue collection with industrial development; court schemes allow restart of manufacturing with safeguards where pollution or environmental concerns exist (though not directly in PLANT Section commentary, it reflects the broader regulatory ethos) [Rajiv Ranjan Singh @ Lallan Singh VS State of Bihar - 1991 0 Supreme(Pat) 16], [United Spirits Ltd. VS State of Bihar - 2023 0 Supreme(Pat) 1108]. "Format note" - References are provided in square brackets after each bullet to indicate examples listed as [Source Identifier].
| | |
|
|










 AI Assistant


